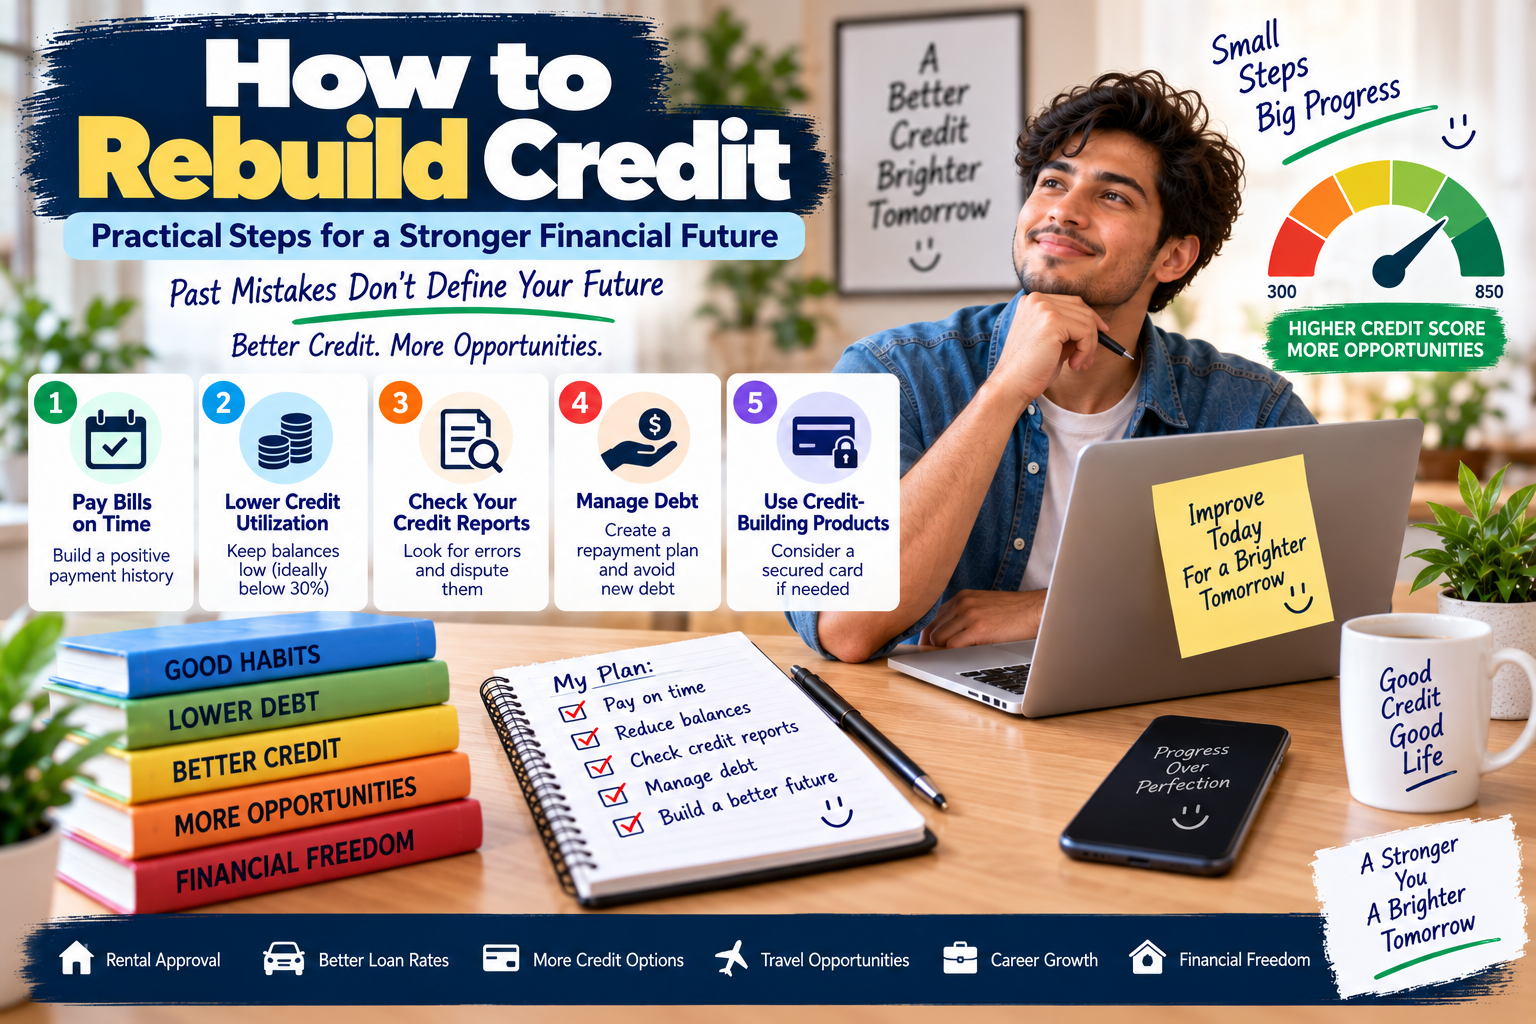
Rebuilding your credit can feel difficult after late payments, high credit card balances, collections, or other financial setbacks. However, learning how to rebuild credit is possible with consistent payments, responsible borrowing, and regular credit report monitoring. There is no instant solution, but the right steps can gradually improve your financial profile.
Whether your credit score is below 600 or you simply want to recover from past mistakes, this guide explains practical strategies for rebuilding credit in the United States.
Quick Answer: The most effective way to rebuild credit is to pay every bill on time, reduce credit card utilization, review your credit reports for errors, avoid unnecessary credit applications, and use credit-building products responsibly.
What Does It Mean to Rebuild Credit?
Rebuilding credit means improving your credit history and demonstrating that you can manage borrowed money responsibly.
Your credit profile may be affected by:
- Missed or late payments
- High credit card utilization
- Accounts in collections
- Defaults or charge-offs
- Bankruptcy
- Too many recent credit applications
- Limited credit history
- Incorrect information on your credit report
The effect of each issue depends on your overall credit history, the type of account, and the scoring model used.
Important: Accurate negative information generally cannot be legally removed simply by paying a credit repair company. However, inaccurate information can be disputed with the credit reporting company and the business that supplied the information.
1. Pay Every Bill on Time
Payment history is an important part of many credit scoring models. Missing payments can damage your credit profile, particularly when the payment becomes significantly delinquent.
To avoid future late payments:
- Set up automatic minimum payments.
- Use calendar reminders before every due date.
- Keep enough money in your bank account.
- Contact your lender early if you expect payment difficulties.
- Pay more than the minimum whenever your budget allows.
An automatic payment system can help prevent accidental missed payments, but you should still monitor your account for errors or insufficient funds.
Example
Suppose you previously missed two credit card payments because you forgot the due dates. You begin using automatic payments and make every payment on time for the next 12 months.
Your credit score may not recover immediately, but the new positive payment history can support gradual improvement over time.
2. Reduce Your Credit Card Utilization
Credit utilization refers to how much of your available revolving credit you are using.
For example:
| Credit Limit | Balance | Utilization |
|---|---|---|
| $1,000 | $800 | 80% |
| $1,000 | $500 | 50% |
| $1,000 | $300 | 30% |
| $1,000 | $100 | 10% |
A high balance relative to your credit limit can negatively affect your credit score. Lower utilization is generally helpful, although there is no universal percentage that guarantees a particular score.
Practical strategies
- Pay down high-interest credit card balances.
- Avoid maxing out your cards.
- Spread spending across cards only if it helps you manage balances.
- Pay before the statement closing date when possible.
- Avoid taking on new debt solely to improve your utilization ratio.
Remember: You do not need to carry a balance and pay interest to build credit.
3. Review Your Credit Reports for Errors
Credit report errors may negatively affect your credit profile. Review your reports for incorrect information, including:
- Accounts that do not belong to you
- Incorrect late payment records
- Wrong account balances
- Incorrect credit limits
- Duplicate collection accounts
- Accounts incorrectly reported as open
- Identity theft-related accounts
You can obtain credit reports through AnnualCreditReport.com.
If you find inaccurate information, dispute it with the relevant credit reporting company and the company that provided the information.
What to include in a dispute
- Your personal identification details
- The account being disputed
- A clear explanation of the error
- Supporting documents
- A request for investigation and correction
Only dispute information that is genuinely inaccurate or incomplete.
4. Deal With Past-Due Accounts and Collections
Ignoring past-due accounts may allow the situation to become more complicated. First, identify the account owner, outstanding balance, payment status, and available repayment options.
Depending on your situation, you may consider:
- Paying the account in full
- Requesting a payment arrangement
- Negotiating with the creditor or collector
- Speaking with a nonprofit credit counselor
- Disputing a debt that you do not recognize or believe is inaccurate
Before making a payment or agreeing to a settlement, understand how the arrangement may affect your finances and credit reporting.
Be cautious about promises
No company can guarantee that accurate negative information will be removed from your credit report. Be careful with businesses that demand large upfront fees or promise an immediate credit score increase.
The Consumer Financial Protection Bureau provides information about debt collection practices and consumer rights.
5. Consider a Secured Credit Card
A secured credit card may be useful if you cannot qualify for a traditional unsecured credit card.
With many secured cards:
- You provide a refundable security deposit.
- The issuer assigns a credit limit, often related to the deposit.
- You use the card for manageable purchases.
- You make payments on time.
- The issuer may eventually offer an upgrade or return the deposit, depending on its policies.
Before applying, check:
- Annual fees
- Interest rate
- Security deposit requirements
- Whether payments are reported to major credit bureaus
- Upgrade and refund policies
Use the card only for purchases you can afford to repay.
A secured credit card is not free money. You remain responsible for your balance and payment obligations.
6. Avoid Applying for Too Many Credit Accounts
Applying for multiple credit cards or loans within a short period may result in hard inquiries and can indicate increased borrowing risk to lenders.
Avoid submitting applications simply because you want to test your approval chances.
Instead:
- Check eligibility requirements before applying.
- Review your credit report first.
- Compare fees and interest rates.
- Apply only for products that fit your financial situation.
- Avoid opening several accounts at once unless you have a clear reason.
Prequalification tools may sometimes allow you to check potential offers without a hard inquiry, but the terms and availability vary by lender.
7. Create a Repayment Plan for High-Interest Debt
High-interest debt can make rebuilding credit more difficult because a large part of your payment may go toward interest.
Two common repayment approaches are:
Debt avalanche method
Pay extra toward the debt with the highest interest rate while maintaining minimum payments on other accounts.
Potential benefit: You may reduce total interest costs.
Debt snowball method
Pay extra toward the smallest balance first while making minimum payments on other debts.
Potential benefit: Paying off smaller balances may provide motivation and simplify your finances.
Neither method automatically improves your credit score. Their primary purpose is to help you manage debt and reduce financial pressure.
8. Keep Older Accounts Open When Appropriate
The age of your credit accounts may influence some credit scoring models. Closing an older account is not always harmful, but it can affect your available credit, utilization, and overall credit profile.
Before closing an account, consider:
- Annual fees
- Whether the account is useful
- Your current utilization
- Your ability to control spending
- The issuer’s account closure policy
Do not keep an expensive or unsuitable account open only for credit history purposes. Your financial stability and ability to avoid unnecessary debt should come first.
9. Build a Realistic Monthly Budget
Credit improvement becomes harder when your expenses consistently exceed your income.
Create a simple monthly budget that includes:
| Category | Example |
|---|---|
| Housing | $1,000 |
| Utilities | $150 |
| Food | $350 |
| Transportation | $200 |
| Debt payments | $300 |
| Emergency savings | $150 |
| Other expenses | $250 |
The figures above are illustrative. Your actual budget should reflect your income, location, household size, and obligations.
Budgeting tips
- Track expenses for at least one month.
- Identify unnecessary subscriptions.
- Keep a small emergency reserve.
- Avoid using credit cards for expenses you cannot repay.
- Prioritize essential bills and minimum debt payments.
A budget can help you avoid repeating the financial problems that damaged your credit in the first place.
10. Monitor Your Credit Progress Consistently
Credit rebuilding takes time. Checking your credit information periodically can help you identify changes and track progress.
Monitor:
- Payment history
- Credit card balances
- Credit utilization
- New accounts
- Hard inquiries
- Collection accounts
- Errors or suspicious activity
You may see your score fluctuate even when you are following your repayment plan. Different lenders and credit scoring models may use different information.
Focus on building consistent financial habits instead of expecting a specific score increase every month.
How Long Does It Take to Rebuild Credit?
There is no fixed timeline for rebuilding credit. The recovery period depends on the severity and recency of negative information, your current credit profile, and your financial behavior going forward.
| Credit Problem | Possible Recovery Consideration |
|---|---|
| High credit utilization | Improvement may occur after reported balances decrease |
| Recent late payment | Its effect may reduce over time with positive payment history |
| Collections | Resolution and reporting depend on the account and circumstances |
| Bankruptcy | Its impact and reporting period depend on the bankruptcy type and applicable rules |
| Limited credit history | Building a consistent record may take several months or longer |
The CFPB states that most negative information can generally be reported for up to seven years, while certain bankruptcies may remain for up to ten years. Reporting periods and exceptions depend on the type of information and applicable law.
A negative item remaining on your report does not mean your credit score cannot improve during that period.
How to Rebuild Credit After Late Payments
If you have missed payments, follow these steps:
- Check your credit reports.
- Identify which accounts are past due.
- Bring overdue accounts current when financially possible.
- Contact creditors to discuss available hardship options.
- Set up payment reminders or automatic payments.
- Avoid additional late payments.
- Reduce credit card balances.
- Monitor your reports for incorrect information.
Example: Recovering After Late Payments
Imagine that a borrower missed a credit card payment after losing part of their income. They later create a budget, contact the lender, and establish a payment routine.
Their credit score may remain affected for some time, but consistently paying on time and reducing balances can help establish a stronger recent credit history.
The exact result will depend on the person’s complete credit profile.
How to Rebuild Credit After Collections
If an account is in collections, do not immediately assume that paying it will produce a specific credit score increase.
First:
- Confirm that the debt belongs to you.
- Review the amount and account details.
- Check whether the information is accurate.
- Understand your options for repayment or settlement.
- Keep written records of communications.
- Ask how any agreement will be documented.
If you dispute a debt, follow the applicable dispute process and retain supporting evidence.
If the debt is legitimate but unaffordable, consider speaking with a nonprofit credit counseling organization before agreeing to a repayment plan.
How to Rebuild Credit After Bankruptcy
Bankruptcy can have a significant effect on your credit profile, but it does not necessarily prevent you from rebuilding credit afterward.
Potential steps include:
- Maintaining reliable payments on current obligations
- Creating a realistic budget
- Monitoring your credit reports
- Avoiding unnecessary new debt
- Considering a secured credit card if appropriate
- Building an emergency savings fund
- Seeking qualified financial or legal guidance
The timing and process will depend on your bankruptcy type, discharge status, current debts, and financial circumstances.
Do not take on new credit simply to demonstrate activity. Only use borrowing products that you can manage responsibly.
Common Mistakes to Avoid While Rebuilding Credit
Mistake 1: Paying a company to remove accurate information
Accurate negative information generally cannot be removed simply because you pay a credit repair service.
Mistake 2: Applying for several credit cards at once
Multiple applications may lead to hard inquiries and additional debt risk.
Mistake 3: Carrying a balance to build credit
You do not need to pay interest to establish responsible credit usage.
Mistake 4: Ignoring credit reports
Errors can remain unnoticed if you never review your reports.
Mistake 5: Closing every credit account
Closing accounts without considering utilization and account history may affect your credit profile.
Mistake 6: Taking out expensive loans to improve your score
Borrowing money solely for credit-building purposes can create unnecessary interest costs and repayment pressure.
A Simple 90-Day Credit Rebuilding Plan
Days 1–30: Understand Your Situation
- Obtain and review your credit reports.
- List all debts and payment due dates.
- Identify past-due accounts.
- Create a monthly budget.
- Set up payment reminders.
Days 31–60: Reduce Financial Pressure
- Pay all bills on time.
- Reduce credit card balances where possible.
- Contact creditors about repayment options.
- Avoid unnecessary credit applications.
- Dispute genuine credit report errors.
Days 61–90: Build Consistency
- Continue making timely payments.
- Monitor your credit reports.
- Review your spending habits.
- Build emergency savings.
- Evaluate whether a secured credit card or credit-builder product is appropriate.
This plan does not guarantee a specific credit score increase. Its purpose is to establish sustainable financial habits.
Frequently Asked Questions
1. How can I rebuild credit quickly?
You can begin by paying all bills on time, reducing credit utilization, checking your credit reports for errors, and avoiding unnecessary applications. However, there is no guaranteed method for quickly increasing your credit score.
2. Can I rebuild credit with a 500 credit score?
Yes, rebuilding may be possible with a 500 credit score. Focus on payment consistency, reducing debt, correcting errors, and using credit-building products responsibly if you qualify.
3. How long does it take to rebuild credit after late payments?
The timeline varies depending on how recent and severe the late payments were and what happens afterward. Consistent on-time payments can help strengthen your credit history over time.
4. Can paying off collections improve my credit score?
Paying or settling a collection may resolve the debt, but the effect on your credit score depends on the scoring model, account details, and reporting practices. Do not assume payment guarantees a particular score increase.
5. Should I close credit cards with high interest rates?
You may consider closing an account if its fees or terms are unsuitable, but first evaluate how closure could affect your available credit and utilization. Avoid keeping an expensive account open solely for credit history.
6. Does checking my own credit score hurt my credit?
Checking your own credit score or credit report generally does not create a hard inquiry. However, the type of credit check matters, so understand whether an action is a soft or hard inquiry.
7. Can a secured credit card help rebuild credit?
A secured credit card may help when the issuer reports account activity to credit bureaus. Confirm the issuer’s reporting practices, fees, and terms before applying.
8. Can credit repair companies remove late payments?
A company generally cannot remove accurate negative information merely because you pay for its services. Inaccurate or incomplete information can be disputed through the appropriate process.
9. Does carrying a credit card balance improve credit?
No. Carrying a balance is not required to build credit. Paying your balance in full can help you avoid interest charges and manage utilization.
10. What is the first step in rebuilding credit?
The first step is understanding your current credit situation. Obtain your credit reports, identify negative information and outstanding debts, and create a realistic plan for timely payments and debt management.
Why Maintain Market Is Different
At Maintain Market, our goal is to explain financial topics in a practical and understandable way.
Instead of focusing only on credit score numbers, this guide covers:
- Credit report monitoring
- Debt repayment strategies
- Credit utilization
- Secured credit cards
- Collections and late payments
- Budgeting
- Long-term credit habits
Credit improvement is not about finding a secret shortcut. It is about understanding your financial situation and making consistent decisions that support your long-term goals.
Recommended Next Steps
If you are rebuilding credit, consider reviewing these related topics:
- Best secured credit cards
- Best credit cards for fair credit
- Personal loans for bad credit in the USA
- How to increase your credit score
- How to build credit fast
Always compare fees, interest rates, eligibility requirements, and repayment terms before applying for a financial product.
References
Consumer Financial Protection Bureau (CFPB) — How to Rebuild Your Credit
Practical guidance on timely payments, credit utilization, secured cards, and credit report errors.
Read the official guide
Consumer Financial Protection Bureau — Credit Reports and Scores
Information about credit reports, credit scores, credit repair scams, and consumer rights.
Explore credit reports and scores
Consumer Financial Protection Bureau — Debt Collection Resources
Guidance on debt collection practices, consumer rights, and handling collection accounts.
Explore debt collection resources
AnnualCreditReport.com — Official Free Credit Reports
The authorized website for accessing credit reports from Equifax, Experian, and TransUnion.
Access your official credit reports
Consumer Financial Protection Bureau — Ways to Build or Rebuild Credit
Guidance on secured credit cards and other responsible credit-building options.
Read credit-building guidance
Editorial Review
Search intent: Informational and practical guidance
Review focus: Accuracy, responsible financial guidance, clarity, and consumer protection
Disclaimer: This article is for educational purposes only and does not constitute personalized financial, legal, or credit counseling advice.