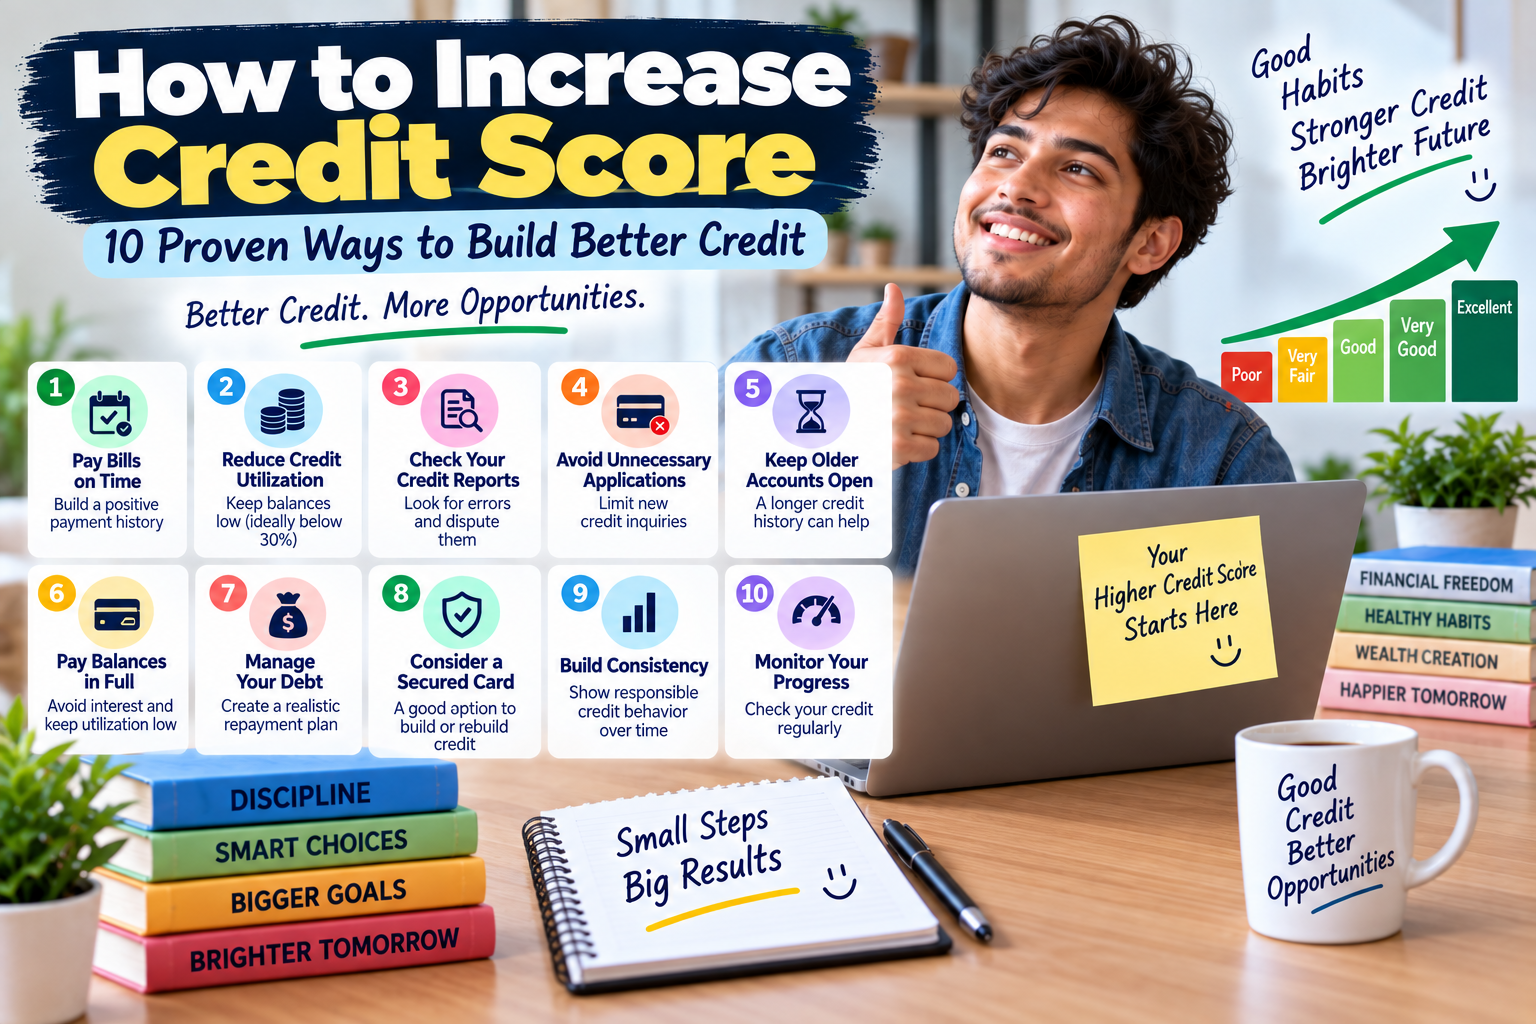
If you want to know how to increase credit score, the best approach is to build consistent financial habits. Paying bills on time, reducing credit card balances, checking your credit reports, and limiting unnecessary credit applications can help improve your credit profile over time.
Your credit score can influence your ability to qualify for credit cards, personal loans, mortgages, and competitive interest rates. However, there is no guaranteed shortcut to achieving a higher score.
This guide explains practical ways to improve your credit score in the United States, including strategies for people with bad credit, limited credit history, or high credit card balances.
Quick Answer: How to Increase Credit Score
The most effective steps generally include:
- Pay every bill on time.
- Reduce credit card utilization.
- Check your credit reports for errors.
- Avoid unnecessary credit applications.
- Keep older credit accounts open when appropriate.
- Pay credit card balances in full when possible.
- Manage existing debt responsibly.
- Consider a secured credit card if you need to build credit.
- Monitor your credit reports regularly.
- Give your credit history time to improve.
Your results depend on your current credit profile, the scoring model used, and the information reported by lenders.
How Credit Scores Work
Credit scores are calculated using information from your credit reports. Different lenders may use different scoring models, so the score you see may not be identical to the score used by a lender.
Common factors considered by credit scoring models include:
| Credit Factor | Why It Matters |
|---|---|
| Payment history | Shows whether you repay debts on time |
| Credit utilization | Measures how much revolving credit you use |
| Credit history length | Reflects your experience managing credit |
| Credit mix | Considers different types of credit accounts |
| New credit | Considers recent applications and accounts |
Not every scoring model weighs these factors in exactly the same way.
10 Effective Ways to Increase Your Credit Score
1. Pay Your Bills on Time
Payment history is one of the most important factors in many credit scoring models.
Late payments can negatively affect your credit profile, particularly when they become seriously overdue or are reported to credit bureaus.
What you can do:
- Set up automatic payments.
- Use payment reminders.
- Pay at least the minimum amount by the due date.
- Contact your lender if you are struggling to make a payment.
- Bring overdue accounts current as soon as possible.
Paying on time consistently is more valuable than making occasional large payments.
2. Reduce Your Credit Card Utilization
Credit utilization is the percentage of your available revolving credit that you are using.
For example:
| Total Credit Limit | Credit Card Balance | Utilization |
|---|---|---|
| $5,000 | $500 | 10% |
| $5,000 | $1,500 | 30% |
| $5,000 | $4,000 | 80% |
Higher utilization can negatively affect your credit score.
Many experts recommend keeping utilization below 30%, while lower utilization may be beneficial. You do not need to carry a balance to build credit.
Practical steps:
- Pay down high-interest card balances.
- Avoid maxing out credit cards.
- Make payments before the statement closing date when appropriate.
- Spread spending responsibly across available credit.
- Avoid taking on debt you cannot repay.
There is no single utilization percentage that guarantees a particular score.
3. Check Your Credit Reports for Errors
Errors on your credit report may negatively affect your credit score and future applications.
Look for:
- Accounts that do not belong to you
- Incorrect payment history
- Incorrect account balances
- Duplicate accounts
- Incorrect personal information
- Accounts listed as open after closure
You can obtain credit reports through AnnualCreditReport.com, the official federally authorized source.
If you identify inaccurate information, you may dispute it with the credit reporting company and the business that supplied the information.
Checking your own credit report does not hurt your credit score.
4. Avoid Unnecessary Credit Applications
Applying for multiple credit cards or loans within a short period may result in several hard inquiries.
Too many recent applications can affect your credit profile and may cause lenders to view your recent credit activity differently.
Before applying:
- Check eligibility requirements.
- Use prequalification when available.
- Apply only for credit you genuinely need.
- Avoid submitting multiple applications without comparing options.
- Review the terms and potential fees.
Prequalification may use a soft inquiry, but you should confirm the process with the lender.
5. Keep Older Credit Accounts Open When Appropriate
The age of your credit accounts can contribute to your credit profile.
Closing an older credit card may reduce your available credit and potentially increase your overall utilization if you have outstanding balances elsewhere.
However, keeping an account open is not always the best decision if it has expensive fees, security concerns, or encourages unaffordable spending.
Consider:
- Annual fees
- Account security
- Available credit limit
- Your spending habits
- Whether the account is useful
Do not keep an account open solely to improve your score if it creates financial problems.
6. Pay Your Credit Card Balance in Full
Carrying a credit card balance does not improve your credit score.
Paying your balance in full each month can help you:
- Avoid interest charges on purchases when applicable.
- Keep utilization lower.
- Manage debt more effectively.
- Avoid accumulating unnecessary interest.
If paying the full balance is not possible, pay at least the minimum due on time and create a plan to reduce the outstanding balance.
Never spend more than you can reasonably repay just to build credit.
7. Manage Your Existing Debt
Your existing debt obligations may influence how lenders evaluate your financial situation.
Large balances, missed payments, and high monthly debt payments can make it harder to qualify for new credit.
Useful steps include:
- List all outstanding debts.
- Record interest rates and minimum payments.
- Prioritize overdue accounts.
- Create a realistic repayment budget.
- Avoid taking on unnecessary new debt.
A debt repayment plan should fit your income and essential expenses.
8. Consider a Secured Credit Card
A secured credit card may be an option for people who are building or rebuilding credit.
These cards typically require a refundable security deposit, which may be connected to the credit limit. The issuer’s reporting practices and eligibility requirements vary.
Before choosing a secured card, check:
- Annual fees
- Security deposit requirements
- Interest rate
- Credit bureau reporting
- Upgrade opportunities
- Refund conditions
A secured card does not guarantee credit improvement. Responsible use and on-time payments are important.
Related guide: Best Secured Credit Cards
9. Build a Consistent Credit History
Credit improvement generally takes time. A longer history of responsible credit management can provide more information for scoring models.
You can build consistency by:
- Paying accounts on time.
- Keeping balances manageable.
- Avoiding unnecessary account closures.
- Applying for credit only when needed.
- Reviewing your credit reports regularly.
Do not open multiple accounts simply to increase your credit mix. New credit should serve a genuine financial purpose.
10. Monitor Your Credit Progress
Regularly reviewing your credit reports can help you identify changes and potential problems.
Monitor for:
- New accounts
- Unrecognized inquiries
- Payment reporting errors
- Changes in account balances
- Suspicious activity
Checking your own credit report is considered a soft inquiry and does not lower your score.
Credit monitoring services may provide alerts, but the information and scoring models available can differ between providers.
How to Increase Credit Score Fast
Some credit improvements may appear relatively quickly after updated information is reported, while others require months or longer.
Potentially faster actions include:
- Paying down high credit card balances.
- Correcting inaccurate information.
- Bringing overdue accounts current.
- Avoiding additional unnecessary credit applications.
However, no company can legitimately guarantee a specific credit score increase within a fixed timeframe.
Be cautious of services that promise to remove accurate negative information or offer instant credit repair.
How to Increase Credit Score From 500
If your credit score is around 500, focus on correcting the issues that are affecting your credit profile.
Recommended Steps
| Step | Purpose |
|---|---|
| Review credit reports | Identify errors and negative accounts |
| Pay bills on time | Establish consistent payment history |
| Reduce balances | Lower credit utilization |
| Address overdue debt | Prevent further negative reporting |
| Consider secured credit | Build credit if reported appropriately |
| Avoid unnecessary applications | Limit additional inquiries |
Your score may not improve immediately, particularly if you have recent serious delinquencies, collections, or other negative information.
How to Increase Credit Score With No Credit History
People with no credit history may need to establish a record of responsible borrowing.
Potential options include:
- Secured credit cards
- Student credit cards
- Credit-builder loans
- Products designed for limited credit history
Before opening an account, confirm whether the provider reports payment activity to the major credit reporting companies.
Debit cards, prepaid cards, and cash payments generally do not establish traditional credit history because they do not involve borrowing and repaying credit.
How Long Does It Take to Increase Your Credit Score?
The timeframe depends on the reason your score is low and how quickly your credit report changes.
| Situation | Possible Timeline |
|---|---|
| Lowering credit card balances | May reflect after updated reporting |
| Correcting reporting errors | Depends on the dispute process |
| Building payment history | Usually requires consistent payments over time |
| Recovering from late payments | Can take longer |
| Building credit from scratch | Often requires several months or more |
Credit scoring models use different calculations, and lenders may update information at different times.
Avoid promises of guaranteed results within seven, 30, or 60 days.
Common Mistakes That Can Hurt Your Credit Score
Mistake 1: Maxing Out Credit Cards
High utilization may negatively affect your credit score.
Mistake 2: Missing Minimum Payments
Late payments can damage your credit history and may lead to additional fees.
Mistake 3: Applying for Too Many Cards
Frequent applications may result in additional hard inquiries.
Mistake 4: Closing Accounts Without Planning
Closing accounts may reduce available credit and affect utilization.
Mistake 5: Paying for Guaranteed Credit Repair
Be cautious of companies promising guaranteed score increases or removal of accurate negative information.
Mistake 6: Carrying Debt for Credit Building
You do not need to pay interest or maintain debt to build a good credit score.
Frequently Asked Questions
1. How to increase credit score quickly?
You may improve your credit profile by reducing high credit card balances, paying bills on time, and correcting inaccurate credit report information. The speed of improvement depends on your credit history and when lenders report updated information.
No method guarantees a specific number of points within a particular timeframe.
2. Does paying credit cards in full increase your credit score?
Paying credit card balances in full can help you avoid interest and manage utilization. Consistent on-time payments and responsible credit use may support a stronger credit profile.
You do not need to carry a balance to build credit.
3. Can I increase my credit score without a credit card?
Yes, depending on your circumstances, you may build credit through qualifying installment loans or credit-builder products that report payments to credit bureaus.
However, not every financial product reports payment activity. Check the provider’s reporting policy before applying.
4. Does checking my credit score lower it?
Checking your own credit score generally does not lower it. Checking your own credit report is also not a hard inquiry.
A lender’s credit check during a credit application may involve a hard inquiry, so review the application terms.
5. How can I increase my credit score from 600 to 700?
Focus on paying bills on time, reducing credit utilization, checking for credit report errors, and avoiding unnecessary applications.
The time required varies depending on your credit history, outstanding debt, and negative information.
6. Can paying off debt increase my credit score?
Paying down revolving credit card balances may improve your utilization and potentially support a higher score. The result depends on your overall credit profile and the scoring model used.
Paying off an installment loan may have different effects and does not guarantee an immediate score increase.
7. Does closing a credit card hurt your credit score?
Closing a credit card can reduce your available credit and may increase your utilization percentage if you still have balances on other cards.
The effect depends on your credit profile, account history, and scoring model. Consider fees and financial needs before closing an account.
8. How often should I check my credit report?
You should review your credit reports regularly to identify errors and suspicious activity. You can access your reports through AnnualCreditReport.com.
Checking your own credit report does not hurt your credit score.
9. Can I increase my credit score without paying off all my debt?
You can work on improving your credit while repaying debt, but you should prioritize on-time payments and reduce balances where possible.
Create a repayment plan that fits your budget and avoid taking on unaffordable additional debt.
10. Is a credit repair company necessary to increase my credit score?
You can take many credit improvement steps yourself, including checking reports, disputing inaccurate information, paying bills on time, and reducing balances.
Be careful with companies that demand upfront fees or guarantee specific score increases. Accurate negative information generally cannot be legally removed simply because it is unfavorable.
Final Takeaway
Learning how to increase credit score starts with understanding your credit report and focusing on the factors you can control.
The most useful long-term habits include:
- Paying bills on time.
- Keeping credit utilization manageable.
- Reviewing credit reports for errors.
- Limiting unnecessary applications.
- Managing debt responsibly.
- Maintaining consistent credit habits.
There is no guaranteed shortcut, but responsible financial behavior can help you build a stronger credit profile over time.
Why Maintain Market Is Different
Maintain Market explains personal finance topics in clear, practical language to help readers understand their options.
Our content focuses on:
- Credit-building strategies
- Financial product comparisons
- Potential fees and risks
- Official financial guidance
- Practical steps readers can evaluate
Always verify current financial terms and eligibility requirements directly with lenders and official sources before making financial decisions.
References
- CFPB – Understand Your Credit Score
- CFPB – How to Get and Keep a Good Credit Score
- CFPB – How to Rebuild Your Credit
- CFPB – Requesting Your Credit Report
- AnnualCreditReport.com
- Experian – How to Improve Your Credit Score
Editorial Review
Reviewed by: Maintain Market Editorial Team
Focus: Credit scores, credit reports, credit cards, and personal finance education
Disclaimer: This article is for educational purposes only and does not guarantee credit score increases or financial outcomes.