If you’re buying a home and don’t have a large down payment or perfect credit, understanding FHA loan requirements can help you see whether this type of mortgage may fit your situation. FHA loans are made by private lenders and insured by the Federal Housing Administration, which is part of the U.S. Department of Housing and Urban Development (HUD).
Quick Answer: What Are the FHA Loan Requirements?
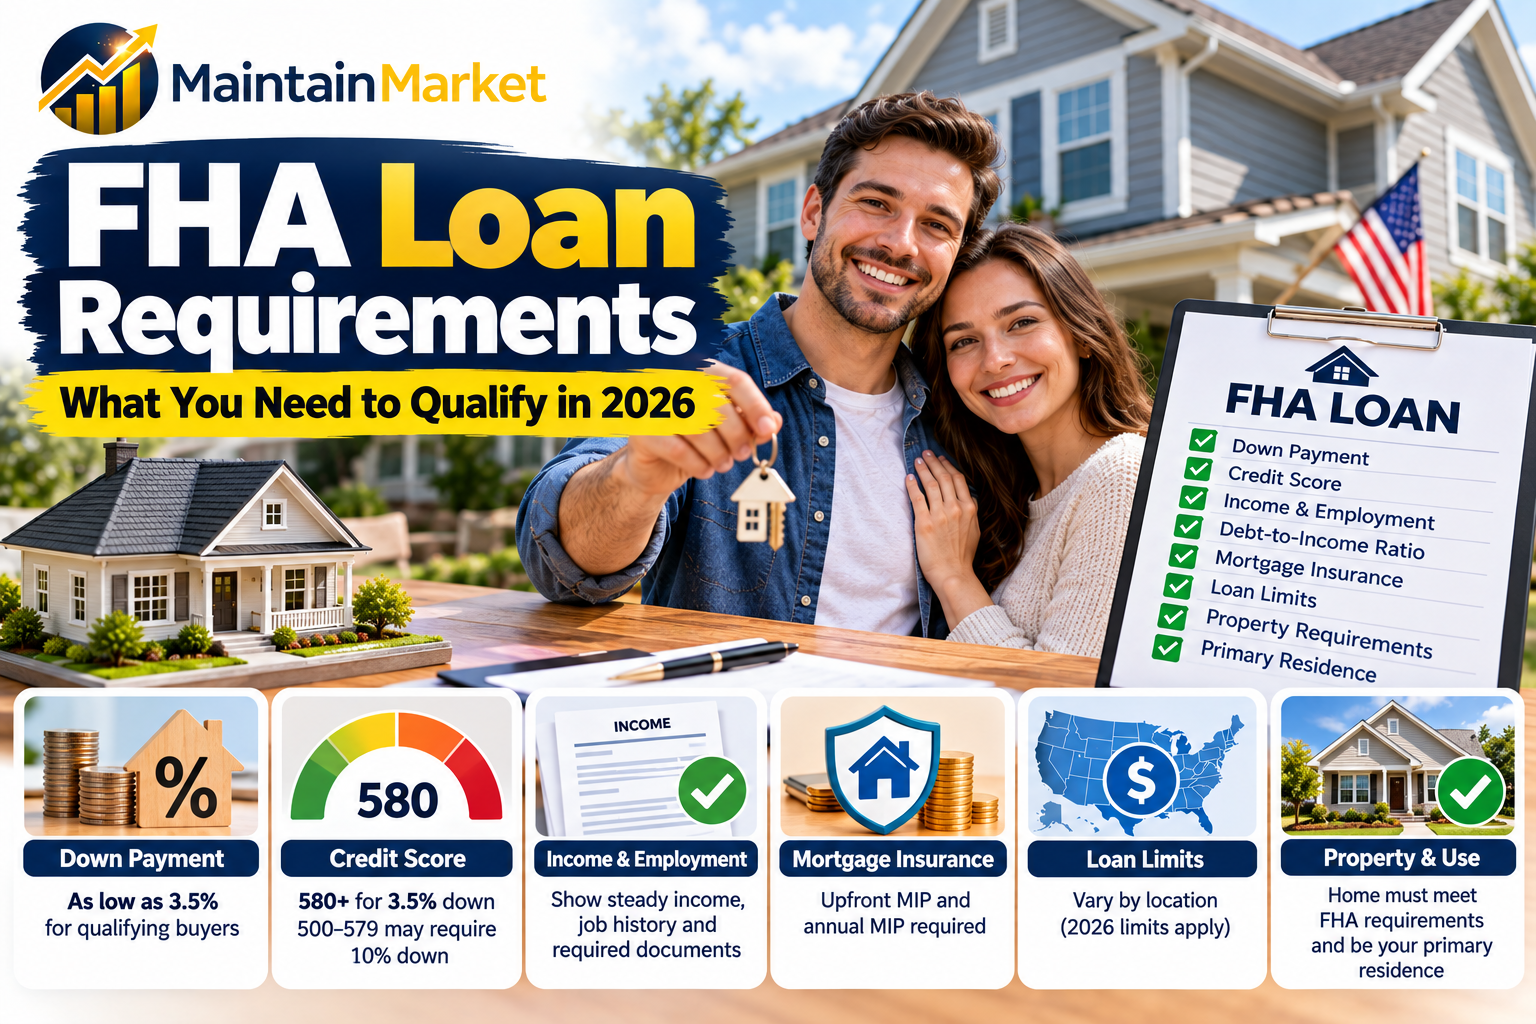
The main FHA loan requirements include:
- A minimum down payment of 3.5% for borrowers who meet the credit-score requirement for maximum FHA financing
- A credit history that meets FHA and lender underwriting requirements
- Enough income to support the monthly mortgage payment and other debts
- Proof of income, assets and employment
- A property that meets FHA requirements
- The home must generally be your principal residence
- Mortgage insurance is required
- The loan must fall within the FHA loan limit for the property and location
Your lender will review your complete financial situation. Meeting one FHA requirement does not automatically guarantee approval.
1. What Is an FHA Loan?
An FHA loan is a mortgage insured by the Federal Housing Administration.
The FHA does not usually lend you the money directly.
Instead:
You → Apply with an FHA-approved lender → Lender provides the mortgage → FHA insures the loan
This government-backed insurance can make it possible for lenders to offer FHA mortgages to borrowers who may not qualify as easily for some conventional loans.
The CFPB says FHA loans can allow down payments as low as 3.5% and generally have more flexible credit requirements than conventional loans.
2. You May Be Able to Put Down as Little as 3.5%
One of the biggest reasons people look at FHA loans is the relatively low down payment.
For borrowers who qualify for the maximum FHA financing, the minimum required investment is generally 3.5% of the property’s adjusted value.
Example
Suppose you’re buying a home for:
$300,000
A 3.5% down payment would be:
$10,500
That means the down payment could be much smaller than a traditional 20% down payment.
However, remember that your down payment isn’t your only upfront expense.
You may also have:
- Closing costs
- Prepaid taxes
- Homeowners insurance
- Inspection costs
- Appraisal costs
- Moving expenses
- Initial home repairs
The CFPB recommends considering these additional costs when planning how much cash you need to buy a home.
3. What Credit Score Do You Need for an FHA Loan?
Credit score is an important part of FHA underwriting.
The commonly used FHA minimum credit-score framework allows:
| Credit score | Typical FHA down-payment requirement |
|---|---|
| 580 or higher | 3.5% |
| 500–579 | 10% |
| Below 500 | Generally not eligible for FHA-insured financing |
These are FHA program thresholds, not a promise that a lender will approve your application.
A lender may have its own requirements, sometimes called lender overlays, that are stricter than the FHA minimums.
Also, FHA underwriting looks at more than just a credit score. Your credit history, debts, income, assets and overall application matter.
HUD’s FHA handbook provides underwriting rules for borrowers with different credit profiles, while lenders use FHA underwriting systems and requirements to evaluate the complete application.
Important 2026 update
FHA announced in 2026 that it is implementing additional credit-score models, including VantageScore 4.0 and FICO Score 10T, alongside the existing Classic FICO model. FHA said the implementation date for the new models is January 1, 2027.
So don’t assume that an online credit-score app is necessarily the exact score a mortgage lender will use.
4. You Need to Show That You Can Repay the Mortgage
FHA approval isn’t based only on your credit score.
The lender also needs to determine whether you have enough income to handle the mortgage and your other financial obligations.
The lender may review:
- Employment
- Salary or other qualifying income
- Existing debts
- Credit history
- Bank accounts
- Assets
- Monthly housing expenses
- Other financial obligations
Depending on your situation, the lender may request documents such as:
- Pay stubs
- W-2 forms
- Tax returns
- Bank statements
- Employment verification
- Statements for existing debts
- Documentation for other qualifying income
FHA’s current Handbook 4000.1 contains detailed rules for documenting employment-related income and borrower eligibility.
5. Your Debt-to-Income Ratio Matters
Your debt-to-income ratio, or DTI, compares your monthly debt payments with your gross monthly income.
Simple example
Suppose you earn:
$7,000 per month before taxes
And your monthly debt obligations total:
$2,800
Your DTI would be:
$2,800 ÷ $7,000 = 40%
FHA underwriting uses qualifying ratios, but there isn’t one simple DTI number that automatically determines whether every FHA applicant qualifies.
For manually underwritten FHA loans, HUD’s handbook contains specific qualifying-ratio rules and possible compensating factors. Automated underwriting can produce different results depending on the borrower’s overall application.
What can help your application?
Depending on the situation, factors such as:
- Stronger credit history
- Cash reserves
- Stable income
- Lower monthly debt
- A smaller increase in housing payment
may affect the underwriting decision.
So don’t assume that a specific DTI percentage automatically means “approved” or “denied.”
6. You Usually Need Mortgage Insurance With an FHA Loan
This is one of the most important FHA costs to understand.
FHA loans require mortgage insurance.
There are generally two parts:
Upfront Mortgage Insurance Premium (UFMIP)
This is charged upfront and may be financed into the mortgage rather than paid entirely out of pocket.
Annual Mortgage Insurance Premium (MIP)
This is generally collected as part of your monthly mortgage payment.
The CFPB confirms that mortgage insurance is required for FHA loans and that FHA mortgage insurance includes an upfront and monthly cost.
Why does this matter?
A low down payment can make it easier to buy a home, but mortgage insurance increases your overall borrowing cost.
That’s why it’s important to compare the total cost of the loan, not just the down payment.
7. The Home Must Meet FHA Property Requirements
FHA requirements apply to the property, not just the borrower.
The home must meet FHA’s property standards and appraisal requirements.
The appraisal is used to assess the property’s value and whether it meets applicable FHA requirements.
Potential issues can include problems involving:
- Safety
- Structural condition
- Major systems
- Property access
- Certain health or safety concerns
The exact requirements depend on the property and FHA rules.
Important 2026 development
HUD published proposed changes to FHA’s Minimum Property Requirements in September 2026.
Those changes are currently proposed, not final policy, so they should not be treated as current FHA requirements.
For current requirements, lenders and appraisers should use the applicable version of FHA Handbook 4000.1.
8. The Home Generally Needs to Be Your Primary Residence
FHA’s basic 203(b) mortgage program is designed for borrowers purchasing or refinancing a principal residence.
That means an FHA loan generally isn’t designed simply for buying an investment property that you don’t intend to occupy.
HUD’s basic FHA mortgage program describes eligibility for a person intending to use the mortgaged property as their principal residence.
What about multi-unit homes?
Certain one-to-four-unit properties can qualify under FHA rules.
For example, an eligible borrower may be able to purchase a property with multiple units if the property and borrower meet the applicable FHA requirements.
The specific occupancy and property rules matter, so don’t assume every four-unit property automatically qualifies.
9. The Loan Must Be Within the FHA Loan Limit
FHA loans aren’t unlimited.
The maximum FHA-insured mortgage amount depends on:
- Location
- Property size
- Number of units
For 2026, HUD announced the following national FHA loan-limit floor and ceiling for forward mortgages:
| Property | Low-cost area floor | High-cost area ceiling |
|---|---|---|
| 1 unit | $541,287 | $1,249,125 |
| 2 units | $693,050 | $1,599,375 |
| 3 units | $837,700 | $1,933,200 |
| 4 units | $1,041,125 | $2,402,625 |
These are the national floor and ceiling figures. Your actual FHA loan limit can fall somewhere between them depending on the county or metropolitan area.
Example
If you’re buying a home in a high-cost area, your applicable FHA limit may be significantly higher than the national floor.
Always check the FHA limit for the specific county where the property is located.
10. You Need Money for More Than the Down Payment
A common mistake first-time buyers make is saving exactly 3.5% and assuming they’re ready to close.
You’re not necessarily done.
You may need money for:
Down payment
Your required minimum investment.
Closing costs
These can include lender and settlement-related costs.
Prepaid expenses
Such as certain taxes and insurance expenses.
Home inspection
Although inspection costs vary, many buyers choose to have an independent inspection.
Moving costs
Moving can become surprisingly expensive.
Emergency savings
After buying a home, unexpected repairs can happen.
Example
If you’re buying a $300,000 home:
3.5% down payment = $10,500
But your total cash needed to purchase the home may be higher because of closing costs and other expenses.
The CFPB recommends considering these additional costs when preparing for homeownership.
FHA Loan Requirements Checklist
Before applying, use this simple checklist:
☐ Check your credit reports and scores
☐ Review your monthly debts
☐ Calculate your approximate DTI
☐ Save for the down payment
☐ Budget for closing costs
☐ Keep money available for reserves and moving costs
☐ Gather income documents
☐ Gather bank statements
☐ Check the FHA loan limit in your county
☐ Find an FHA-approved lender
☐ Compare Loan Estimates from multiple lenders
☐ Make sure the property meets FHA requirements
☐ Understand FHA mortgage insurance
☐ Confirm the home will be your primary residence
FHA Loan Requirements vs. Conventional Loan Requirements
FHA isn’t the only low-down-payment mortgage option.
Here’s a simple comparison:
| Feature | FHA loan | Conventional loan |
|---|---|---|
| Down payment | As low as 3.5% for qualifying borrowers | Some programs allow as little as 3% |
| Credit flexibility | Generally more flexible | Requirements vary |
| Mortgage insurance | FHA mortgage insurance required | PMI may apply depending on down payment |
| Loan limits | FHA county limits | Conventional conforming limits |
| Property rules | FHA property requirements apply | Different property requirements |
| Government insurance | FHA-insured | Not an FHA-insured loan |
The CFPB notes that conventional loans can sometimes cost less but may be harder to qualify for, while FHA loans can provide lower down-payment and more flexible-credit options.
The right comparison depends on your credit, down payment, income, property and total loan costs.
Can You Get an FHA Loan With Bad Credit?
Possibly.
FHA loans are known for allowing lower credit scores than many conventional mortgages.
However, bad credit does not mean automatic FHA approval.
The lender will look at your complete financial profile.
For example, it may consider:
- Recent late payments
- Collections
- Existing debts
- Credit history
- Income
- Assets
- Down payment
- Overall ability to repay
A borrower with a lower credit score may also face a higher minimum down payment under FHA rules.
That’s why it’s better to ask a lender to review your complete situation instead of relying only on a credit-score cutoff.
Can First-Time Homebuyers Get an FHA Loan?
Yes.
You do not have to be a first-time homebuyer to use an FHA loan.
FHA loans can be used by eligible borrowers who meet the program’s requirements.
However, FHA loans are popular among first-time buyers because the program can offer a relatively low down payment and flexible credit requirements.
The CFPB also notes that FHA is one of several mortgage options available to first-time homebuyers.
What Documents Do You Need for an FHA Loan?
Your lender will tell you exactly what documents are required, but you may be asked for:
Income documents
- Recent pay stubs
- W-2s
- Tax returns when applicable
- Employment verification
Asset documents
- Bank statements
- Savings account statements
- Investment account statements
Debt information
- Credit card statements
- Auto loan information
- Student loan information
- Other monthly debt obligations
Identification
- Government-issued identification
- Social Security information
- Other documents required by the lender
Self-employed borrowers or people with unusual income situations may need additional documentation.
7 Mistakes to Avoid When Applying for an FHA Loan
1. Assuming 3.5% is all the cash you need
Closing costs and other expenses can add significantly to your upfront budget.
2. Looking at only one lender
Different lenders can offer different rates, fees and underwriting requirements.
3. Assuming your credit score guarantees approval
Your complete financial profile matters.
4. Ignoring mortgage insurance
FHA mortgage insurance adds to the cost of the loan.
5. Buying a home before checking the FHA loan limit
A property may exceed the applicable FHA loan limit.
6. Making major financial changes during the mortgage process
Taking on new debt or changing your financial situation can affect underwriting.
7. Focusing only on the monthly payment
A lower monthly payment doesn’t necessarily mean a lower total loan cost.
How to Improve Your Chances of Getting an FHA Loan
There is no guaranteed formula for approval, but you can prepare before applying.
Check your credit
Look for errors and make sure your information is accurate.
Pay bills on time
Your payment history can affect your credit profile.
Reduce unnecessary debt
Lower monthly debt obligations can improve your overall financial position.
Save more than the minimum
Having additional cash can help you handle closing costs and unexpected expenses.
Avoid unnecessary new credit
Opening several new accounts before applying for a mortgage can create additional complications.
Keep your financial documents organized
Having income and asset documentation ready can make the application process smoother.
The CFPB recommends checking your credit report, understanding your finances and avoiding unnecessary new credit before applying for a mortgage.
Frequently Asked Questions
What are the basic FHA loan requirements?
The main requirements include meeting FHA credit and underwriting standards, making the required minimum investment, having qualifying income and assets, purchasing an eligible property, meeting occupancy requirements and staying within the applicable FHA loan limit. FHA mortgage insurance is also required.
What is the minimum down payment for an FHA loan?
For borrowers who meet the FHA credit requirements for maximum financing, the minimum down payment is generally 3.5%. Borrowers with lower qualifying credit scores may need a larger down payment.
Can I get an FHA loan with a 500 credit score?
FHA rules can allow borrowers with credit scores from 500 to 579 to qualify with a 10% minimum down payment, subject to the full underwriting requirements. A lender may have stricter requirements.
Is FHA mortgage insurance required?
Yes. FHA loans require mortgage insurance. This generally includes an upfront mortgage insurance premium and an annual premium paid over time.
Are FHA loans only for first-time homebuyers?
No. FHA loans aren’t limited to first-time buyers. Eligible borrowers can use FHA financing if they meet the applicable program requirements.
What is the FHA loan limit in 2026?
The 2026 FHA loan limit varies by county and property size. For one-unit properties, the national floor is $541,287 and the high-cost-area ceiling is $1,249,125.
Does FHA require a specific debt-to-income ratio?
FHA underwriting does use qualifying ratios, but there isn’t one universal DTI number that automatically approves or rejects every borrower. Manual underwriting has specific ratio rules, while automated underwriting considers the borrower’s overall profile.
Does the home have to be my primary residence?
For the standard FHA 203(b) mortgage program, the property is generally intended to be the borrower’s principal residence.
Can I use an FHA loan to buy a multi-unit property?
FHA’s basic mortgage program can cover eligible one-to-four-unit properties, subject to FHA’s occupancy, property and underwriting requirements.
Are FHA requirements the same at every lender?
Not necessarily. FHA sets program requirements, but individual lenders can apply additional requirements. That’s why comparing multiple FHA lenders can be useful.
Final Takeaway
FHA loan requirements can be easier to understand when you break them into a few main areas:
Credit + down payment + income + debt + property + occupancy + loan limit + mortgage insurance.
You don’t need perfect credit or a 20% down payment to consider an FHA mortgage.
But don’t look only at the minimum down payment.
Before choosing an FHA loan, compare the interest rate, mortgage insurance, closing costs, monthly payment and total cost with other mortgage options.
Your lender can review your individual situation and tell you which FHA requirements apply to your application.
Why Maintain Market Is Different
At Maintain Market, we explain mortgage and personal-finance topics in simple language instead of filling pages with complicated financial terms.
For FHA loans, that means breaking down:
- Credit-score requirements
- Down-payment rules
- DTI
- Mortgage insurance
- FHA loan limits
- Property requirements
- Required documents
- First-time buyer questions
- Common mistakes
Our goal is to help readers understand the numbers and rules before they speak with a lender.
Maintain Market — Clear information. Smarter financial decisions.
References
- HUD — FHA Single Family Housing Policy Handbook 4000.1
- HUD — 2026 FHA Loan Limits
- HUD — Basic Home Mortgage Loan 203(b)
- CFPB — FHA Loans
- CFPB — Mortgage Insurance
- CFPB — Preparing Your Finances for a Mortgage
Editorial Review
Reviewed for: U.S. FHA mortgage requirements, down payment, credit requirements, mortgage insurance, FHA loan limits, property eligibility and borrower considerations.
Primary sources: U.S. Department of Housing and Urban Development (HUD) and Consumer Financial Protection Bureau (CFPB).
Important: FHA requirements and lender policies can change. Borrowers should confirm current requirements with an FHA-approved lender and review the applicable HUD guidance before applying.