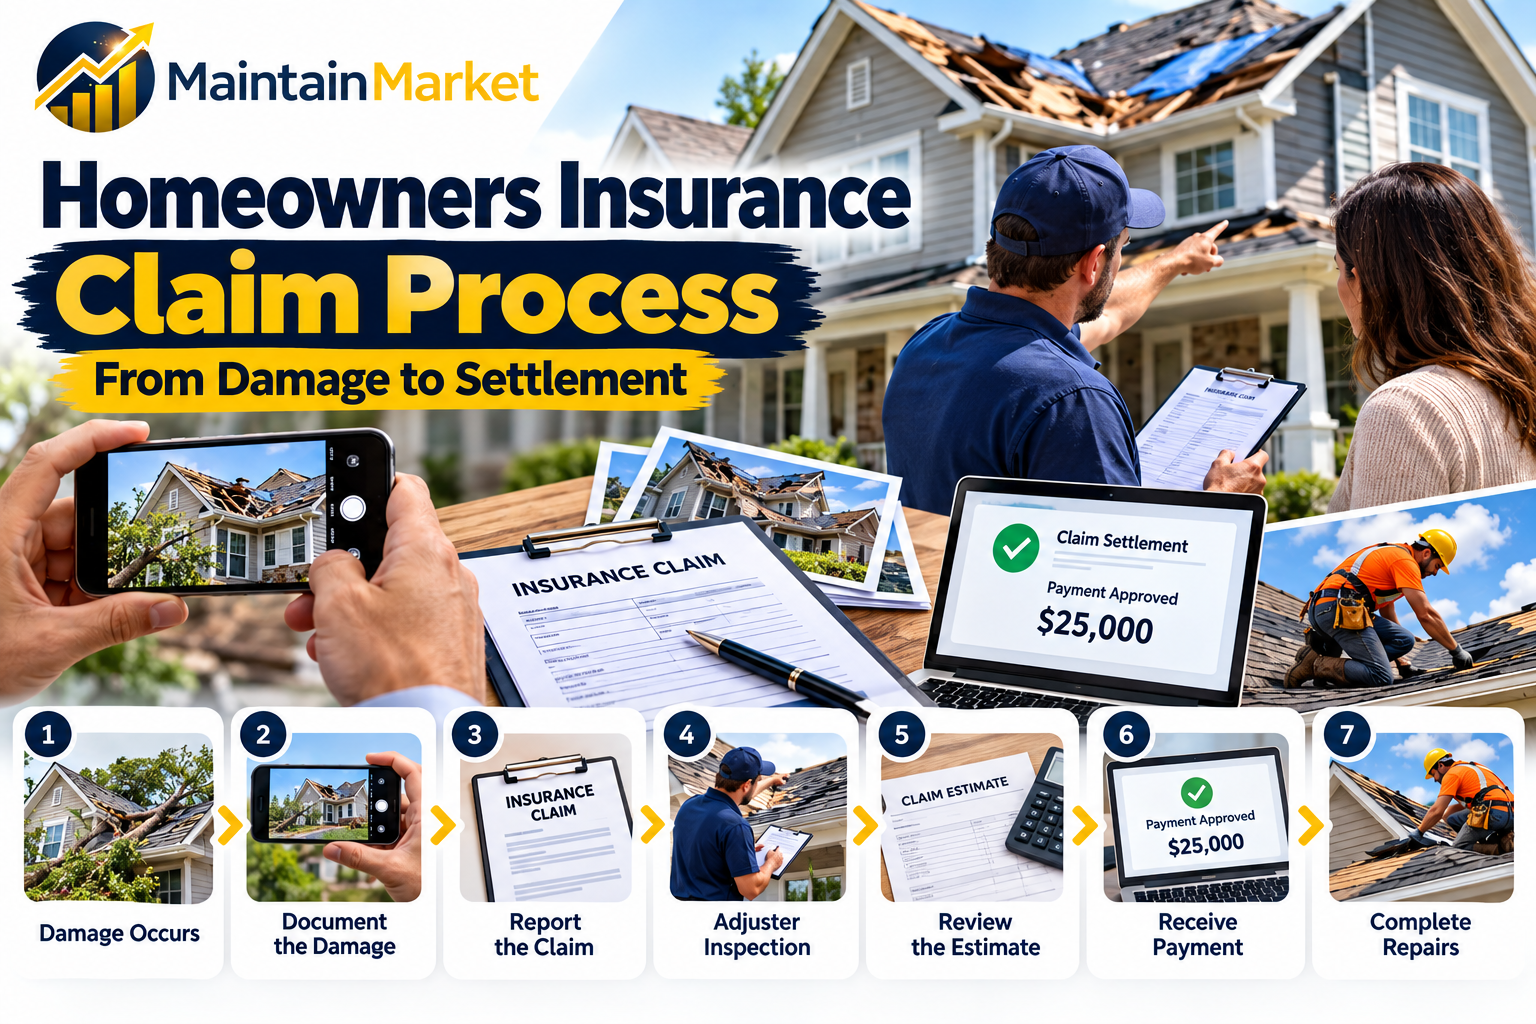
The homeowners insurance claim process starts when your home or belongings are damaged by a covered event and you contact your insurance company. From taking photos and reporting the loss to meeting the adjuster and receiving payment, each step matters. Knowing what happens next can help you avoid delays, keep better records, and understand what your insurance company is asking for.
Quick Answer: How Does the Homeowners Insurance Claim Process Work?
The homeowners insurance claim process usually follows these steps:
- Check your safety
- Prevent more damage
- Document the damage
- Check your policy and deductible
- Report the claim
- Prepare your documents
- Meet the insurance adjuster
- Review the claim estimate
- Receive the claim payment
- Complete repairs and keep records
The exact process can vary by insurance company, policy, state, and type of damage. The NAIC recommends contacting your insurer as soon as possible, taking photos and videos, making a list of damaged property, and keeping records throughout the claim.
1. Make Sure Everyone Is Safe
Before thinking about insurance, make sure you and your family are safe.
If your home has been damaged by:
- Fire
- Storm
- Flooding
- Fallen trees
- A broken pipe
- Electrical damage
- A major roof problem
there may be safety risks inside or around the property.
Do not enter an unsafe area just to take pictures.
If there is a serious danger, contact the proper emergency service first.
Your insurance claim can wait until everyone is safe.
2. Stop More Damage From Happening
After the immediate danger has passed, take reasonable steps to protect your home from additional damage.
For example:
- Cover a broken window
- Put a temporary cover over a damaged roof
- Shut off water if a pipe has burst
- Move belongings away from leaking water
- Arrange emergency water removal when needed
These are often called temporary repairs.
The goal is not to completely repair the home yourself.
It is to stop the damage from getting worse.
The NAIC advises homeowners to protect their property from further damage and keep receipts for reasonable temporary repairs.
Important
Do not make major permanent repairs before the insurance company has had a chance to inspect the damage, unless the repair is necessary for safety or to prevent further damage.
Take photos and videos first whenever it is safe to do so.
3. Take Photos and Videos of Everything
This is one of the most important parts of the homeowners insurance claim process.
Before cleaning up or throwing damaged items away, document what happened.
Take photos of:
- The outside of your home
- The damaged roof
- Walls
- Ceilings
- Floors
- Windows
- Doors
- Furniture
- Appliances
- Electronics
- Personal belongings
- Water damage
- Fallen trees
- Broken pipes
- Other damaged areas
Take both wide photos and close-up photos.
For example:
Wide photo: Shows the entire damaged room.
Close-up photo: Shows the damaged section of the wall or ceiling.
If possible, take a video while walking through the property.
The NAIC recommends taking photos and videos of damage and making a list of damaged property.
4. Check Your Insurance Policy and Deductible
Before filing a claim, look at your policy.
You want to know:
- What type of coverage you have
- What causes of damage are covered
- What exclusions apply
- Your deductible
- Your coverage limits
- Whether additional coverage applies
- Whether you have loss-of-use coverage
Your deductible is the amount you are generally responsible for before the insurer pays its share of a covered loss.
Simple example
Suppose:
Covered damage: $10,000
Deductible: $2,000
If the full $10,000 loss is covered and no other limits or adjustments apply, the deductible would generally be your responsibility and the insurer would consider the remaining covered amount.
But if the repair cost is only $1,500 and your deductible is $2,000, there may be no insurance payment.
The NAIC recommends knowing your deductible before filing a claim.
5. Report the Claim to Your Insurance Company
Once you decide to file, contact your insurance company or agent.
Your insurer may ask for:
- Policy number
- Name
- Property address
- Phone number
- Date of loss
- Time of loss, if known
- Description of what happened
- Description of the damage
- Photos or videos
- List of damaged belongings
Try to report the loss as soon as possible.
The amount of time allowed to report a claim can vary by state and policy, so do not wait unnecessarily.
Keep your claim number
After you report the claim, the insurer will usually give you a claim number.
Save it.
You may need it when talking to:
- Your insurance company
- The adjuster
- Contractors
- Your mortgage company
- Other people involved in the claim
6. Prepare Your Claim Documents
The insurance company may ask you for documents to support your claim.
The exact list depends on the type of loss.
Common documents can include:
| Document | Why It May Help |
|---|---|
| Photos | Shows the damage |
| Videos | Shows the condition of the property |
| Receipts | Helps prove ownership and value |
| Repair estimates | Shows possible repair costs |
| Home inventory | Lists damaged belongings |
| Police report | Useful for theft or vandalism |
| Contractor report | Helps explain repair needs |
| Previous repair records | Shows the home’s earlier condition |
| Temporary repair receipts | Documents emergency costs |
| Insurance policy | Shows coverage and limits |
If you do not have every document, do not panic.
Give the insurer what you have and ask what else is needed.
The NAIC recommends keeping receipts, repair records, and a home inventory to make the claims process easier.
7. Meet the Insurance Adjuster
After you report the claim, the insurance company may send a claims adjuster to inspect the damage.
The adjuster may:
- Walk around the property
- Look at damaged rooms
- Inspect the roof
- Check walls and ceilings
- Review damaged belongings
- Look at temporary repairs
- Take photos
- Ask questions about what happened
- Review your documents
The adjuster then prepares information for the insurance company to help determine the claim payment.
What should you do during the inspection?
Be honest and provide the information you have.
Show the adjuster:
- Damage you found
- Photos you took
- Repair records
- Receipts
- Damaged belongings
- Contractor estimates
You do not need to know every insurance term.
If you do not understand something, ask.
8. Understand the Different Types of Adjusters
You may hear several different terms during a claim.
Company Adjuster
This adjuster works for the insurance company.
The insurance company pays the adjuster’s cost.
Independent Adjuster
An independent adjuster is not a direct employee of your insurance company but may be hired by the insurer to handle claims.
The insurance company pays this adjuster.
Public Adjuster
A public adjuster works for the homeowner.
They can help review the damage, prepare the claim, and negotiate with the insurance company.
However, you pay the public adjuster’s fee.
Rules for public adjusters vary by state, and some states have licensing rules.
You do not automatically need a public adjuster for every claim.
For a small and simple claim, many homeowners handle the process directly with their insurer.
For a large or difficult claim, some homeowners choose professional help.
9. Review the Damage Estimate
After the inspection, the insurance company will work out the amount it believes is covered.
The adjuster may consider:
- Cost of repairs
- Damaged belongings
- Your deductible
- Policy limits
- Type of coverage
- Depreciation, where applicable
- Other policy terms
The insurer may provide an estimate or settlement information.
Read it carefully.
Do not simply look at the final dollar amount.
Check:
- What damage was included?
- What damage was excluded?
- What repairs were included?
- Was your deductible taken out?
- Were any items given a lower value?
- Are there policy limits?
- Is more documentation needed?
The NAIC recommends asking for an itemized explanation when you have questions about a settlement.
10. Receive Your Insurance Payment
A homeowners insurance claim does not always result in one single payment.
Depending on the claim, you may receive different payments for different parts of the loss.
These can include:
- Emergency expenses
- Additional living expenses
- Personal belongings
- Structural repairs
- Other covered losses
The NAIC explains that major claims may involve several payments rather than one single check.
What if you have a mortgage?
If you have a mortgage, your lender may also be listed on a payment for major structural repairs.
This happens because the lender has a financial interest in the home.
You may need to work with the mortgage company before the repair money can be fully used.
What Is Additional Living Expense Coverage?
If covered damage makes your home unsafe or unlivable, your policy may provide Additional Living Expense (ALE) coverage.
This can help with certain extra costs while your home is being repaired.
For example, you may temporarily need:
- Hotel accommodation
- Temporary housing
- Extra food costs
- Storage
The exact expenses covered depend on your policy.
Keep receipts for these expenses.
Do not assume every expense will automatically be paid.
The NAIC identifies Additional Living Expenses as one type of payment that can be part of a homeowners claim.
How Long Does the Homeowners Insurance Claim Process Take?
There is no single timeline for every homeowners insurance claim.
A small claim may move fairly quickly.
A large claim involving serious structural damage can take much longer.
The timeline can depend on:
- Type of damage
- Size of the claim
- How quickly you report it
- How much documentation is available
- Availability of an adjuster
- Contractor estimates
- Whether the cause of damage is disputed
- Whether additional inspections are needed
- State rules
- Whether the claim is disputed
A simple water-damage claim may be easier to review than a major fire or storm claim involving the entire home.
The NAIC notes that major repairs or rebuilding can take a long time, particularly after major disasters.
Homeowners Insurance Claim Process Timeline
Here is a simple example of how the process may look.
| Stage | What Happens |
|---|---|
| Day 1 | Damage occurs |
| Day 1–2 | Take photos and protect the property |
| Day 1–Several days | Report the claim |
| Next step | Insurer assigns claim/adjuster |
| Inspection | Adjuster reviews the damage |
| After inspection | Estimate is prepared |
| Review | Insurer decides covered amount |
| Payment | Claim payment is issued |
| Repairs | Home repairs begin or continue |
| Final review | Additional payment may be considered if allowed |
This is only an example.
Actual timing can vary greatly by insurer, state, claim type, and the amount of damage.
What Happens If the Insurance Company Needs More Information?
Sometimes the insurer cannot finish reviewing a claim immediately.
It may ask for:
- More photos
- Receipts
- Contractor estimates
- Proof of ownership
- Repair records
- Additional inspection
- A statement about what happened
Do not ignore these requests.
If you do not understand what the insurer wants, ask:
“Can you please explain exactly what document or information you need from me?”
Then keep a copy of what you send.
What If You Disagree With the Insurance Adjuster’s Estimate?
You do not have to stay silent if you believe the estimate does not reflect the covered damage.
First, ask the insurer to explain the estimate.
You can then provide:
- Contractor estimates
- Photos
- Repair reports
- Receipts
- Other evidence
The NAIC recommends trying to resolve disagreements with your insurer first. You can also ask your contractor to meet with the adjuster when appropriate.
Example
Your contractor estimates:
$25,000
The insurance company’s estimate says:
$17,000
Instead of simply saying “I want $25,000,” ask for an item-by-item comparison.
You can ask:
- Which repairs are missing?
- Why was this repair not included?
- What price was used?
- Is there another reason the amount is different?
That creates a much clearer discussion.
What If Your Homeowners Insurance Claim Is Denied?
A denied claim is a different situation from simply disagreeing about the amount.
If the insurer denies the claim, ask for the reason in writing.
Then review:
- The denial letter
- Your policy
- The coverage section
- Exclusions
- Supporting evidence
If you still disagree, you can ask the insurer to review the claim again.
If the issue cannot be resolved, you can contact your state’s insurance department.
The NAIC says state insurance departments can help with issues such as claim delays, denials, and disputes with insurers.
What If the Claim Payment Is Lower Than Expected?
This can happen for several reasons.
For example:
- Your deductible was applied
- Some damage was excluded
- A policy limit applies
- Depreciation was applied
- Some items were not considered covered
- The insurer’s repair estimate is lower than your contractor’s estimate
Ask the insurer for an itemized explanation.
Do not guess why the payment is lower.
The NAIC recommends asking questions and requesting an explanation of the claim settlement when you do not understand the payment.
Actual Cash Value vs. Replacement Cost
This is another important part of the claim process.
Actual Cash Value
This generally takes depreciation into account.
For example, an older roof or older piece of furniture may be worth less than the cost of buying a new replacement.
Replacement Cost
Replacement cost coverage can provide money based on the cost to repair or replace covered property with similar property, subject to the policy terms and limits.
The exact way your claim is paid depends on your policy.
Look at the property coverage section before assuming the insurer will pay the full cost of buying new items.
Do You Need a Contractor Before Filing a Claim?
Not always.
You can generally report the loss to your insurer before you have a contractor.
In fact, it can be useful to report the claim first so you understand the insurer’s process.
You can then obtain repair estimates when appropriate.
The NAIC recommends being careful when choosing contractors after a disaster and not allowing anyone to pressure you into signing a repair agreement quickly.
Good practice
Get more than one estimate for a major repair when practical.
Check the contractor’s:
- Experience
- References
- License requirements
- Insurance
- Written estimate
- Payment terms
Do not feel pressured to sign something immediately after a disaster.
Watch Out for Home Repair Scams
After a major storm, fire, or other disaster, contractors may approach homeowners quickly.
Some may offer to:
- Handle your entire insurance claim
- Start repairs immediately
- “Guarantee” your insurance payment
- Ask for a large payment upfront
- Ask you to sign documents you do not understand
Be careful.
The NAIC warns homeowners about repair fraud and advises against being pressured into quickly signing contracts or paying upfront without understanding the agreement.
Before hiring someone
Ask for:
- Written estimate
- References
- Proof of insurance
- Required license information
- Payment terms
- Scope of work
Take your time.
Keep a Claim File
One of the easiest ways to stay organized is to create one folder for the entire claim.
Keep:
Insurance documents
- Policy
- Declarations page
- Claim number
- Coverage documents
Damage records
- Photos
- Videos
- Inventory
- Receipts
Claim records
- Adjuster reports
- Estimates
- Settlement letters
- Payment records
Communication
- Emails
- Letters
- Phone call notes
Repair records
- Contractor estimates
- Invoices
- Temporary repair receipts
The NAIC recommends keeping records of communications and claim documents throughout the process.
Keep Notes of Every Call
This is a small habit that can be very useful.
Whenever you speak with your insurer, write down:
Date: September 24, 2026
Time: 2:00 PM
Person: Claims representative
Claim number: XXXXX
What was discussed: Roof inspection scheduled
Next step: Adjuster will visit on Friday
You can do this in a notebook, spreadsheet, or simple document.
Keep copies of emails and letters too.
What Should You Never Do During a Homeowners Insurance Claim?
Avoid these common mistakes.
1. Waiting too long to report the claim
Policies and state rules can have reporting deadlines.
2. Throwing away damaged property too quickly
The insurer may want to inspect it.
3. Making major repairs before documenting the damage
Take photos and videos first when possible.
4. Accepting an estimate you do not understand
Ask questions before agreeing.
5. Signing documents without reading them
Especially documents related to repairs or assignment of insurance benefits.
6. Giving false information
Always provide accurate information.
7. Keeping no records
Save emails, letters, receipts, photos, and notes.
Homeowners Insurance Claim Process Example
Imagine a homeowner named Mike has a major storm at his home.
The next morning, Mike sees:
- Roof damage
- Water inside the bedroom
- A broken window
- Damaged furniture
Here is how his claim could move forward.
Step 1: Safety
Mike makes sure his family is safe.
Step 2: Temporary protection
He places a temporary cover over the broken window.
Step 3: Documentation
He takes photos and videos of the roof, window, bedroom, and furniture.
Step 4: Policy review
He checks his deductible and coverage.
Step 5: Claim report
He contacts his insurer and receives a claim number.
Step 6: Adjuster inspection
An adjuster visits the home and reviews the damage.
Step 7: Estimate
The insurer prepares a claim estimate.
Step 8: Review
Mike checks the estimate and asks questions about anything missing.
Step 9: Payment
The insurer issues payment for covered damage according to the policy.
Step 10: Repairs
Mike works with a contractor to complete the repairs.
This is an illustrative example, not a real insurance claim. Actual claims can follow a different timeline.
What Happens to Your Belongings During a Claim?
If personal property is damaged or destroyed, the insurer may ask you to create a list.
Include:
- Item name
- Brand
- Model
- Purchase date
- Approximate price
- Current condition
- Photos
- Receipt, if available
- Serial number, if available
For example:
| Item | Purchase Price | Proof |
|---|---|---|
| Laptop | $1,400 | Receipt |
| Television | $900 | Photo + receipt |
| Sofa | $1,200 | Photo |
| Camera | $1,600 | Receipt + serial number |
You may not have receipts for everything.
If that happens, use photos, bank records, emails, warranties, or other information that can help show what you owned.
The NAIC recommends creating and keeping a home inventory for this reason.
Can You Live Somewhere Else During the Claim?
If covered damage makes your home unsafe to live in, your policy may include loss of use or Additional Living Expense coverage.
This can help with certain extra living costs while repairs are being made.
Examples can include:
- Temporary housing
- Hotel
- Storage
- Certain additional food costs
The exact coverage depends on your policy.
Ask the insurer:
“Does my policy provide Additional Living Expense coverage for this loss?”
If the answer is yes, ask what expenses are covered and keep your receipts.
What If You Have a Mortgage?
Your mortgage company can become part of the claim process when the damage is serious.
This is because the lender has a financial interest in the property.
For major structural repairs, the insurance payment may include both you and your mortgage lender.
The lender may then hold the funds or release money as repairs are completed, depending on the loan and lender’s process.
If this happens, ask your mortgage company:
- What documents are required?
- How will the payment be handled?
- When can repair funds be released?
- Does the lender need contractor information?
Can You Choose Your Own Contractor?
In many situations, homeowners can choose their own contractor, but the details can vary by policy, insurer, and state.
Your insurer may have a network of contractors it works with.
You do not have to assume that the first contractor who contacts you is the right choice.
Compare estimates and check the contractor carefully.
The NAIC recommends getting more than one bid when possible and avoiding pressure from contractors after disasters.
What If You and the Insurer Cannot Agree?
Start by trying to resolve the issue directly with your insurance company.
Ask for:
- Written explanation
- Itemized estimate
- Policy section involved
- Reason for any excluded damage
- Explanation of the payment
If the disagreement continues, check your policy for an appraisal clause when the dispute is about the value of the loss.
You may also consider a public adjuster or attorney for a large or difficult dispute.
Your state’s insurance department may also be able to help with certain complaints.
When Should You Contact Your State Insurance Department?
You may contact your state insurance department if you cannot resolve a problem with your insurer.
For example:
- Your claim is taking too long
- You believe the insurer is not following the policy
- You disagree with a denial
- You have problems getting a response
- You believe the claim was not handled properly
The NAIC says state insurance departments can investigate complaints involving unfair claim delays or denials, failure to honor a policy, and other insurance problems.
Try to resolve the problem with your insurer first and keep your records ready.
Homeowners Insurance Claim Process Checklist
Save this checklist for future reference:
☐ Make sure everyone is safe
☐ Stop further damage when possible
☐ Take photos
☐ Take videos
☐ Make a list of damaged items
☐ Check your deductible
☐ Review your policy
☐ Report the claim quickly
☐ Save your claim number
☐ Prepare receipts and records
☐ Meet the adjuster
☐ Review the damage estimate
☐ Ask questions about missing items
☐ Keep all claim documents
☐ Keep repair receipts
☐ Review the settlement
☐ Contact your insurer if you disagree
☐ Contact your state insurance department if needed
Frequently Asked Questions
What is the homeowners insurance claim process?
The homeowners insurance claim process usually involves reporting the loss, documenting the damage, having the insurer inspect the property, reviewing the claim, calculating the covered amount, and issuing payment. The exact process can vary by policy, insurer, state, and type of damage.
How soon should I file a homeowners insurance claim?
You should generally contact your insurance company as soon as reasonably possible after a loss. Policies and state rules can have different reporting deadlines, so waiting can create problems.
What does an insurance adjuster do?
An insurance adjuster reviews the damage, looks at the property and belongings, gathers information, and prepares an estimate for the insurer. The insurer then uses that information when deciding the covered claim amount.
Do I need a contractor before filing a homeowners insurance claim?
Usually, you can report the claim before choosing a contractor. Your insurer may then explain its process and what estimates or repairs are needed. For major repairs, getting more than one estimate can be useful.
How long does a homeowners insurance claim take?
There is no single timeline. Small claims can move faster, while large claims involving major damage, multiple inspections, or rebuilding can take much longer. State rules and the type of loss can also affect the timeline.
Does filing a homeowners insurance claim increase your insurance rate?
It can affect your future insurance costs or renewal depending on the insurer, type of claim, your claims history, and state rules. Ask your insurer how a particular claim could affect your policy before making a decision when the damage is small.
What happens after the insurance adjuster visits?
The adjuster reviews the damage and prepares information for the insurer. The insurer then uses the policy, deductible, limits, and damage information to determine the covered amount and settlement.
Can I disagree with an insurance claim estimate?
Yes. If you believe the estimate is missing covered damage or the amount is incorrect, ask the insurer for an explanation and provide supporting documents such as contractor estimates, photos, and repair records.
What if my homeowners insurance claim is denied?
Ask for the denial in writing and find out which part of the policy the insurer relied on. If you disagree, you can ask the insurer to review the claim again and, if necessary, contact your state insurance department.
What is a public adjuster?
A public adjuster is a professional hired by the homeowner to help with a property insurance claim. They can review damage, prepare claim information, and negotiate with the insurer. The homeowner pays the public adjuster’s fee, and rules vary by state.
What documents do I need for a homeowners insurance claim?
Common documents include photos, videos, a list of damaged belongings, receipts, repair estimates, police reports when relevant, and temporary repair receipts. Your insurer may ask for additional documents depending on the claim.
Final Takeaway
The homeowners insurance claim process may look complicated, but it becomes easier when you break it into simple steps.
Document the damage → report the claim → meet the adjuster → review the estimate → understand the payment → complete repairs.
The most important things you can do are:
- Take plenty of photos and videos.
- Report the loss promptly.
- Keep receipts and records.
- Understand your deductible.
- Read the claim estimate carefully.
- Ask questions when something does not make sense.
- Keep copies of all communication.
And remember, your insurance policy is the main document that tells you what is covered, what is excluded, and what your responsibilities are.
If a claim becomes difficult or you disagree with the insurer, you can ask for a review and contact your state insurance department for help.
Why Maintain Market Is Different
At Maintain Market, we explain insurance topics using simple, everyday language.
The goal is not just to tell you that you can file a claim. We explain what happens before, during, and after the claim so you know what to expect.
We focus on practical questions such as:
- What should I do first?
- What documents should I keep?
- What does the adjuster do?
- How is the payment calculated?
- What happens if I disagree?
- When should I contact my state insurance department?
Insurance policies differ by company and state, so this article is general information for U.S. homeowners. Always check your own policy for the exact rules that apply to your claim.
References
- NAIC — What You Need to Know When Filing a Homeowners Claim
- NAIC — What You Should Know About Settling a Homeowners Insurance Claim
- NAIC — A Consumer’s Guide to Home Insurance
- NAIC — Homeowners Insurance
- NAIC — Home Inventory
- NAIC — How to File a Complaint
- NAIC — How Do I File a Complaint Against My Insurance Company?
Editorial Review
This article is for general educational purposes for homeowners in the United States. Claim procedures, deadlines, coverage, deductibles, settlement rules, and complaint processes can vary by insurer, policy, and state. Readers should review their own policy and contact their insurance company or state insurance department for help with a specific claim.