If you own a home and have built up equity, you may be able to borrow against that value to access cash for home improvements, debt consolidation, education expenses, or other financial needs. Two common options are a cash-out refinance and a home equity loan. Understanding cash out refinance vs home equity loan can help you choose an option that fits your financial situation.
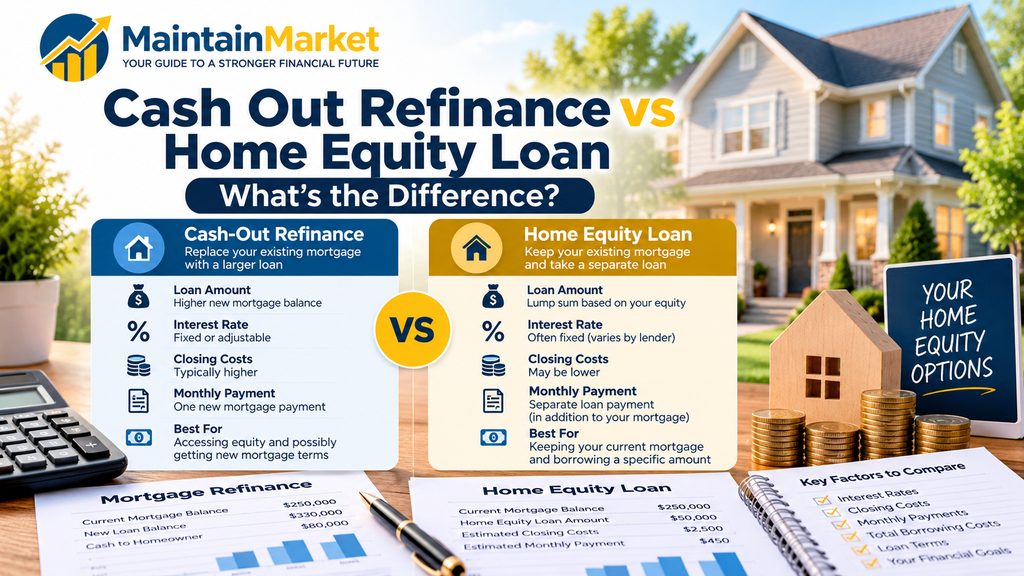
A cash-out refinance replaces your existing mortgage with a new, larger mortgage and gives you the difference in cash after paying off the old loan and applicable costs. A home equity loan is a separate loan secured by your property, allowing you to borrow a lump sum while keeping your existing mortgage.
Neither option is automatically better. Your current mortgage rate, borrowing needs, available equity, loan fees, repayment plans, and financial goals all matter.
Cash Out Refinance vs Home Equity Loan: What’s the Difference?
The biggest difference is what happens to your existing mortgage.
- Cash-out refinance: You replace your current mortgage with a new mortgage for a larger amount. The new loan pays off the existing mortgage, and you receive the remaining proceeds after applicable costs.
- Home equity loan: You keep your current mortgage and take out another loan secured by your home. You receive the borrowed amount as a lump sum and repay it separately.
A cash-out refinance usually results in one new mortgage payment. A home equity loan generally means you will have two loan payments: your original mortgage and the home equity loan.
Quick comparison
| Feature | Cash-Out Refinance | Home Equity Loan |
|---|---|---|
| Existing mortgage | Replaced | Kept |
| Loan structure | New primary mortgage | Usually a second mortgage |
| Money received | Lump sum | Lump sum |
| Interest rate | Fixed or adjustable, depending on product | Often fixed |
| Monthly payments | Usually one new mortgage payment | Usually two separate payments |
| Closing costs | Often higher because it is a new mortgage | May be lower, depending on lender |
| Repayment term | New mortgage term | Separate loan term |
| Best suited for | Borrowers who also want to change mortgage terms | Borrowers who want to preserve their existing mortgage |
The exact terms, fees, and eligibility requirements vary by lender and loan program.
What Is a Cash-Out Refinance?
A cash-out refinance is a mortgage refinancing option that allows homeowners to access some of the equity in their property.
Instead of keeping your existing mortgage, you replace it with a new mortgage that has a higher loan balance. The new mortgage pays off your previous loan, and you receive the remaining eligible proceeds in cash after applicable closing costs and other deductions.
Example of a cash-out refinance
Imagine the following situation:
- Current home value: $450,000
- Existing mortgage balance: $250,000
- New cash-out refinance mortgage: $330,000
The new mortgage pays off the existing $250,000 balance.
The remaining $80,000 is the difference before closing costs, prepaid items, and other applicable deductions.
You could receive less than $80,000 after those deductions.
This is a simplified example, not a loan approval or an indication of how much a lender will allow you to borrow.
Advantages of a cash-out refinance
- One new mortgage payment: You replace your existing mortgage rather than maintaining a separate home equity loan.
- Access to a lump sum: You can receive cash for eligible financial needs.
- Potentially better mortgage terms: If market conditions and your qualifications allow, you may obtain a different interest rate or loan term.
- Possible debt consolidation: You may use the proceeds to pay off higher-interest debts, although this converts unsecured debt into debt secured by your home.
- Flexible use of proceeds: Depending on loan terms, proceeds can generally be used for a range of purposes.
Disadvantages of a cash-out refinance
- You replace your entire mortgage: Your existing interest rate and repayment schedule will no longer apply.
- Closing costs: Refinancing can involve appraisal, title, origination, and other costs.
- Potentially higher interest expenses: A new loan may carry a higher rate or extend your repayment period.
- Reduced home equity: Borrowing against your equity increases the amount secured by your home.
- Foreclosure risk: If you cannot make the new mortgage payments, you could lose your home.
A cash-out refinance deserves particular attention if your current mortgage has a much lower interest rate than the rate available today.
What Is a Home Equity Loan?
A home equity loan allows you to borrow against the equity you have built in your property.
Unlike a cash-out refinance, a home equity loan does not replace your existing mortgage. It is generally a second mortgage with its own interest rate, loan balance, monthly payment, and repayment schedule.
Most home equity loans provide the borrowed amount as a lump sum. Many have fixed interest rates, although product terms can vary by lender.
Example of a home equity loan
Suppose:
- Current home value: $450,000
- Existing mortgage balance: $250,000
- Home equity loan: $50,000
You receive $50,000 as a lump sum, subject to the lender’s approval and applicable costs.
Your original mortgage remains in place. You now have two separate obligations:
- Your existing mortgage payment
- Your new home equity loan payment
The lender will evaluate your credit, income, debt obligations, property value, and existing mortgage balance before deciding how much you can borrow.
Advantages of a home equity loan
- Keep your existing mortgage: You do not have to replace your current mortgage or give up its interest rate.
- Predictable payments: Many home equity loans have fixed interest rates and fixed monthly payments.
- Lump-sum funding: You receive the approved loan amount upfront.
- Separate repayment schedule: You can repay the home equity loan independently of your first mortgage.
- Useful for planned expenses: It may suit borrowers who know exactly how much money they need for a renovation or another large expense.
Disadvantages of a home equity loan
- Two loan payments: You must continue paying your original mortgage and the new home equity loan.
- Additional borrowing costs: The loan may include appraisal, origination, title, or other fees.
- Potentially higher interest rate: Because the home equity loan is generally a second lien, its interest rate may be higher than a first mortgage.
- Foreclosure risk: Your home serves as collateral, so missed payments can put your property at risk.
- Less available equity: Borrowing reduces the equity you retain in your home.
Cash-Out Refinance vs Home Equity Loan: Which Has a Lower Interest Rate?
There is no universal answer.
Cash-out refinance interest rates may be lower than home equity loan rates because a cash-out refinance replaces the first mortgage, while a home equity loan generally sits behind the existing first mortgage.
However, the rate alone does not tell you which option is cheaper.
For example, consider two hypothetical situations:
- Your existing mortgage has a 4.00% interest rate.
- A new cash-out refinance is offered at 6.75%.
- A separate home equity loan is offered at 8.00%.
These are illustrative rates, not current market quotes.
Although the cash-out refinance rate is lower than the home equity loan rate, it applies to the entire new mortgage balance—not just the additional cash you want to borrow.
If you replace a low-rate $250,000 mortgage with a larger mortgage at 6.75%, the cost of refinancing your existing balance could outweigh the benefit of the lower rate on the additional borrowing.
A home equity loan may allow you to keep the existing 4.00% mortgage and pay the higher rate only on the separate amount borrowed.
Always compare the total cost of both options rather than comparing interest rates in isolation.
Cash-Out Refinance vs Home Equity Loan: Closing Costs
Closing costs can make a significant difference when comparing these borrowing options.
A cash-out refinance involves replacing your existing mortgage, so it may include costs associated with a new mortgage transaction, such as:
- Loan origination charges
- Appraisal fees
- Title search and title insurance
- Credit report fees
- Recording fees
- Discount points, if applicable
- Prepaid taxes and insurance
A home equity loan may involve some of these costs too, but the total can be different depending on the lender, property, and loan structure.
Before signing an agreement, request a written breakdown of all fees.
Do not assume a loan with no upfront closing costs is free. Some lenders may recover costs through a higher interest rate or other loan terms.
Which Option Is Better for Debt Consolidation?
Both options can be used to consolidate eligible debts, but they involve important financial risks.
For example, suppose you have:
- Credit card debt: $20,000
- Personal loan debt: $10,000
- Total non-mortgage debt: $30,000
You might consider borrowing $30,000 through a cash-out refinance or a home equity loan to pay off these balances.
However, converting unsecured debt into debt secured by your home changes the consequences of not repaying it.
Credit card debt is generally not secured by your home. A home equity loan or cash-out refinance is secured by your property. If you cannot make the required payments, you could face foreclosure.
Also compare the total interest you would pay over the repayment period. A lower monthly payment does not necessarily mean a lower overall cost, especially if you spread the debt over many years.
Consider speaking with a qualified nonprofit credit counselor before using home equity to consolidate debt.
When Should You Choose a Cash-Out Refinance?
A cash-out refinance may be worth considering when:
- You want to replace your existing mortgage with different terms.
- The new mortgage rate is competitive compared with your current rate.
- You need a substantial lump sum.
- You prefer one new mortgage payment instead of maintaining two separate loans.
- You have compared the refinancing costs with the potential long-term benefits.
It may be less attractive if your existing mortgage has a significantly lower interest rate than the new rate available to you.
When Should You Choose a Home Equity Loan?
A home equity loan may be worth considering when:
- You want to keep your current mortgage.
- You have a favorable interest rate on your existing mortgage.
- You know exactly how much money you need.
- You prefer a lump sum rather than a revolving credit line.
- You want a separate repayment schedule.
- You can comfortably manage two loan payments.
For homeowners with a low existing mortgage rate, preserving that mortgage can be an important financial advantage.
Cash-Out Refinance vs Home Equity Loan vs HELOC
A Home Equity Line of Credit (HELOC) is another way to borrow against home equity, but it works differently from both options.
| Feature | Cash-Out Refinance | Home Equity Loan | HELOC |
|---|---|---|---|
| Existing mortgage | Replaced | Kept | Kept |
| Money received | Lump sum | Lump sum | Draw as needed |
| Interest rate | Fixed or adjustable | Often fixed | Often variable |
| Repayment | New mortgage schedule | Separate loan schedule | Draw period followed by repayment |
| Best suited for | Replacing mortgage and accessing equity | One-time borrowing | Ongoing or uncertain expenses |
A HELOC works like a revolving credit line. You can borrow from the available credit during the draw period, repay the amount, and potentially borrow again, subject to the agreement.
A home equity loan is generally more suitable when you need a specific amount upfront. A HELOC may be useful when expenses occur over time, such as a renovation with several stages.
Learn more about the difference between a home equity loan and a HELOC.
How to Compare Cash-Out Refinance and Home Equity Loan Offers
Before choosing either option, compare the following:
1. Check your available home equity
Calculate your approximate home equity:
Home Equity = Current Home Value − Outstanding Mortgage Balance
For example:
- Home value: $450,000
- Mortgage balance: $250,000
- Approximate home equity: $200,000
This is your estimated equity, not the amount you can automatically borrow. Lenders consider loan-to-value limits, credit, income, existing liens, and other requirements.
2. Compare interest rates
Get written quotes for both options.
For a cash-out refinance, compare the new mortgage rate with your existing mortgage rate. For a home equity loan, compare the offered rate and repayment terms with your existing mortgage obligations.
3. Review closing costs
Request itemized estimates from each lender. Compare origination charges, appraisal costs, title fees, points, lender credits, and other applicable expenses.
4. Calculate the total monthly payment
For a cash-out refinance, calculate the payment on the new mortgage.
For a home equity loan, add the new loan payment to your existing mortgage payment.
Also account for property taxes, homeowners insurance, mortgage insurance where applicable, and other housing costs.
5. Compare the total borrowing cost
Consider the interest paid over the expected time you will keep each loan, along with upfront costs and any changes to your repayment period.
6. Check the repayment terms
Review fixed or adjustable rates, loan maturity, prepayment provisions, and any other conditions that could affect your finances.
7. Evaluate your financial stability
Borrowing against home equity increases the debt secured by your property. Make sure the new payment fits comfortably within your budget, even if your income or expenses change.
Frequently Asked Questions
1. Is a cash-out refinance better than a home equity loan?
Neither option is always better. A cash-out refinance may suit borrowers who also want to replace their existing mortgage. A home equity loan may suit homeowners who want to preserve their current mortgage and borrow a separate lump sum.
2. What is the main difference between cash-out refinance and home equity loan?
A cash-out refinance replaces your existing mortgage with a larger new mortgage. A home equity loan is generally a separate second mortgage that allows you to borrow against your home’s equity without replacing the first mortgage.
3. Which has a lower interest rate, cash-out refinance or home equity loan?
Cash-out refinance rates may be lower than home equity loan rates, but this varies by borrower and lender. A cash-out refinance applies the new rate to the entire refinanced mortgage balance, while a home equity loan generally applies its rate only to the separate amount borrowed.
4. Can I keep my current mortgage with a home equity loan?
Yes. A home equity loan generally allows you to keep your existing mortgage. You will have a separate loan balance and repayment schedule.
5. Does a cash-out refinance increase my mortgage balance?
Yes. A cash-out refinance generally creates a new mortgage balance that is larger than the amount needed to pay off your existing mortgage. The additional amount provides the cash proceeds, after applicable costs and deductions.
6. Can I use a home equity loan to pay off credit card debt?
Yes, some borrowers use home equity loans to consolidate credit card debt. However, doing so turns unsecured debt into debt secured by your home. If you cannot repay the loan, your home could be at risk.
7. Do cash-out refinances have closing costs?
Yes. Cash-out refinances typically involve closing costs because they replace an existing mortgage with a new one. The exact charges depend on the lender, loan amount, property, and transaction.
8. Is a home equity loan considered a second mortgage?
Generally, yes. If you already have a first mortgage, a home equity loan is typically a second mortgage secured by the same property.
9. Can I get a cash-out refinance if my home is paid off?
Potentially, yes. A homeowner who owns a property outright may be able to obtain a mortgage that provides cash based on the property’s value, subject to lender requirements and eligibility.
10. Is a home equity loan tax deductible?
Interest may be deductible in certain circumstances, but it is not automatically deductible. Under IRS rules, the use of the borrowed funds and other eligibility requirements matter. Consult a qualified tax professional and review the IRS guidance on home mortgage interest.
Final Thoughts
Choosing between a cash-out refinance and a home equity loan depends on your existing mortgage, borrowing needs, and long-term financial plans.
A cash-out refinance replaces your current mortgage and may be useful if you also want to change your mortgage terms. A home equity loan lets you keep your existing mortgage while borrowing a separate lump sum against your home.
Before making a decision, compare interest rates, closing costs, monthly payments, repayment periods, and total borrowing costs. Most importantly, remember that both options use your home as collateral. Borrow only what you can reasonably afford to repay.
External authoritative sources
These links within the article:
- CFPB: Alternatives to a HELOC
- CFPB: What Is a Home Equity Loan?
- CFPB: Home Equity Loan vs HELOC
- Fannie Mae: Mortgage Refinancing Options
- CFPB: Loan Estimate Explainer
Disclaimer: This article is for educational purposes only and does not constitute financial, mortgage, tax, or legal advice. Loan terms, interest rates, fees, eligibility requirements, and tax treatment vary. Consult qualified professionals before making a borrowing decision.