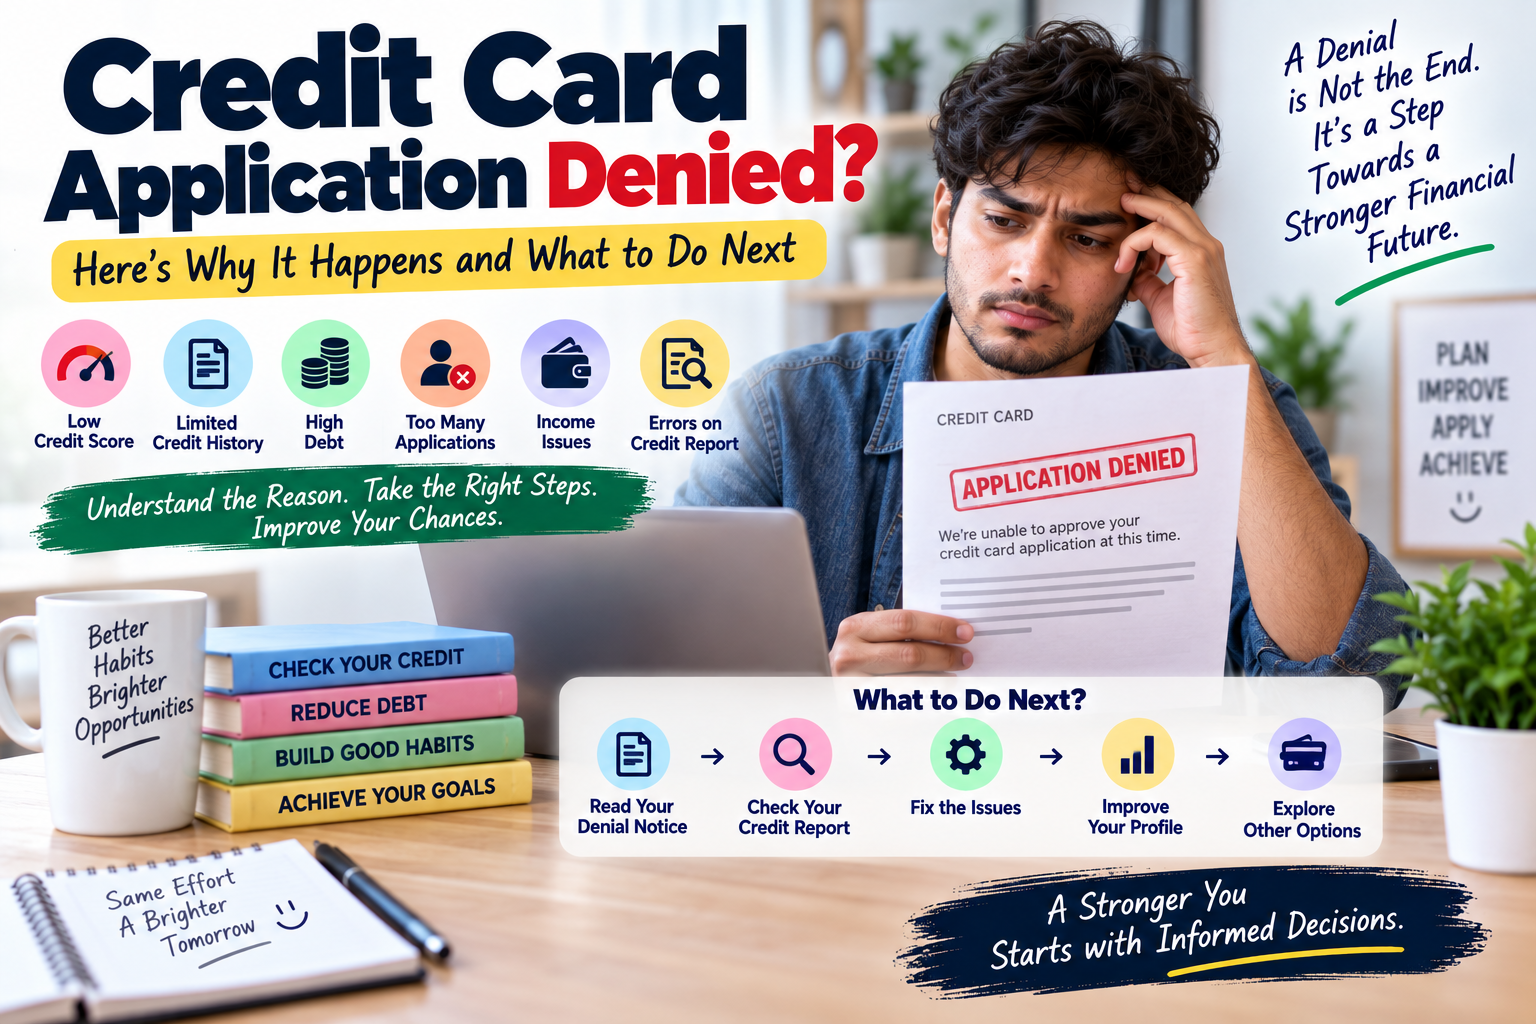
Getting a credit card application denied can be frustrating, especially when you believe your credit score and income should qualify you. However, credit card issuers consider several factors, including your credit history, income, debt levels, recent applications, and the lender’s approval criteria.
A denial does not necessarily mean you can never qualify for a credit card. Understanding the reason for rejection and taking the right steps can improve your chances of approval in the future.
In this guide, you’ll learn why credit card applications are denied, what to do after rejection, how denial affects your credit score, and how to improve your approval chances.
Quick Answer: Why Was My Credit Card Application Denied?
Your credit card application may have been denied because of:
- Low credit score
- Limited or insufficient credit history
- High credit utilization
- Too many recent credit applications
- High debt-to-income ratio
- Insufficient or unverifiable income
- Recent late payments or defaults
- Bankruptcy or other negative credit information
- Too many existing credit accounts
- Failure to meet the issuer’s internal eligibility requirements
The most important first step is to review your adverse action notice, which should explain the main reason or reasons for the denial.
10 Common Reasons Your Credit Card Application Was Denied
1. Your Credit Score Is Too Low
Credit card companies generally review your credit score to estimate how you have managed credit in the past.
A lower score may indicate:
- Missed or late payments
- High credit card balances
- Defaults or collections
- A short credit history
- Multiple recent credit inquiries
Different cards have different eligibility requirements. A denial for a premium rewards card does not necessarily mean you cannot qualify for a secured credit card or another card designed for credit building.
What you can do:
- Pay bills on time.
- Reduce outstanding credit card balances.
- Review your credit reports for errors.
- Avoid applying for several cards within a short period.
2. You Have a Limited Credit History
A limited credit history can make it difficult for an issuer to evaluate your credit behavior.
This may affect:
- Students applying for their first credit card
- Young adults with little borrowing experience
- New residents with limited U.S. credit history
- Consumers who have never used a credit account
Even if you have a good income, the issuer may not have enough information to assess your repayment behavior.
Potential alternatives include:
- Student credit cards
- Secured credit cards
- Credit-builder products
- Cards designed for applicants with limited credit history
Approval is not guaranteed, and eligibility depends on the issuer’s requirements.
3. Your Credit Utilization Is Too High
Credit utilization refers to the amount of revolving credit you are using compared with your total available credit.
For example:
| Credit Limit | Balance | Utilization |
|---|---|---|
| $5,000 | $1,000 | 20% |
| $5,000 | $2,500 | 50% |
| $5,000 | $4,500 | 90% |
A high utilization ratio may negatively affect your credit score and make lenders more cautious.
How to improve it:
- Pay down existing credit card balances.
- Avoid reaching your credit limit.
- Make payments before the statement closing date when possible.
- Avoid taking on unnecessary revolving debt.
There is no universal utilization percentage that guarantees approval. Issuers use their own underwriting criteria.
4. You Applied for Too Many Credit Cards Recently
Several credit applications within a short period may raise concerns for some lenders.
Each application may result in a hard credit inquiry, depending on the issuer and application process. Multiple inquiries can also affect your credit profile.
Frequent applications may suggest that you are seeking additional credit, although the impact depends on your overall credit history and the lender’s evaluation.
What you should do:
- Stop submitting unnecessary applications.
- Check whether you received a prequalification offer.
- Review your credit report.
- Wait until you understand the reason for the previous denial before applying again.
Prequalification does not guarantee final approval.
5. Your Income Is Too Low or Cannot Be Verified
Credit card issuers may consider your income and ability to make payments when evaluating an application.
Your application may be denied if:
- Your reported income does not meet the issuer’s criteria.
- Your income information cannot be verified.
- You entered incorrect information.
- Your employment or income details are inconsistent.
- Your existing financial obligations appear high relative to your income.
Some issuers allow applicants to report qualifying income sources beyond employment income. However, you should provide accurate information and follow the issuer’s instructions.
Never exaggerate your income to improve your approval chances.
6. Your Debt-to-Income Ratio Is Too High
Your debt-to-income ratio, or DTI, compares your monthly debt payments with your gross monthly income.
For example:
- Gross monthly income: $4,000
- Monthly debt payments: $1,600
- DTI: 40%
A high DTI may indicate that a large portion of your income is already committed to debt payments.
Credit card issuers may consider your existing debts, housing costs, income, and other information when making their decisions.
Ways to improve your financial profile:
- Pay down existing debts.
- Avoid unnecessary new loans.
- Maintain stable income records.
- Review your monthly budget.
- Correct inaccurate information on your application.
DTI requirements vary by lender, and there is no single ratio that guarantees approval.
7. You Have Recent Late Payments or Defaults
Payment history is an important part of many credit scoring models.
A credit card application may be denied if your credit report shows:
- Recent late payments
- Accounts in collections
- Charge-offs
- Loan defaults
- Repeated missed payments
The age, frequency, and seriousness of negative information can affect how lenders evaluate your application.
What you can do:
- Pay all current accounts on time.
- Bring overdue accounts up to date where possible.
- Contact creditors if you are experiencing financial difficulty.
- Dispute inaccurate information with the relevant credit reporting company.
Accurate negative information generally cannot simply be removed because it is unfavorable.
8. Your Credit Report Contains Errors
A credit report may contain inaccurate or outdated information.
Examples include:
- Incorrect account balances
- Accounts that do not belong to you
- Incorrect payment history
- Duplicate accounts
- Incorrect personal information
If a lender denied your application because of your credit report, review the adverse action notice and obtain the relevant credit report.
You can dispute information you believe is inaccurate with the credit reporting company and the company that supplied the information.
Do not ignore credit report errors. Incorrect information may affect future credit applications, insurance-related decisions where permitted, and other financial evaluations.
9. You Already Have Too Many Credit Accounts
Some issuers may consider the number of credit accounts you already have, your total available credit, and your existing balances.
Your application may be denied if the issuer believes:
- You already have substantial available credit.
- Your existing balances are high.
- You have recently opened several accounts.
- Your credit profile does not fit the card’s target requirements.
Having multiple credit cards is not automatically harmful. The effect depends on how you manage them, your balances, payment history, and the issuer’s policies.
Focus on responsible account management rather than opening accounts solely to increase your total credit limit.
10. You Did Not Meet the Issuer’s Internal Approval Criteria
Every credit card issuer uses its own eligibility and underwriting standards.
Even applicants with good credit may be denied because of:
- Internal risk policies
- Existing relationships with the issuer
- Application information
- Credit history
- Income and financial obligations
- Card-specific eligibility rules
- Incomplete or inconsistent information
A good credit score does not guarantee approval for every credit card.
If the issuer provides a reason for rejection, use that information to determine your next step instead of immediately applying for another card.
What Should You Do After Your Credit Card Application Is Denied?
Follow these steps before submitting another application.
Step 1: Read Your Adverse Action Notice
An adverse action notice generally explains the main reason or reasons for the credit decision, or tells you how to request those reasons.
If the decision was based on your credit report, the notice may also provide information about:
- The credit score used
- Key factors affecting that score
- The credit reporting company involved
- Your rights to obtain and dispute credit report information
Keep this notice for your records.
Step 2: Check Your Credit Reports
Review your credit reports for errors, unfamiliar accounts, and incorrect payment information.
You can obtain free credit reports through the official federally authorized website:
AnnualCreditReport.com
Review the report associated with the credit reporting company identified in your notice, as well as other reports when appropriate.
Step 3: Identify the Main Problem
Try to determine whether your denial was related to:
- Credit score
- High utilization
- Income
- Debt
- Recent inquiries
- Credit history
- Incorrect application information
Address the relevant issue instead of making multiple applications without a plan.
Step 4: Contact the Card Issuer
You may contact the issuer’s reconsideration department if one is available.
Ask:
- Why was my application denied?
- Can you clarify the reason listed in the notice?
- Is additional documentation accepted?
- Can my application be reviewed again?
- Are there other cards for which I may qualify?
Reconsideration is not available for every issuer and does not guarantee approval.
Step 5: Avoid Immediate Repeated Applications
Applying for several cards after a denial may result in additional hard inquiries.
Instead:
- Review the denial reason.
- Check your credit reports.
- Improve the relevant financial factor.
- Compare eligibility criteria.
- Apply only when there is a reasonable basis to do so.
Does a Denied Credit Card Application Hurt Your Credit Score?
The denial itself generally does not directly reduce your credit score.
However, the application may have resulted in a hard credit inquiry, which can affect your credit profile.
The impact depends on factors such as:
- The scoring model used
- Your existing credit history
- The number of recent inquiries
- The information contained in your credit report
Checking whether you are prequalified may involve a soft inquiry, but you should confirm the process with the issuer.
Always read the application disclosures before submitting your information.
How Long Should You Wait Before Applying Again?
There is no universal waiting period that applies to every applicant.
The appropriate time depends on the reason for denial.
| Denial Reason | Potential Next Step |
|---|---|
| High credit utilization | Reduce outstanding balances |
| Credit report error | Investigate and dispute inaccurate information |
| Too many recent inquiries | Avoid unnecessary applications |
| Low credit score | Build consistent payment history |
| Insufficient credit history | Consider credit-building products |
| Income verification issue | Correct inaccurate information and prepare documentation |
| High debt | Review and reduce financial obligations |
Do not apply again simply because time has passed. Apply when your financial profile or eligibility has meaningfully improved.
Can You Get a Credit Card After Being Denied?
Yes, you may still qualify for another credit card, but approval depends on the issuer’s requirements.
Possible options include:
Secured Credit Cards
Secured cards typically require a refundable security deposit, which may influence the available credit limit.
They may be considered by applicants who want to establish or rebuild credit, although approval and reporting practices vary by issuer.
Student Credit Cards
Students may find cards designed for applicants with limited credit history. Eligibility requirements differ among issuers.
Credit-Builder Products
Some credit-building products are designed to help consumers establish payment history. Review fees, reporting practices, and account terms carefully.
Credit Union Cards
Credit unions may have different eligibility requirements from large banks. Membership may be required.
Compare annual fees, interest rates, deposit requirements, credit reporting, and other terms before applying.
Mistakes to Avoid After a Credit Card Denial
Mistake 1: Applying for Multiple Cards Immediately
Repeated applications may create additional hard inquiries and make it harder to understand why you were denied.
Mistake 2: Ignoring the Denial Notice
The adverse action notice can provide useful information about the lender’s decision.
Mistake 3: Applying With Incorrect Income
Always report income accurately and provide documentation when requested.
Mistake 4: Paying Companies That Guarantee Approval
Be cautious of companies promising guaranteed credit card approval in exchange for upfront fees or sensitive personal information.
Mistake 5: Ignoring Credit Report Errors
Incorrect information may continue affecting future applications if it is not investigated.
Mistake 6: Closing All Existing Credit Accounts
Closing accounts without considering their impact on utilization, account age, and financial management may not be the best response. Evaluate your situation before taking action.
Credit Card Application Denied With Good Credit: Why?
A good credit score is only one part of a credit card issuer’s decision.
You may still be denied because of:
- High balances
- Too many recent applications
- High debt obligations
- Insufficient income verification
- Existing exposure to the issuer
- Incomplete application information
- Card-specific eligibility standards
A good credit score improves your overall credit profile, but it does not guarantee approval.
Review the specific reason provided by the issuer rather than assuming that your credit score was the only factor.
Credit Card Application Denied Because of Income
Income-related denial may occur when the issuer cannot verify the information or determines that the application does not meet its requirements.
Before applying again:
- Confirm that your income details are accurate.
- Review whether the issuer accepts your income sources.
- Keep relevant documentation available.
- Avoid reporting income that you cannot reasonably support.
- Review your monthly debt obligations.
The issuer may consider income alongside credit history and other financial information.
Credit Card Application Denied Because of Credit History
If your credit history is limited or contains negative information, consider focusing on long-term credit improvement.
Helpful habits include:
- Paying accounts on time
- Keeping balances manageable
- Avoiding unnecessary applications
- Monitoring credit reports
- Maintaining accurate personal information
- Using credit only when repayment is affordable
Credit improvement generally requires consistent financial behavior over time.
Frequently Asked Questions
1. What is the most common reason for credit card application denial?
Common reasons include low credit score, limited credit history, high credit utilization, excessive debt, recent applications, and insufficient income verification. The exact reason depends on the issuer’s evaluation.
Review your adverse action notice to understand the main reason for your specific denial.
2. Can I apply for another credit card after being denied?
Yes, you may apply for another card, but applying immediately may result in additional hard inquiries. First, identify the reason for denial and determine whether another card matches your eligibility and financial situation.
3. Does a denied credit card application stay on my credit report?
The denial itself generally does not appear as a separate negative entry. However, the credit inquiry associated with the application may appear on your credit report, depending on how the issuer processed the application.
4. How can I improve my chances of credit card approval?
You can improve your application by paying bills on time, reducing credit utilization, correcting credit report errors, limiting unnecessary applications, and providing accurate income information.
No strategy guarantees approval because each issuer uses its own criteria.
5. Can I get a credit card with bad credit?
Some issuers offer secured cards or other products designed for consumers with limited or damaged credit. Eligibility, fees, deposit requirements, and credit reporting policies vary.
Compare the terms carefully before submitting an application.
6. Should I call the credit card company after denial?
You may contact the issuer to ask for clarification or determine whether reconsideration is available. Prepare questions about the denial reason and ask whether additional documentation can be reviewed.
Reconsideration is not guaranteed and may not be offered by every issuer.
7. Does applying for a credit card lower my credit score?
A credit card application may lead to a hard inquiry, which can affect your credit score. The impact varies depending on your credit profile and the scoring model used.
Some prequalification processes use soft inquiries, but you should confirm the process with the issuer.
8. Can a credit card company deny me because of my age or nationality?
Federal law prohibits creditors from discriminating on certain protected grounds, including race, color, religion, national origin, sex, marital status, and age when the applicant is legally able to enter into a contract.
Creditors may still consider lawful eligibility and repayment-related information. If you believe discrimination occurred, consider contacting the Consumer Financial Protection Bureau.
9. What if the information used to deny my application is incorrect?
Review your adverse action notice and obtain the relevant credit report. If you identify inaccurate information, you can dispute it with the credit reporting company and the company that supplied the information.
Keep copies of documents and correspondence related to your dispute.
10. How soon can I rebuild my credit after a denial?
The timeframe depends on the reason for denial and your financial circumstances. Paying on time, reducing balances, and correcting errors may help over time, but credit improvement is not immediate.
Focus on consistent financial habits rather than expecting a guaranteed result within a specific number of days.
Final Takeaway
Having your credit card application denied does not automatically mean you have poor financial habits or that you will never qualify for credit.
The best approach is to:
- Read your adverse action notice.
- Identify the specific denial reason.
- Review your credit reports.
- Correct inaccurate information.
- Reduce debt or utilization when necessary.
- Avoid unnecessary applications.
- Consider products that match your current credit profile.
Understanding why you were denied is the first step toward making a more informed credit decision.
Why Maintain Market Is Different
At Maintain Market, we focus on explaining financial products in a practical and easy-to-understand way.
Our guides aim to help readers:
- Understand credit and lending terminology.
- Compare available financial options.
- Identify potential risks and fees.
- Learn what questions to ask lenders.
- Make informed decisions based on their circumstances.
We encourage readers to verify current terms directly with financial institutions and official regulatory sources before applying.
References
- CFPB – What Can I Do If My Credit Application Was Denied?
- CFPB – Credit Discrimination Is Illegal
- CFPB – Information a Card Issuer Cannot Use
- AnnualCreditReport.com
- FTC – Credit and Loan Scams
Editorial Review
Reviewed by: Maintain Market Editorial Team
Focus: Credit cards, credit applications, credit reports, and personal finance education
Disclaimer: This article is for educational purposes only and does not guarantee credit approval or provide personalized financial advice.