Choosing between term life insurance vs whole life insurance can be confusing, especially when both policies promise financial protection for your loved ones. The biggest difference is how long the coverage lasts and what happens to the premiums you pay.
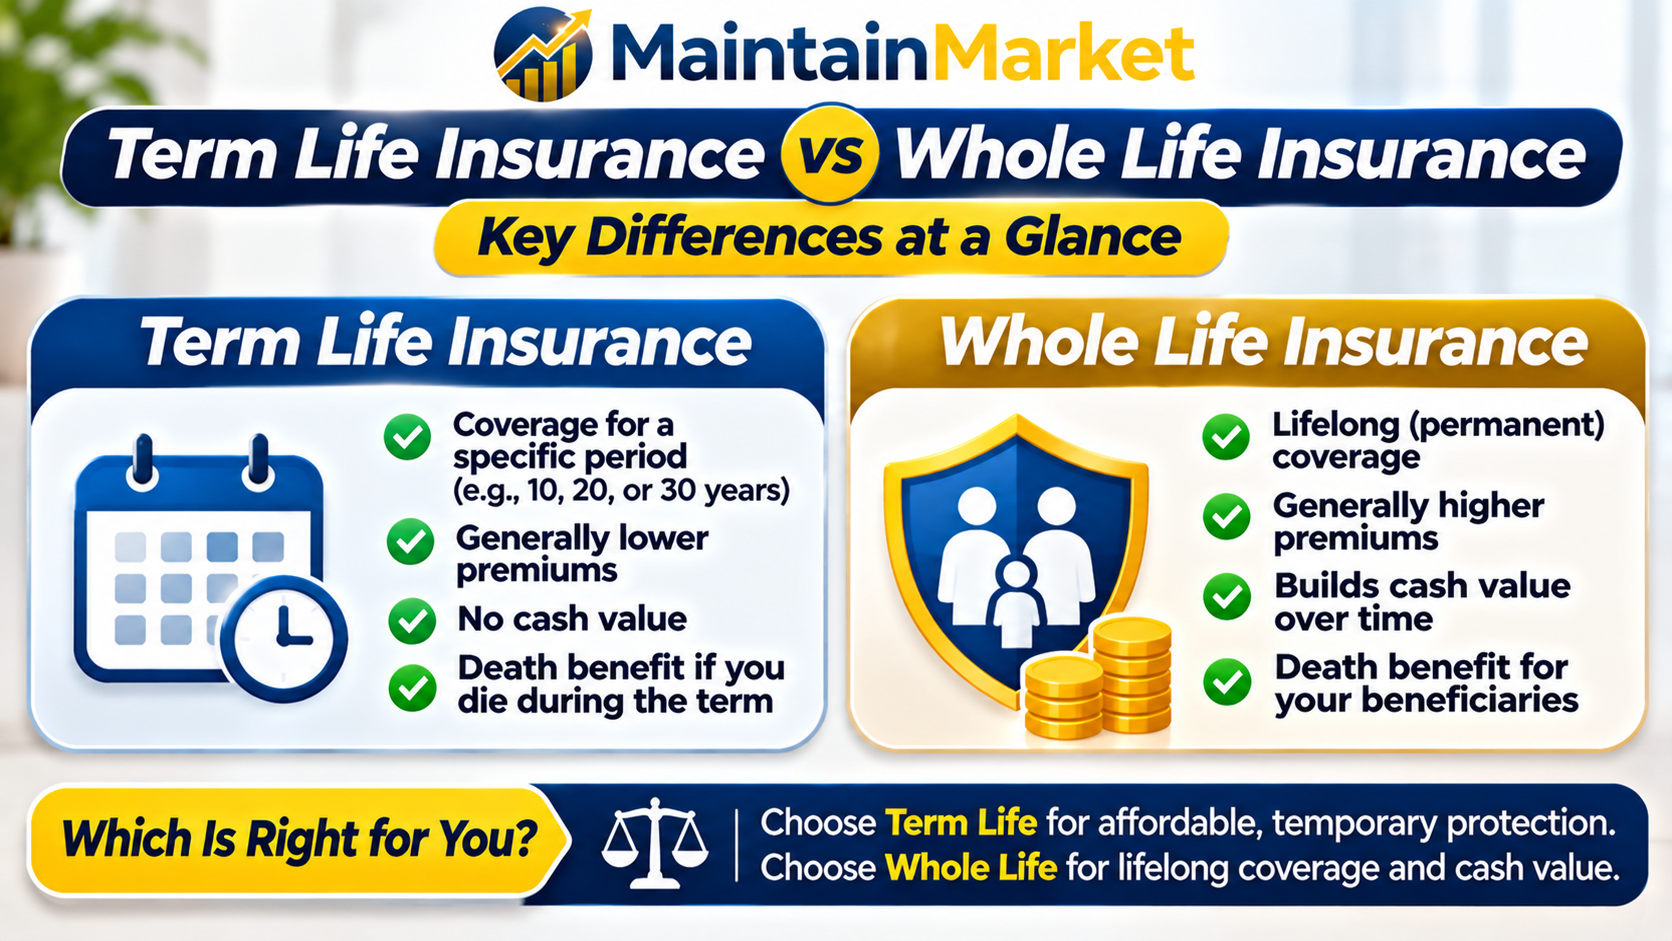
Term life insurance provides coverage for a specific period, such as 10, 20, or 30 years. Whole life insurance is designed to provide lifelong coverage, as long as the policy remains in force, and builds cash value over time.
Term life insurance generally costs less initially, making it useful for people who need substantial coverage for a limited period. Whole life insurance costs more but may suit people who want permanent coverage and a cash value feature.
Neither policy is automatically better. Your choice depends on your financial responsibilities, budget, age, dependents, and long-term goals.
This guide compares both types of life insurance, including their costs, benefits, limitations, and situations where each may make sense.
Quick Answer: Term Life Insurance vs Whole Life Insurance
The main difference is that term life insurance covers you for a selected period, while whole life insurance is designed to cover you throughout your lifetime.
| Feature | Term Life Insurance | Whole Life Insurance |
|---|---|---|
| Coverage duration | Specific period, such as 10, 20, or 30 years | Designed to last your lifetime |
| Premiums | Generally lower initially | Generally higher |
| Death benefit | Paid if the insured dies during the covered term | Paid when the insured dies, subject to policy conditions |
| Cash value | Does not build cash value | Builds cash value over time |
| Premium structure | Often level during the selected term | Generally fixed under traditional whole life policies |
| Policy loans | No cash value to borrow against | May allow borrowing against available cash value |
| Best suited for | Temporary financial protection | Long-term or lifelong protection |
In simple terms:
- Choose term life insurance if you need affordable coverage for a specific financial responsibility, such as a mortgage or raising children.
- Consider whole life insurance if you want permanent coverage, can afford the higher premiums, and value the policy’s cash value feature.
What Is Term Life Insurance?
Term life insurance is a policy that provides financial protection for a specified period. Common coverage periods include 10, 15, 20, and 30 years, although available terms depend on the insurer and applicant.
If the insured person dies while the policy is active, the insurance company generally pays the death benefit to the named beneficiaries, subject to the policy terms.
If the insured person outlives the policy term, the coverage usually ends without a death benefit being paid.
How Does Term Life Insurance Work?
Suppose you purchase a 20-year term life insurance policy with a $500,000 death benefit.
You pay the required premiums during the policy term. If you die while the policy is active, your beneficiaries may receive the $500,000 death benefit, subject to the contract.
If you survive the full 20 years, the policy generally expires and no death benefit is payable.
Some policies offer renewal or conversion options. However, renewal premiums may be substantially higher, and conversion rights may have deadlines or other conditions.
Advantages of Term Life Insurance
1. Lower initial premiums
Term life insurance generally costs less than comparable whole life coverage, particularly during the early policy years.
2. Higher coverage for a lower initial cost
Because the policy does not include a cash value feature, you may be able to purchase a larger death benefit for a lower premium.
3. Straightforward coverage
The policy provides a defined death benefit during a specified coverage period.
4. Useful for temporary financial responsibilities
It may help protect your family while you are paying a mortgage, raising children, or managing other financial obligations.
5. Potential conversion options
Some term policies allow you to convert coverage into a permanent policy without new medical underwriting, subject to the conversion rules and deadlines in the contract.
Disadvantages of Term Life Insurance
1. Coverage expires
If you outlive the selected term, coverage generally ends unless the policy is renewed or converted.
2. No cash value
Traditional term life insurance does not build savings or cash value that you can borrow against.
3. Renewal can become expensive
Renewing a term policy may result in significantly higher premiums, particularly as you get older.
4. New coverage may be harder to obtain later
If you need insurance after your term ends, your age and health may make a new policy more expensive or difficult to qualify for.
Who Should Consider Term Life Insurance?
Term life insurance may be worth considering if:
- You have young children or financially dependent family members.
- You have a mortgage or other large financial obligations.
- You want income protection for your family during your working years.
- You need a specific amount of coverage for a limited period.
- You want life insurance without paying for a cash value feature.
What Is Whole Life Insurance?
Whole life insurance is a type of permanent life insurance designed to provide coverage throughout the insured person’s lifetime, provided the policy remains in force and its requirements are met.
Unlike term life insurance, traditional whole life insurance includes a cash value component that grows over time according to the policy’s terms.
Whole life insurance generally has scheduled premiums, a stated death benefit, and guaranteed policy values. Participating policies may also pay dividends, but dividends are not guaranteed.
How Does Whole Life Insurance Work?
Suppose you purchase a whole life insurance policy with a $250,000 death benefit.
You pay premiums according to the policy schedule. Part of the premium supports the cost of insurance and policy expenses, while the policy also builds cash value over time.
If you die while the policy is in force, the insurer generally pays the contractual death benefit to your beneficiaries.
While you are alive, you may be able to borrow against the available cash value or surrender the policy for its cash surrender value, subject to applicable terms, charges, and tax consequences.
Advantages of Whole Life Insurance
1. Lifelong coverage
Traditional whole life insurance is designed to remain in force throughout your lifetime if the policy requirements are met.
2. Cash value accumulation
The policy builds cash value over time. This can provide access to funds during your lifetime through eligible policy loans or surrender.
3. Generally fixed premiums
Traditional whole life premiums are generally scheduled and do not increase as you age, provided the policy is maintained according to its terms.
4. Death benefit for beneficiaries
The policy provides a death benefit that can help beneficiaries manage financial obligations or receive an inheritance.
5. Potential dividends
Some participating whole life policies may pay dividends. These are not guaranteed and depend on the insurer’s experience and policy provisions.
Disadvantages of Whole Life Insurance
1. Higher premiums
Whole life insurance generally costs considerably more than term coverage with a comparable initial death benefit.
2. Cash value takes time to accumulate
Cash value may build slowly during the early policy years. The amount available if you surrender the policy can be lower than the total premiums you have paid.
3. Policy loans have consequences
Borrowing against cash value generally involves interest. An outstanding loan can reduce the death benefit and may cause the policy to lapse if it is not managed properly.
4. Less flexibility than some other financial products
Traditional whole life policies have specific premium schedules and contract conditions. They may not be suitable if you need flexible access to your money.
5. Early surrender can be costly
Cancelling a policy during its early years may result in surrender charges or receiving less than the premiums paid.
Who Should Consider Whole Life Insurance?
Whole life insurance may be worth considering if:
- You want permanent life insurance coverage.
- You have a long-term financial need for a death benefit.
- You can comfortably afford the premiums.
- You understand how cash value and policy loans work.
- You want to leave money to beneficiaries regardless of when you die, provided the policy remains in force.
Term Life Insurance vs Whole Life Insurance: 8 Major Differences
Understanding the differences can help you choose coverage that fits your financial situation.
1. Coverage Duration
The biggest difference is how long each policy is designed to provide protection.
Term life insurance covers you for a specific period. Whole life insurance is designed to provide coverage throughout your lifetime.
For example, a 20-year term policy may expire when you are 55 if you purchased it at age 35. A traditional whole life policy can remain in force beyond that age, subject to its terms.
Which is better?
It depends on how long your financial need will last. If your primary responsibility is a mortgage that should be paid off in 20 years, term coverage may be appropriate. If you want a lifelong death benefit, whole life may be worth comparing.
2. Monthly Premiums and Costs
Term life insurance generally has lower initial premiums because it provides coverage for a limited period and does not build cash value.
Whole life insurance generally costs more because it combines permanent insurance protection with a cash value component.
The actual premium depends on:
- Age
- Health history
- Tobacco use
- Coverage amount
- Policy features
- Insurer and underwriting results
Which is better?
Term life may be more affordable if your priority is obtaining a larger death benefit while keeping premiums lower.
Whole life may suit someone who can afford the higher premium and wants permanent coverage.
3. Cash Value
Term life insurance does not build cash value.
Whole life insurance builds cash value over time according to the contract.
For example, if you purchase a whole life policy, its cash value may gradually increase as you continue paying premiums. The amount available depends on the policy’s guaranteed values, expenses, and any applicable dividends or adjustments.
You may be able to borrow against the cash value, but loans can accrue interest and reduce the death benefit if they remain unpaid.
Which is better?
If you want a policy without a savings component, term life may be simpler. If you value permanent coverage with contractual cash value, whole life may be worth considering.
4. Death Benefit
Both term and whole life insurance provide a death benefit to named beneficiaries if the insured dies while the policy is in force.
The difference is the coverage period.
With term life insurance, the death benefit is generally payable only if death occurs during the selected term.
With whole life insurance, the death benefit is designed to remain available throughout the insured person’s lifetime, provided the policy remains in force.
Which is better?
The right choice depends on whether your family needs financial protection for a defined period or a lifelong benefit.
5. Flexibility
Term life insurance generally provides a straightforward structure, although renewal and conversion features may be available.
Whole life insurance has more policy features, including cash value, possible policy loans, and dividend options for participating policies.
However, these features come with specific rules and costs.
Which is better?
Term life may be easier to understand if you want straightforward temporary coverage. Whole life may offer additional features if you understand and need them.
6. Investment and Savings Features
Term life insurance is designed primarily for protection. It does not accumulate cash value.
Whole life insurance combines protection with a cash value feature.
However, cash value should not automatically be treated as an investment with returns comparable to stocks, mutual funds, or other market-based investments.
The policy’s costs, guarantees, dividend assumptions, and surrender conditions all matter.
Which is better?
If your main goal is life insurance protection, term coverage may be sufficient. If permanent insurance and cash value are important to you, examine the whole life policy’s guaranteed and non-guaranteed illustrations carefully.
7. Renewal and Conversion
Term policies may include renewal provisions that allow you to continue coverage after the original term. However, renewal premiums are generally higher and may increase at each renewal.
Some term policies also include a conversion option that allows you to convert to an eligible permanent policy without new medical underwriting, provided you meet the policy’s conversion conditions.
Whole life insurance generally does not need renewal at the end of a fixed term because it is designed as permanent coverage.
Which is better?
If you want temporary coverage with a possible route to permanent insurance later, compare term policies that include a conversion option.
8. What Happens If You Outlive the Policy?
If you outlive a standard term life policy, the coverage generally ends and no death benefit is paid. Some policies offer return-of-premium features, but these usually cost more and have specific conditions.
If you outlive a whole life policy that remains in force, the policy continues according to its terms and provides the contractual death benefit when the insured dies.
Which is better?
Term may be appropriate if your financial responsibilities are expected to end within the coverage period. Whole life may be appropriate if you want protection that is not tied to a fixed term.
Term Life vs Whole Life Insurance: Example
Let’s compare two hypothetical policies to understand the difference.
Suppose a 35-year-old applicant is comparing:
- A $500,000, 20-year term life policy
- A $500,000 whole life policy
The term policy is designed to provide protection for 20 years. The whole life policy is designed to provide permanent coverage and accumulate cash value.
The term policy will generally have a much lower initial premium than the whole life policy.
However, the whole life policy provides a cash value feature and is not designed to expire after 20 years.
| Comparison | 20-Year Term Policy | Whole Life Policy |
|---|---|---|
| Initial death benefit | $500,000 | $500,000 |
| Coverage duration | 20 years | Lifetime, subject to policy terms |
| Initial premium | Generally lower | Generally higher |
| Cash value | No | Yes |
| If insured survives 20 years | Coverage generally ends | Coverage continues |
| Policy loans | No | May be available against cash value |
This example illustrates the structural differences, not actual insurance quotes. Premiums and policy values vary based on the applicant, insurer, and contract.
Is Term Life Insurance Better Than Whole Life Insurance?
Term life insurance may be a better fit if you want substantial coverage for a specific period and prefer lower initial premiums.
Whole life insurance may be a better fit if you want permanent protection and can afford the higher premiums associated with cash value coverage.
Consider these situations:
| Your situation | Policy worth considering |
|---|---|
| You have young children who depend on your income | Term life |
| You have a mortgage with a defined repayment period | Term life |
| You want coverage for a specific number of years | Term life |
| You want a lifelong death benefit | Whole life |
| You want permanent coverage with cash value | Whole life |
| You have a long-term estate or legacy planning need | Whole life may be worth comparing |
The best policy is the one that meets your actual financial needs without creating an unaffordable premium obligation.
Can You Have Both Term and Whole Life Insurance?
Yes. Some people choose to combine term and whole life insurance.
This approach may provide a larger death benefit during years when financial responsibilities are highest, while maintaining a smaller amount of permanent coverage.
For example, a person may purchase:
- $500,000 in 20-year term coverage to protect their family while raising children and paying a mortgage.
- $100,000 in whole life coverage for a longer-term financial need.
The amounts above are only an illustration. The right combination depends on your financial obligations, budget, and existing coverage.
Combining policies can increase total premiums, so compare the cost against the actual protection you need.
Should You Buy Term Life and Invest the Difference?
You may have heard the phrase “buy term and invest the difference.”
The idea is to purchase lower-cost term insurance and invest the money you would otherwise spend on a more expensive whole life policy.
This approach may suit people who are comfortable managing separate investments and want to keep insurance and investing as distinct financial decisions.
However, it is not automatically the right strategy for everyone.
Consider:
- Whether you will consistently invest the premium difference
- Your investment risk tolerance
- Your time horizon
- The need for permanent insurance
- Your ability to maintain the term policy
- Taxes, fees, and investment expenses
Whole life insurance offers contractual guarantees and a permanent death benefit when maintained according to its terms. Investments outside an insurance policy have different risks and potential returns.
Compare both approaches based on your actual financial goals rather than assuming one always produces better results.
Common Mistakes to Avoid When Choosing Between Term and Whole Life Insurance
1. Choosing Whole Life Only Because It Builds Cash Value
Cash value is a feature, not proof that the policy is the best financial choice. Understand the premiums, guaranteed values, expenses, and surrender conditions.
2. Choosing Term Without Considering What Happens When It Ends
If you still need coverage after the term expires, renewing or purchasing another policy may be more expensive or difficult.
Check the renewal and conversion provisions before buying.
3. Buying More Coverage Than You Need
A larger death benefit may mean higher premiums. Estimate your family’s financial needs before choosing a coverage amount.
4. Ignoring Policy Illustrations
For whole life insurance, review guaranteed values separately from non-guaranteed dividends or projections.
Do not assume illustrated dividends will always be paid.
5. Cancelling an Existing Policy Without Comparing Alternatives
Replacing a policy can involve new underwriting, higher premiums, surrender charges, and a new contestability period. Review the existing and proposed policies before making a change.
6. Focusing Only on the Monthly Premium
A low premium does not necessarily mean the policy is suitable. Consider coverage duration, death benefit, exclusions, renewal terms, and long-term affordability.
Frequently Asked Questions
1. What is the main difference between term life and whole life insurance?
Term life insurance covers you for a specific period, while whole life insurance is designed to provide lifelong coverage. Whole life also builds cash value, whereas standard term life insurance does not.
2. Is term life insurance cheaper than whole life insurance?
Generally, yes. Term life insurance usually has lower initial premiums because it provides temporary coverage and does not build cash value. Whole life premiums are generally higher because the policy provides permanent coverage and cash value.
3. Can whole life insurance expire?
Traditional whole life insurance is designed to remain in force throughout the insured person’s lifetime if policy requirements are met. However, a policy can lapse or be surrendered under certain circumstances, including failure to meet required payments.
4. Do you get money back from term life insurance?
Standard term life insurance generally does not return premiums if you outlive the policy term. Some insurers offer return-of-premium term policies, but they generally cost more and have specific conditions.
5. Can I borrow money from whole life insurance?
You may be able to borrow against the available cash value of a whole life policy. Interest generally applies, and an unpaid loan can reduce the death benefit or affect the policy’s ability to remain in force.
6. Is whole life insurance a good investment?
Whole life insurance is primarily an insurance product with a cash value feature. Whether it suits your financial plan depends on its costs, guarantees, policy structure, and your need for permanent coverage. It should not be compared with investments solely on projected returns.
7. Can I convert term life insurance to whole life insurance?
Some term policies include a conversion option that allows you to convert to an eligible permanent policy without new medical underwriting. The available products, conversion deadlines, and other conditions depend on your contract.
8. What happens if I outlive my term life insurance policy?
The policy generally expires without a death benefit if you survive the term. You may be able to renew or convert the policy if those options are included in your contract.
9. Can I have term and whole life insurance at the same time?
Yes. You can own both types of coverage if you qualify and can afford the premiums. Some people combine term coverage for temporary needs with a smaller permanent policy for lifelong protection.
10. Which life insurance is better for seniors?
It depends on age, health, financial needs, and budget. Term insurance may be useful for a remaining financial obligation, while whole life may suit someone seeking permanent coverage. Older applicants should compare eligibility, premiums, and available coverage carefully.
Final Thoughts: Which Should You Choose?
The choice between term life insurance and whole life insurance comes down to the type of financial protection you need.
Term life insurance may be the more practical option if you want affordable coverage during a specific period, such as while raising children or paying off a mortgage.
Whole life insurance may be worth considering if you want permanent coverage, can afford the higher premiums, and understand how its cash value works.
Before purchasing either policy, compare quotes, review the contract, and consider how long your family may need financial protection.
You do not need the most expensive policy or the largest death benefit. You need coverage that fits your financial responsibilities and remains affordable.
At Maintain Market, our goal is to help you understand insurance options clearly so you can make informed decisions about protecting your family’s financial future.
Disclaimer: This article is for general educational purposes for U.S. consumers and is not individualized financial, investment, or insurance advice. Policy features, premiums, guarantees, conversion options, and eligibility vary by insurer, state, and applicant. Review the policy contract and consult a licensed insurance professional when necessary.
References
- National Association of Insurance Commissioners (NAIC) – Life Insurance
- NAIC – Life Insurance Buyer’s Guide
- NAIC – What Type of Life Insurance Is Right for You?
- NerdWallet – Term vs. Whole Life Insurance: Key Differences and How to Choose
- Fidelity – Term Life vs. Whole Life Insurance
- California Department of Insurance – Life Insurance Guide
Editorial Review: Reviewed for U.S. consumer relevance, accuracy of policy distinctions, and clarity. Premiums, policy guarantees, and available features vary by insurer and contract.