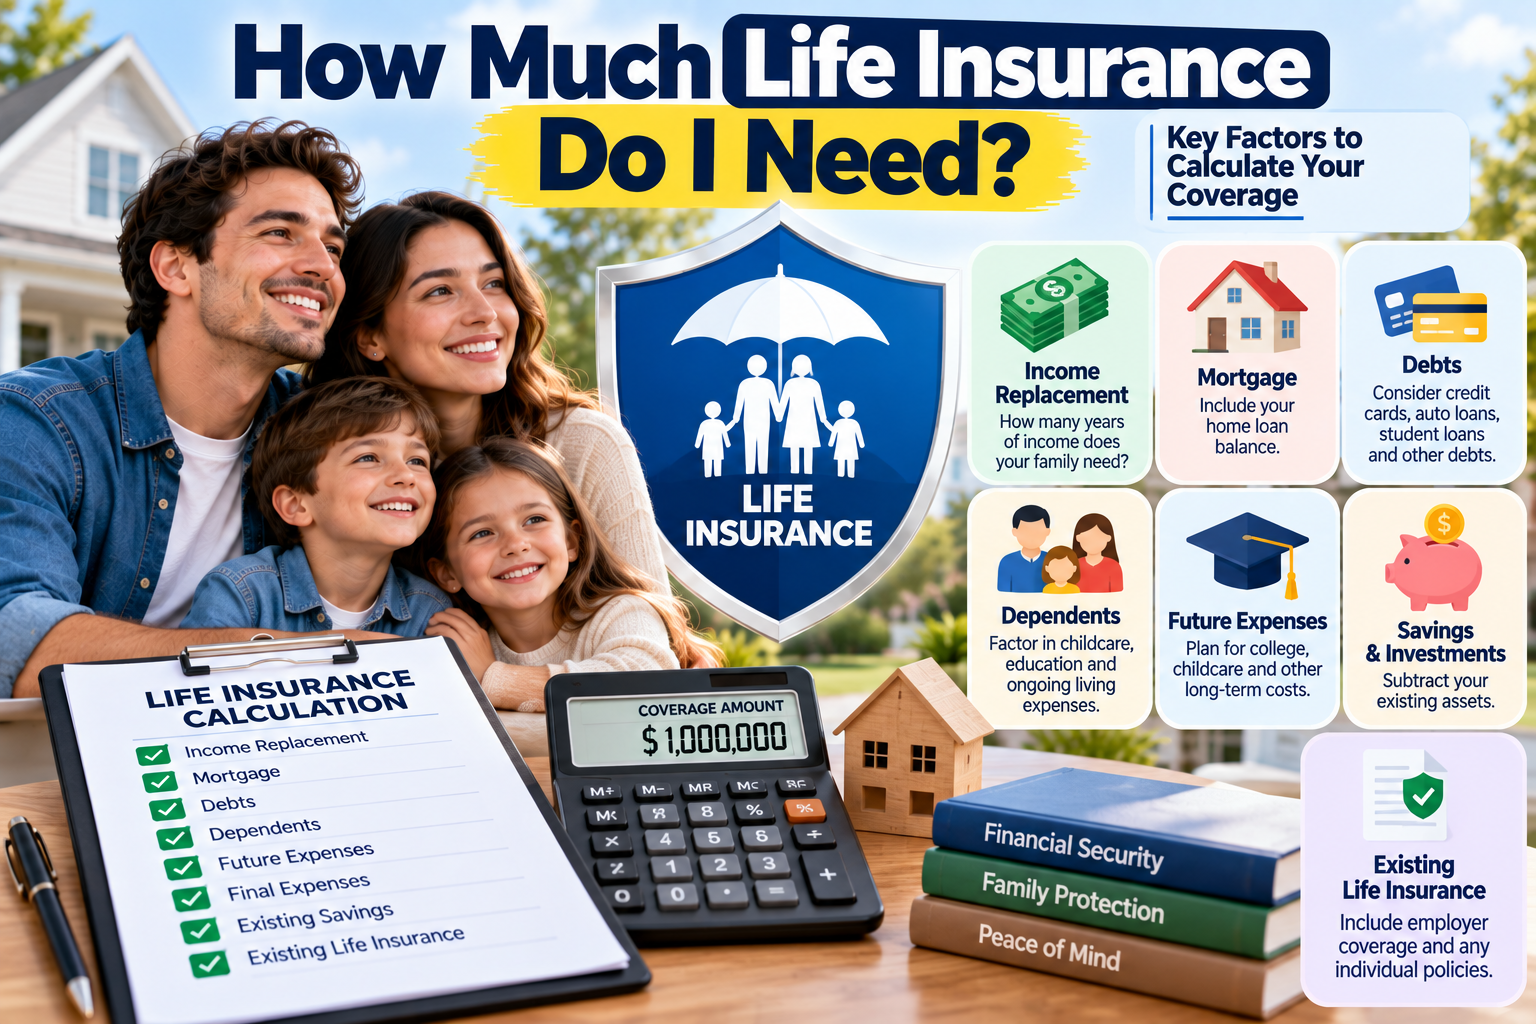
If you’re asking how much life insurance do I need, there isn’t one number that works for everyone. The right amount depends on your income, debts, mortgage, children, spouse or other dependents, future expenses, savings, existing life insurance, and how long your family would need financial support.
A simple rule such as 5 or 10 times your income can provide a starting point, but a more personalized calculation looks at the actual financial gap your family could face.
Quick Answer: How Much Life Insurance Do I Need?
A useful starting formula is:
Life Insurance Needed = Financial Obligations + Income Replacement + Future Expenses + Final Expenses − Existing Assets − Existing Life Insurance
Your calculation may include:
- Income your family would need to replace
- Mortgage and other debts
- Childcare and education costs
- Final expenses
- Ongoing household expenses
- Emergency financial needs
- Existing savings and investments
- Employer-provided life insurance
- Individual life insurance you already own
The NAIC recommends looking at how much family income you provide, who depends on you financially, debts, final expenses, education costs, inflation, and other future needs when determining coverage.
1. Start With the Income Your Family Depends On
Your income may be one of the largest financial resources your household would lose after your death.
Ask:
How much of my family’s current income comes from me?
If you earn $80,000 a year and your spouse or children rely heavily on that income, replacing some or all of it may require a significant death benefit.
You don’t necessarily need to replace your entire salary forever.
Instead, consider:
- How many years your family would need support
- Your spouse’s income
- Your children’s ages
- Expected retirement
- Existing savings
- Other sources of income
Example
Suppose you earn:
$80,000 per year
If your family needs income support for 10 years:
$80,000 × 10 = $800,000
That’s a starting point—not necessarily the final amount of insurance you need.
You would then add other financial obligations and subtract assets or existing coverage.
2. Calculate Your Outstanding Debts
Your family may have financial obligations that continue after your death.
Consider:
- Mortgage
- Credit cards
- Personal loans
- Private student loans
- Auto loans
- Business-related obligations
- Other significant debts
For example:
| Financial obligation | Amount |
|---|---|
| Mortgage | $300,000 |
| Auto loan | $25,000 |
| Other debt | $15,000 |
| Total | $340,000 |
If you want life insurance to help your family clear these obligations, the death benefit needs to account for them.
The NAIC specifically recommends considering how your family would repay debts after your death.
3. Consider Your Mortgage
Your mortgage can represent a major financial obligation.
If you have a $350,000 mortgage and your family wants the ability to pay it off after your death, you may include that amount in your calculation.
But you don’t necessarily have to use life insurance to completely eliminate the mortgage.
You might instead want enough coverage to:
- Pay off the mortgage
- Reduce the balance
- Cover several years of payments
- Give your spouse time to adjust financially
The right approach depends on your household’s finances.
4. Include Childcare and Education Costs
Children can create substantial future financial obligations.
Think about:
- Childcare
- School expenses
- College
- Transportation
- Housing
- Everyday living expenses
- Medical and other family costs
For example, if you have two young children, you may want your calculation to include a specific amount for future education.
You don’t have to predict the exact future tuition bill.
Instead, create a reasonable estimate based on your goals and current financial situation.
NAIC lists college tuition and daycare costs among the expenses consumers may consider when determining life-insurance needs.
5. Don’t Forget Final Expenses
Your family may also face expenses after your death.
These can include:
- Funeral expenses
- Burial or cremation
- Medical bills
- Legal or administrative costs
- Other final obligations
The amount varies significantly from person to person.
You can include an estimated amount in your coverage calculation rather than assuming that your family will have enough cash available to handle these expenses.
6. Subtract Your Existing Savings and Investments
Your life-insurance need isn’t necessarily equal to all of your financial obligations.
You may already have assets that your family could use.
Consider:
- Savings accounts
- Brokerage accounts
- Retirement accounts
- Certificates of deposit
- Other liquid investments
- Existing financial assets
For example:
Total financial need: $1,200,000
Existing assets: $200,000
Estimated insurance gap:
$1,200,000 − $200,000 = $1,000,000
This doesn’t mean your family should necessarily liquidate every investment after your death. It simply shows why existing assets can affect the amount of new insurance you may need.
7. Subtract Existing Life Insurance
Don’t forget coverage you already have.
You may have:
- Employer-sponsored life insurance
- An individual term policy
- Permanent life insurance
- Coverage from another organization
Example
Suppose your estimated financial need is:
$1,000,000
You already have:
$250,000 employer coverage
and:
$150,000 individual life insurance
Your existing coverage is:
$400,000
Potential additional coverage needed:
$1,000,000 − $400,000 = $600,000
This is only an illustration. Your employer policy may have conditions around portability or continuation after leaving the job.
The NAIC warns that employer-provided life insurance may not be enough to meet your family’s obligations and that coverage may not necessarily follow you when you leave the employer.
8. Consider How Long Your Family Needs Income Replacement
The amount of coverage and the length of coverage are connected.
For example, a parent with children ages 2 and 4 may have a longer income-replacement need than someone whose children are financially independent.
Consider:
- Children’s ages
- Mortgage term
- Retirement timeline
- Spouse’s expected retirement
- Debt repayment schedule
- Expected income growth
- Other financial responsibilities
This can help you decide whether a 10-, 20-, or 30-year term policy should be considered.
NAIC notes that consumers should consider not only how much coverage they need but also how long they anticipate needing death benefits.
9. Account for Inflation
A dollar today won’t necessarily buy the same amount in the future.
If you’re buying a policy designed to protect your family for decades, inflation matters.
For example, suppose your family currently needs $60,000 a year to maintain its lifestyle.
Over a long period, the cost of everyday expenses could increase.
That means simply multiplying today’s expenses by a fixed number of years may underestimate future needs.
You don’t need to predict inflation perfectly.
The goal is simply to recognize that future expenses may be higher than today’s expenses.
NAIC specifically lists inflation as one of the factors consumers should consider when determining life-insurance needs.
10. Use the 5–8× Income Rule Only as a Starting Point
You’ve probably heard:
Buy 5–8 times your annual income in life insurance.
The NAIC mentions this range as a rule some insurance experts suggest.
But the NAIC also recommends going through your actual financial circumstances to determine a more accurate amount.
For example:
$50,000 income
5× income:
$250,000
8× income:
$400,000
$75,000 income
5× income:
$375,000
8× income:
$600,000
$100,000 income
5× income:
$500,000
8× income:
$800,000
$150,000 income
5× income:
$750,000
8× income:
$1.2 million
These numbers are useful as rough starting points, but they don’t account for your mortgage, debts, children, savings, existing insurance, or other circumstances.
A Better Life Insurance Calculation Example
Let’s create an illustrative example.
Suppose:
Annual income: $90,000
Income replacement period: 10 years
$90,000 × 10 = $900,000
Now add:
Mortgage: $300,000
Other debts: $50,000
Future education expenses: $100,000
Final expenses: $20,000
Total estimated financial need:
$900,000 + $300,000 + $50,000 + $100,000 + $20,000 = $1,370,000
Now subtract:
Savings and investments: $170,000
Existing life insurance: $200,000
Estimated coverage gap:
$1,370,000 − $170,000 − $200,000 = $1,000,000
In this illustrative scenario, $1 million could be a starting point for comparing policies.
It is not a recommendation for everyone earning $90,000.
How Much Life Insurance Do I Need by Income?
Here is a simple starting table:
| Annual income | 5× income | 8× income | 10× income |
|---|---|---|---|
| $50,000 | $250,000 | $400,000 | $500,000 |
| $75,000 | $375,000 | $600,000 | $750,000 |
| $100,000 | $500,000 | $800,000 | $1,000,000 |
| $125,000 | $625,000 | $1,000,000 | $1,250,000 |
| $150,000 | $750,000 | $1,200,000 | $1,500,000 |
| $200,000 | $1,000,000 | $1,600,000 | $2,000,000 |
These are mathematical examples, not personalized insurance recommendations.
Your actual need could be significantly higher or lower depending on your family and finances.
How Much Life Insurance Does a Single Person Need?
A single person may need less life insurance than someone supporting a spouse and children, but being single does not automatically mean you need zero coverage.
Consider whether anyone depends on you financially.
You may also have:
- Student loans
- Private debts
- Mortgage
- Parents who depend on you
- Business obligations
- Final expenses
- Future financial responsibilities
If nobody depends on your income and you have few significant obligations, your immediate need may be relatively limited.
How Much Life Insurance Does a Married Person Need?
A married person should consider how much financial support their spouse would need if their income disappeared.
Think about:
- Both spouses’ incomes
- Mortgage
- Children
- Household expenses
- Debt
- Existing savings
- Retirement assets
- Employer life insurance
If both spouses earn income, you may still need coverage on both lives because the surviving spouse could face additional expenses after losing the other person’s income.
How Much Life Insurance Do Parents Need?
Parents often need to consider more than income replacement.
Your calculation may include:
- Childcare
- Education
- Housing
- Household expenses
- Mortgage
- Transportation
- Medical expenses
- Debt
- Future financial support
A stay-at-home parent may also have a meaningful life-insurance need because replacing childcare, household services, and other responsibilities can create substantial costs.
NAIC specifically says the value of services provided by a person, as well as daycare and other family expenses, can be relevant when determining coverage.
How Much Life Insurance Do I Need If I Have a Mortgage?
Start with your remaining mortgage balance.
Then decide whether your goal is:
- Full mortgage repayment
- Partial repayment
- Income replacement that includes mortgage payments
For example:
Mortgage balance: $400,000
You could include the $400,000 in your financial-obligation calculation if your goal is to provide enough coverage to pay it off.
But you should also consider whether your existing savings, spouse’s income, or other assets already provide some protection.
How Much Life Insurance Do I Need If I Have Student Loans?
It depends on the type of loan and who could remain financially responsible.
Consider:
- Federal student loans
- Private student loans
- Co-signed loans
- Other education debt
Don’t automatically assume every student loan needs to be covered by life insurance.
Review the terms of the specific loan and consider who could be responsible for the balance after death.
How Much Life Insurance Do I Need If I Am a Stay-at-Home Parent?
A stay-at-home parent may still have a significant economic contribution to the household.
If that person dies, the surviving parent may need to pay for:
- Childcare
- Household help
- Transportation
- Meal preparation
- Other services
NAIC recommends considering the value of services provided by the insured when evaluating life-insurance needs.
So, income alone should not be the only factor.
Term Life vs Permanent Life Insurance for Coverage Needs
Once you’ve estimated the amount of coverage you need, you still need to consider what type of policy fits your situation.
| Feature | Term Life | Permanent Life |
|---|---|---|
| Coverage | Specific period | Designed for long-term/lifetime coverage |
| Cash value | Generally no | Depending on policy, yes |
| Initial premiums | Generally lower | Generally higher |
| Common use | Income/debt protection for a defined period | Long-term financial or estate-planning needs |
| Complexity | Generally simpler | Can be more complex |
NAIC explains that term insurance generally covers a specific period and tends to have lower premiums in the early years, while permanent policies provide long-term protection and may include cash value.
Should I Buy More Life Insurance Than I Need?
Buying more coverage isn’t automatically better.
More coverage generally means higher premiums.
Instead, focus on the financial gap your family could realistically face.
At the same time, don’t underestimate future needs simply because a smaller policy has a lower premium.
The goal is to balance:
Coverage + affordability + duration
What If I Already Have Life Insurance?
Start by reviewing your existing policy.
Check:
- Death benefit
- Policy type
- Remaining term
- Premium
- Beneficiaries
- Employer coverage
- Conversion options
- Policy exclusions
Then compare your existing coverage with your current financial obligations.
Your needs may have changed because of:
- Marriage
- Children
- New mortgage
- Higher income
- New debt
- Divorce
- Retirement planning
- Changes in dependents
The NAIC recommends reviewing an existing policy before buying a new one and warns against cancelling an existing policy before the replacement coverage is in place.
Life Insurance Needs Calculator: Simple Formula
You can use this basic worksheet:
Step 1: Income replacement
Annual income × years of replacement
$________
Step 2: Debts
Mortgage + loans + other debts
$________
Step 3: Future expenses
Education + childcare + other major expenses
$________
Step 4: Final expenses
Funeral + medical + other final costs
$________
Step 5: Other financial needs
$________
Step 6: Subtract existing assets
Savings + investments
− $________
Step 7: Subtract existing life insurance
Employer + individual policies
− $________
Estimated coverage gap
$________
This gives you a starting point for discussing coverage with a licensed insurance professional.
Common Life Insurance Calculation Mistakes
Using only your salary
Income is important, but it isn’t the whole calculation.
Forgetting the mortgage
A large mortgage can significantly change your family’s financial needs.
Ignoring childcare
Childcare can become a major expense if one parent dies.
Forgetting existing coverage
Employer and individual policies should be included.
Ignoring inflation
Future expenses may be higher than today’s expenses.
Buying based only on a 10× rule
A multiplier is a shortcut, not a complete financial analysis.
Forgetting stay-at-home contributions
Household services have economic value even when they don’t appear as a salary.
Cancelling existing insurance too soon
Do not cancel an existing policy simply because you’ve applied for a replacement.
Frequently Asked Questions
How much life insurance do I need?
Your coverage need depends on income replacement, debts, dependents, future expenses, final expenses, existing assets, and existing insurance. A personalized calculation is generally more useful than applying one income multiplier to everyone.
Is 10 times my income enough for life insurance?
It may be enough for some people and insufficient for others. Your mortgage, children, debts, savings, existing coverage, and future financial needs can significantly change the amount required.
Is 5 to 8 times my salary enough for life insurance?
The NAIC identifies 5–8 times income as a rule some insurance experts suggest, but it recommends considering your actual financial circumstances to determine a more accurate amount.
How much life insurance does a $100,000 earner need?
A simple 5–8× income calculation produces $500,000 to $800,000, but that is only a starting point. Your actual need could be higher or lower depending on debts, dependents, savings, existing insurance, and future expenses.
How much life insurance should a family of four have?
There is no standard amount for every family of four. Consider both parents’ incomes, children’s ages, mortgage, debts, childcare, education, savings, and existing life insurance.
Do stay-at-home parents need life insurance?
They may. A stay-at-home parent’s household responsibilities can have significant economic value because replacing childcare and other services can create substantial expenses.
Should I include my mortgage in my life insurance calculation?
Yes, if your goal is for the death benefit to help your family repay the mortgage. You can also calculate the coverage needed to replace income while continuing mortgage payments.
Should I subtract savings from the amount of life insurance I need?
Savings and other assets can be considered when calculating the financial gap your family could face. Whether you would actually want those assets used after your death is a separate financial-planning decision.
Is employer life insurance enough?
It depends on the amount of coverage and your family’s financial obligations. Employer coverage may be useful, but it may not provide enough protection and may not necessarily continue if you leave the employer.
Are life insurance death benefits taxable?
Generally, life-insurance proceeds paid to a beneficiary because of the insured person’s death are not included in gross income for federal income-tax purposes. However, interest associated with the proceeds can be taxable, and specific circumstances can produce different tax treatment.
Final Takeaway
If you’re asking how much life insurance do I need, don’t rely on a single multiplier.
Start with your family’s actual financial needs:
Income replacement + debts + future expenses + final expenses − existing assets − existing insurance = estimated coverage gap.
Then consider how long your family would need that protection and whether term or permanent insurance fits your situation.
The 5–8× income rule can provide a quick starting point, but a more detailed calculation can give you a much better picture of the coverage your household may need.
Life insurance should be affordable enough that you can maintain the policy while providing meaningful financial protection to the people who depend on you.
Why Maintain Market Is Different
Maintain Market focuses on explaining the financial calculation behind insurance decisions rather than simply giving readers a generic coverage number.
For life insurance, that means looking at:
- Income replacement
- Mortgage and debt
- Children and dependents
- Childcare
- Education
- Final expenses
- Inflation
- Savings and investments
- Existing employer coverage
- Existing individual policies
- Policy duration
Your actual insurance need depends on your household and financial circumstances. Consider discussing the calculation with a licensed insurance professional or financial advisor before purchasing coverage.
References
- NAIC — Life Insurance
- NAIC — Consumer Insight: Life Insurance Roadmap
- NAIC — Consumer Life Insurance Guide
- NAIC — Life Insurance Topics
- IRS — Life Insurance & Disability Insurance Proceeds
- IRS — Publication 559: Survivors, Executors, and Administrators
Editorial Review
Reviewed for U.S. life-insurance coverage calculations, income replacement, dependents, debt, final expenses, existing coverage, term versus permanent insurance, and general federal tax treatment of life-insurance proceeds. Individual insurance needs, policy terms, premiums, and tax circumstances vary.
Recommended Reads
- Best Life Insurance for Young Adults — Compare term, employer, no-exam, and permanent life insurance options for younger U.S. consumers.
- Life Insurance Without Medical Exam — Understand accelerated underwriting, simplified issue, guaranteed issue, and other no-exam life insurance options.