Finding the right life insurance for seniors can become more challenging as you get older. Premiums generally increase with age, and some insurers have restrictions on who can apply. However, adults in their 60s, 70s, and even 80s may still have several coverage options.
Whether you want to leave money for your family, pay outstanding debts, cover funeral expenses, or provide a financial legacy, choosing the right policy starts with understanding your needs.
Some insurers worth comparing include Guardian, New York Life, Mutual of Omaha, Pacific Life, MassMutual, and USAA. Each offers different policy types, eligibility requirements, and coverage options.
This guide explains the best types of life insurance for seniors, companies to compare, estimated costs, and important factors to consider before purchasing a policy in the United States.
Quick Answer: What Is the Best Life Insurance for Seniors?
The best life insurance for seniors depends on your age, health, budget, and financial goals.
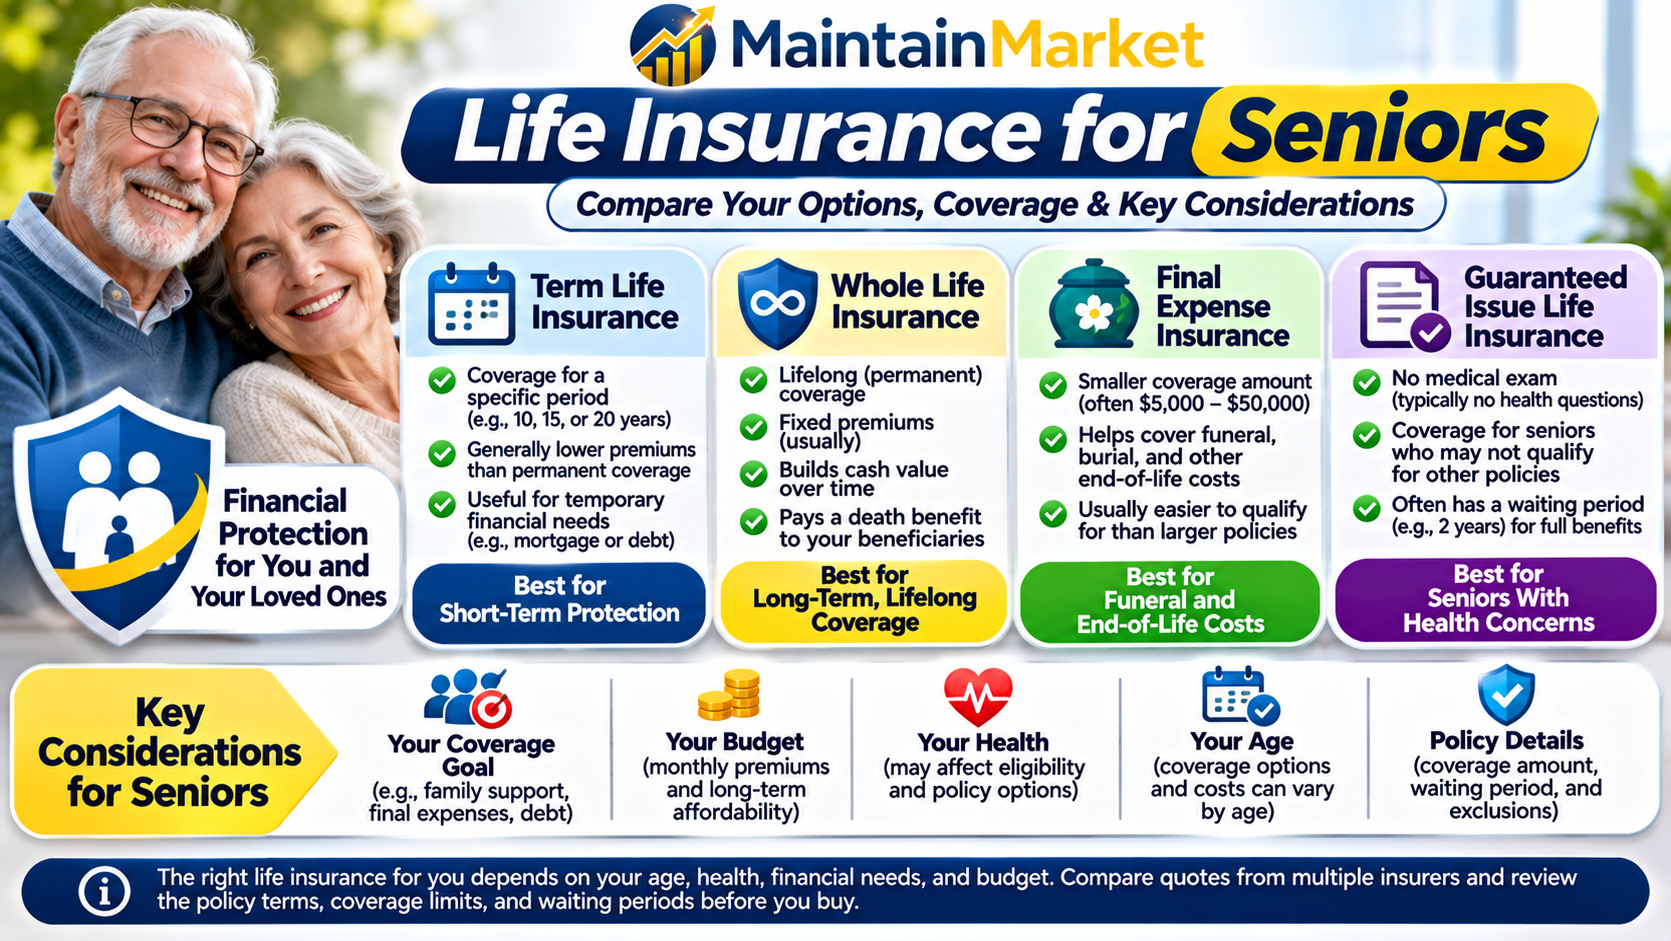
- Term life insurance: Worth considering if you need coverage for a specific period, such as paying off a mortgage or supporting a dependent.
- Whole life insurance: Suitable for people who want permanent coverage with a fixed death benefit and cash value.
- Final expense insurance: Designed to provide a smaller death benefit that can help cover funeral and other end-of-life expenses.
- Guaranteed issue life insurance: An option for some applicants who cannot qualify for medically underwritten coverage, although premiums can be higher and benefits may be limited.
Companies worth comparing include Guardian, New York Life, Mutual of Omaha, Pacific Life, and MassMutual. Availability and eligibility vary by policy and state.
There is no single best insurer for every senior. Compare several quotes and review the policy details before making a decision.
Best Life Insurance Companies for Seniors in 2027
The following companies have been highlighted in recent third-party insurance comparisons. They are options to investigate, not a universal ranking or guarantee of the lowest price.
1. Guardian Life: Worth Considering for Flexible Coverage
Guardian offers term and permanent life insurance products, including whole life coverage.
It may appeal to seniors who want to compare permanent coverage and flexible payment arrangements.
Why consider Guardian?
- Term and whole life insurance options
- Permanent coverage options
- Potential conversion features on eligible term policies
- Whole life coverage available to older applicants, subject to product rules
Potential limitations:
- Eligibility depends on the specific policy.
- Premiums can be substantial for older applicants.
- Some products may require medical underwriting.
Best for: Seniors comparing permanent coverage and flexible premium arrangements.
2. New York Life: Worth Considering for Final Expense Coverage
New York Life offers several life insurance products, including coverage through its AARP life insurance program.
Its guaranteed acceptance option may appeal to older adults who have difficulty qualifying for traditional medically underwritten policies.
Why consider New York Life?
- Term and permanent insurance options
- Guaranteed acceptance coverage through the AARP program for eligible applicants
- No medical exam for certain products
- Final expense coverage options
Potential limitations:
- AARP membership requirements may apply.
- Coverage amounts are limited under some guaranteed acceptance products.
- Certain policies have waiting periods before the full death benefit becomes payable.
Best for: Seniors looking for smaller permanent policies to help with final expenses.
3. Mutual of Omaha: Worth Comparing for Final Expense Insurance
Mutual of Omaha offers life insurance products that may suit older adults looking for smaller permanent coverage.
Its simplified-issue and other senior-focused products may provide alternatives to traditional underwriting, depending on eligibility.
Why consider Mutual of Omaha?
- Final expense coverage options
- Whole life insurance products
- Options with simplified underwriting
- Coverage designed for older applicants
Potential limitations:
- Product availability varies by state.
- Health questions and eligibility rules depend on the policy.
- Premiums and coverage limits vary by applicant.
Best for: Seniors who want to compare final expense and smaller whole life policies.
4. Pacific Life: Worth Considering for Term and Permanent Coverage
Pacific Life offers term and permanent life insurance products. Its term insurance may be relevant to seniors who still need coverage for a defined period.
Why consider Pacific Life?
- Term life insurance options
- Universal life and other permanent coverage products
- Conversion features on eligible policies
- Different coverage structures depending on financial needs
Potential limitations:
- Eligibility and maximum application ages depend on the product.
- Some policies may require working with an insurance professional.
- Premiums depend on age, health, coverage amount, and policy structure.
Best for: Seniors who want to compare term and permanent insurance options.
5. MassMutual: Worth Comparing for Whole Life Insurance
MassMutual offers whole life and other permanent insurance products.
Whole life coverage may be useful for seniors who want lifelong protection and a policy that builds cash value.
Why consider MassMutual?
- Whole life insurance options
- Permanent coverage
- Cash value accumulation under policy terms
- Different coverage and payment structures
Potential limitations:
- Premiums can be higher than term insurance.
- Medical underwriting may apply.
- Dividends, if applicable, are not guaranteed.
Best for: Seniors comparing permanent coverage and long-term financial protection.
6. USAA: An Option for Eligible Military Families
USAA offers life insurance products for eligible customers, including certain military members, veterans, and family members.
Its coverage options may be worth comparing if you meet membership eligibility requirements.
Why consider USAA?
- Term and permanent life insurance options
- Coverage conversion features on eligible products
- Products designed for different financial needs
- Options for eligible military families
Potential limitations:
- Membership eligibility applies.
- Maximum issue ages vary by product.
- Coverage terms and prices depend on the applicant.
Best for: Eligible military members, veterans, and their families comparing life insurance.
Life Insurance Companies for Seniors Compared
| Company | Worth comparing for | Important consideration |
|---|---|---|
| Guardian | Flexible permanent coverage | Underwriting and premium options |
| New York Life | AARP and final expense coverage | Membership and waiting-period terms |
| Mutual of Omaha | Final expense and whole life | Product eligibility |
| Pacific Life | Term and permanent coverage | Maximum application age |
| MassMutual | Whole life insurance | Premium affordability |
| USAA | Eligible military families | Membership requirements |
Recent comparisons from NerdWallet and CNBC Select also identify several of these insurers among the companies worth considering for older adults. Their rankings use different methodologies, so compare the actual policies rather than relying only on a company ranking.
Types of Life Insurance Available for Seniors
Before choosing an insurer, understand the different policy types. The right option depends on how long you need coverage and what you want the death benefit to accomplish.
1. Term Life Insurance
Term life insurance provides coverage for a specified period, such as 10, 15, or 20 years.
If the insured person dies while the policy is active, the insurer generally pays the death benefit to the named beneficiaries, subject to policy terms.
Advantages:
- Generally lower initial premiums than comparable permanent coverage
- Straightforward coverage structure
- Useful for temporary financial obligations
- May provide larger coverage amounts for a limited period
Disadvantages:
- Coverage expires at the end of the selected term.
- Renewing coverage may become expensive.
- Eligibility can become more restrictive with age.
- It generally does not build cash value.
Example: A 65-year-old who still has 10 years remaining on a mortgage may consider a 10-year term policy to provide financial protection during that period.
2. Whole Life Insurance
Whole life insurance is a type of permanent life insurance designed to remain in force throughout the insured person’s lifetime, provided required premiums are paid and policy conditions are met.
It generally includes a death benefit and a cash value component.
Advantages:
- Permanent coverage
- Generally fixed premiums under traditional policies
- Cash value accumulation
- Death benefit for beneficiaries
Disadvantages:
- Usually more expensive than term insurance.
- Cash value builds gradually.
- Early surrender may result in financial losses.
- Policy loans and withdrawals can affect the death benefit.
Best for: Seniors who want permanent coverage and can comfortably afford the premiums.
3. Final Expense Insurance
Final expense insurance is generally a smaller whole life policy designed to help beneficiaries manage costs associated with the policyholder’s death.
The money may help with:
- Funeral expenses
- Burial or cremation costs
- Outstanding medical bills
- Small personal debts
- Other final expenses
Coverage amounts are usually lower than those available through larger traditional life insurance policies.
Advantages:
- Smaller coverage amounts may be easier to budget for.
- Some products use simplified underwriting.
- Can provide permanent coverage.
- Designed around end-of-life expenses.
Disadvantages:
- Premiums can be relatively high compared with the coverage amount.
- Coverage limits are generally modest.
- Some policies include graded death benefits or waiting periods.
Best for: Seniors primarily interested in helping their families manage final expenses.
4. Guaranteed Issue Life Insurance
Guaranteed issue life insurance is a type of policy that generally does not require a medical exam or health questions.
It may be available to people who cannot qualify for other coverage because of certain health conditions.
However, guaranteed acceptance does not mean the policy has no limitations.
Advantages:
- No medical exam
- Generally no health questions
- May provide access to coverage for people with significant health issues
Disadvantages:
- Premiums can be expensive.
- Coverage amounts are often limited.
- Many policies include a graded death benefit period.
- A full death benefit may not be payable for certain non-accidental deaths during the initial waiting period.
Best for: Seniors who have difficulty qualifying for traditional coverage and understand the policy’s limitations.
Before purchasing, read the policy carefully to understand the waiting period, exclusions, premium obligations, and circumstances in which beneficiaries receive the full death benefit.
5. Guaranteed Universal Life Insurance
Guaranteed universal life insurance is a form of permanent life insurance designed to provide coverage to a specified age or potentially for life, depending on the policy structure and premium requirements.
It generally focuses more on maintaining a death benefit than building significant cash value.
Advantages:
- Potentially long-lasting coverage
- May provide more flexible premium structures than traditional whole life
- Can be used for longer-term financial protection
Disadvantages:
- Policy performance depends on meeting contractual requirements.
- Premium payments and funding must be carefully maintained.
- Some policies may lapse if required conditions are not met.
Best for: Seniors who want to compare long-term death benefit protection and understand the policy’s funding requirements.
How Much Does Life Insurance for Seniors Cost?
The cost of life insurance generally increases as you get older. However, your age is only one part of the calculation.
Insurers may consider:
- Age at application
- Sex, where permitted in underwriting
- Health history
- Tobacco use
- Coverage amount
- Policy type
- Term length
- State of residence
- Underwriting results
Example: Why Policy Type Matters
A term policy and a whole life policy with the same death benefit can have very different premiums.
For example, a 70-year-old considering $250,000 in coverage may receive substantially different quotes depending on whether the policy is a 10-year term or permanent whole life policy.
As MoneyGeek comparison illustrates this difference: its analyzed average monthly rates for a 70-year-old woman with $250,000 of coverage were approximately $165 for term life and $1,189 for whole life. These are specific research estimates, not universal quotes or guaranteed prices.
Actual premiums can differ considerably based on health, underwriting, insurer, and policy design.
How to Get an Accurate Life Insurance Quote
Instead of relying on general averages:
- Decide how much coverage you need.
- Choose the policy type that matches your financial goal.
- Compare at least three insurers.
- Provide accurate health and lifestyle information.
- Compare premiums and policy guarantees.
- Review the exclusions and waiting periods.
- Check the insurer’s financial strength.
A personalized quote is more useful than a broad average when deciding whether a policy fits your budget.
What Is the Best Life Insurance for Seniors Over 60?
Adults in their 60s may still have several coverage options, including term life, whole life, and universal life insurance.
The right choice depends on the reason for purchasing coverage.
Consider:
- Mortgage protection: Term life may be worth comparing if you have a defined period of outstanding mortgage payments.
- Family financial support: Term or permanent coverage may help provide financial protection for dependents.
- Final expenses: A smaller whole life or final expense policy may be suitable.
- Long-term protection: Whole life or guaranteed universal life may be worth considering.
If you are relatively healthy, compare traditional underwriting options before choosing guaranteed issue coverage. A medically underwritten policy may offer more coverage for the premium.
What Is the Best Life Insurance for Seniors Over 70?
People over 70 may face higher premiums and more restrictive eligibility requirements. However, coverage may still be available depending on health, insurer, and policy type.
Possible options include:
- Shorter-term life insurance, if available
- Whole life insurance
- Final expense insurance
- Guaranteed issue life insurance
- Certain universal life policies
At this age, it is particularly important to compare the cost of coverage against the financial need it is intended to address.
For example, if the main goal is to cover funeral costs, a smaller final expense policy may be more appropriate than an expensive policy with a large death benefit.
Can Seniors Over 80 Get Life Insurance?
Yes, some insurers offer coverage to applicants over 80, although choices may be limited.
Guaranteed issue and final expense policies may be worth investigating, depending on state availability and product eligibility.
Before applying, consider:
- Maximum application age
- Available death benefit
- Monthly premium
- Waiting period
- Whether the policy requires health questions
- Total premiums over time
If the premium is difficult to afford, consider whether saving money separately for final expenses would be more appropriate.
Do not purchase a policy simply because an agent says you are guaranteed to qualify. Read the actual contract and understand its conditions.
How to Choose the Right Life Insurance Policy as a Senior
Choosing life insurance should begin with your financial goals rather than a company advertisement.
1. Identify Why You Need Coverage
Ask yourself:
- Do I want to cover funeral expenses?
- Do I have outstanding debts?
- Does anyone depend on my income?
- Do I want to leave money to my family?
- Do I need coverage for a mortgage or other financial obligation?
The answer helps determine the appropriate policy type and coverage amount.
2. Calculate How Much Coverage You Need
You do not necessarily need a large policy.
Start by estimating:
- Funeral and burial expenses
- Outstanding debts
- Financial support for dependents
- Mortgage obligations
- Other expenses you want your beneficiaries to cover
Then consider existing savings and other assets that could help meet those obligations.
The objective is to purchase enough coverage to address the financial need without paying for protection you do not require.
3. Compare Monthly Premiums
A policy should fit comfortably within your retirement income or household budget.
Avoid selecting a policy with premiums that may become difficult to maintain.
If a permanent policy has expensive premiums, compare whether a smaller policy or another type of coverage would better meet your needs.
4. Understand Medical Underwriting
Traditional life insurance policies may require health questions, medical records, or a medical examination.
Some insurers offer simplified underwriting, while guaranteed issue policies generally do not require health questions.
If you have a pre-existing condition, compare several insurers. Their underwriting rules may differ.
5. Review Waiting Periods and Exclusions
Some guaranteed issue and final expense policies have graded death benefits.
This means beneficiaries may receive only a refund of premiums, possibly with interest, rather than the full death benefit if the insured dies from certain causes during the initial waiting period.
Understand exactly what is payable and when.
6. Check the Insurer’s Financial Strength
Life insurance is a long-term financial commitment. Review the financial strength ratings of the actual company issuing the policy.
Independent rating agencies such as AM Best assess insurers’ financial strength. Ratings can change, so verify current information before purchasing.
7. Read the Policy Before Signing
Review:
- Premium payment requirements
- Death benefit
- Coverage duration
- Cash value provisions, if applicable
- Exclusions
- Waiting periods
- Policy loan provisions
- Surrender charges
- Beneficiary details
Ask the insurer or licensed insurance professional to explain anything you do not understand.
Do Seniors Really Need Life Insurance?
Not every senior needs life insurance.
If you have no dependents, no significant outstanding obligations, and enough savings to cover final expenses, purchasing a new policy may not be necessary.
However, life insurance may still be useful if:
- Your spouse depends on your financial support.
- You have outstanding debts that could affect your family.
- You want to provide money for funeral expenses.
- You want to leave a financial legacy.
- You have a dependent family member who needs ongoing support.
Consider the premium cost and the actual financial need before deciding.
Common Mistakes Seniors Should Avoid
1. Buying More Coverage Than Necessary
A large death benefit may sound attractive, but it can create expensive premiums. Calculate your actual financial needs first.
2. Choosing Guaranteed Issue Without Comparing Other Options
Guaranteed issue policies can be useful for some applicants, but they may have higher premiums and lower coverage limits. Compare medically underwritten and simplified-issue alternatives if you qualify.
3. Ignoring the Waiting Period
Some policies do not pay the full death benefit for certain causes of death during the initial waiting period. Read the policy terms carefully.
4. Trusting Guaranteed Savings Claims
No insurer can guarantee that its policy will be the cheapest for every senior. Compare personalized quotes.
5. Letting an Existing Policy Lapse Without Reviewing Alternatives
If you already have life insurance, understand the consequences of cancelling or replacing it. A new policy may be more expensive or harder to qualify for because of your age or health.
6. Hiding Medical Information
Providing inaccurate health information can create problems when a claim is reviewed. Answer application questions honestly and completely.
Frequently Asked Questions
1. What is the best life insurance for seniors?
The best policy depends on your financial needs, age, health, and budget. Term insurance may suit temporary obligations, while whole life and final expense insurance may suit people seeking permanent coverage.
2. Can a 70-year-old get life insurance?
Yes. Some insurers accept applications from people aged 70 and older. Available policy types, coverage amounts, and premiums depend on the insurer and applicant.
3. Can an 80-year-old get life insurance?
Some insurers offer coverage to applicants over 80, particularly through certain final expense and guaranteed issue products. Eligibility and coverage limits vary by state and policy.
4. Is term or whole life insurance better for seniors?
Term life may be less expensive initially and is designed for a specific coverage period. Whole life provides permanent coverage and generally includes cash value, but premiums are usually higher. The appropriate option depends on your goals and budget.
5. What is the cheapest life insurance for seniors?
There is no universally cheapest insurer. Premiums depend on age, health, coverage amount, policy type, and underwriting. Compare personalized quotes from multiple companies.
6. Can seniors get life insurance without a medical exam?
Yes. Some insurers offer simplified-issue and guaranteed issue policies without a traditional medical examination. However, simplified-issue coverage may still require health questions, while guaranteed issue products generally have lower coverage limits and may include waiting periods.
7. Is guaranteed issue life insurance worth it?
It may be useful if you cannot qualify for traditional coverage and need a smaller death benefit for final expenses. However, compare the premiums, waiting period, and total benefit before purchasing.
8. Does Medicare include life insurance?
No. Medicare is primarily health insurance for eligible people, not life insurance. It does not provide a traditional death benefit to beneficiaries.
9. Can seniors with pre-existing conditions get life insurance?
Possibly. Some insurers may accept applicants with certain medical conditions, depending on the condition, severity, treatment, and underwriting requirements. Guaranteed issue coverage may be another option, but its limitations should be reviewed.
10. How much life insurance should a senior have?
The amount depends on outstanding debts, final expenses, dependents, existing savings, and the financial legacy you want to leave. Estimate your actual financial obligations rather than choosing a coverage amount based only on a general rule.
Final Thoughts: Finding the Right Life Insurance for Seniors
Life insurance can still be an option for older adults, but choosing the right policy requires careful comparison.
If you need protection for a specific financial obligation, term insurance may be worth considering. If you want lifelong coverage, compare whole life or other permanent policies. If your main concern is funeral expenses, final expense insurance may be more appropriate.
Companies such as Guardian, New York Life, Mutual of Omaha, Pacific Life, MassMutual, and USAA are worth researching, but the best choice depends on your eligibility, location, health, and financial goals.
Before purchasing, compare several personalized quotes, review the policy conditions, and make sure the premium is affordable over the long term.
At MaintainMarket, our goal is to help readers understand financial products clearly so they can make informed decisions for themselves and their families.
Disclaimer: This article is for general educational purposes for U.S. consumers and is not individualized financial or insurance advice. Life insurance eligibility, premiums, policy features, coverage limits, and waiting periods vary by insurer, product, state, and applicant. Review the policy contract and consult a licensed insurance professional when necessary.
References
- National Association of Insurance Commissioners (NAIC) – Life Insurance
- NAIC – Consumer Life Insurance Guide
- NerdWallet – Best Life Insurance for Seniors in 2026
- CNBC Select – Best Life Insurance Companies for Seniors
- MoneyGeek – Best Term Life Insurance for Seniors
- MoneyGeek – Best Whole Life Insurance for Seniors
Editorial Review: Reviewed for U.S. consumer relevance, life insurance terminology, policy distinctions, and clarity. Company comparisons reflect published third-party research and do not guarantee availability, acceptance, or pricing.