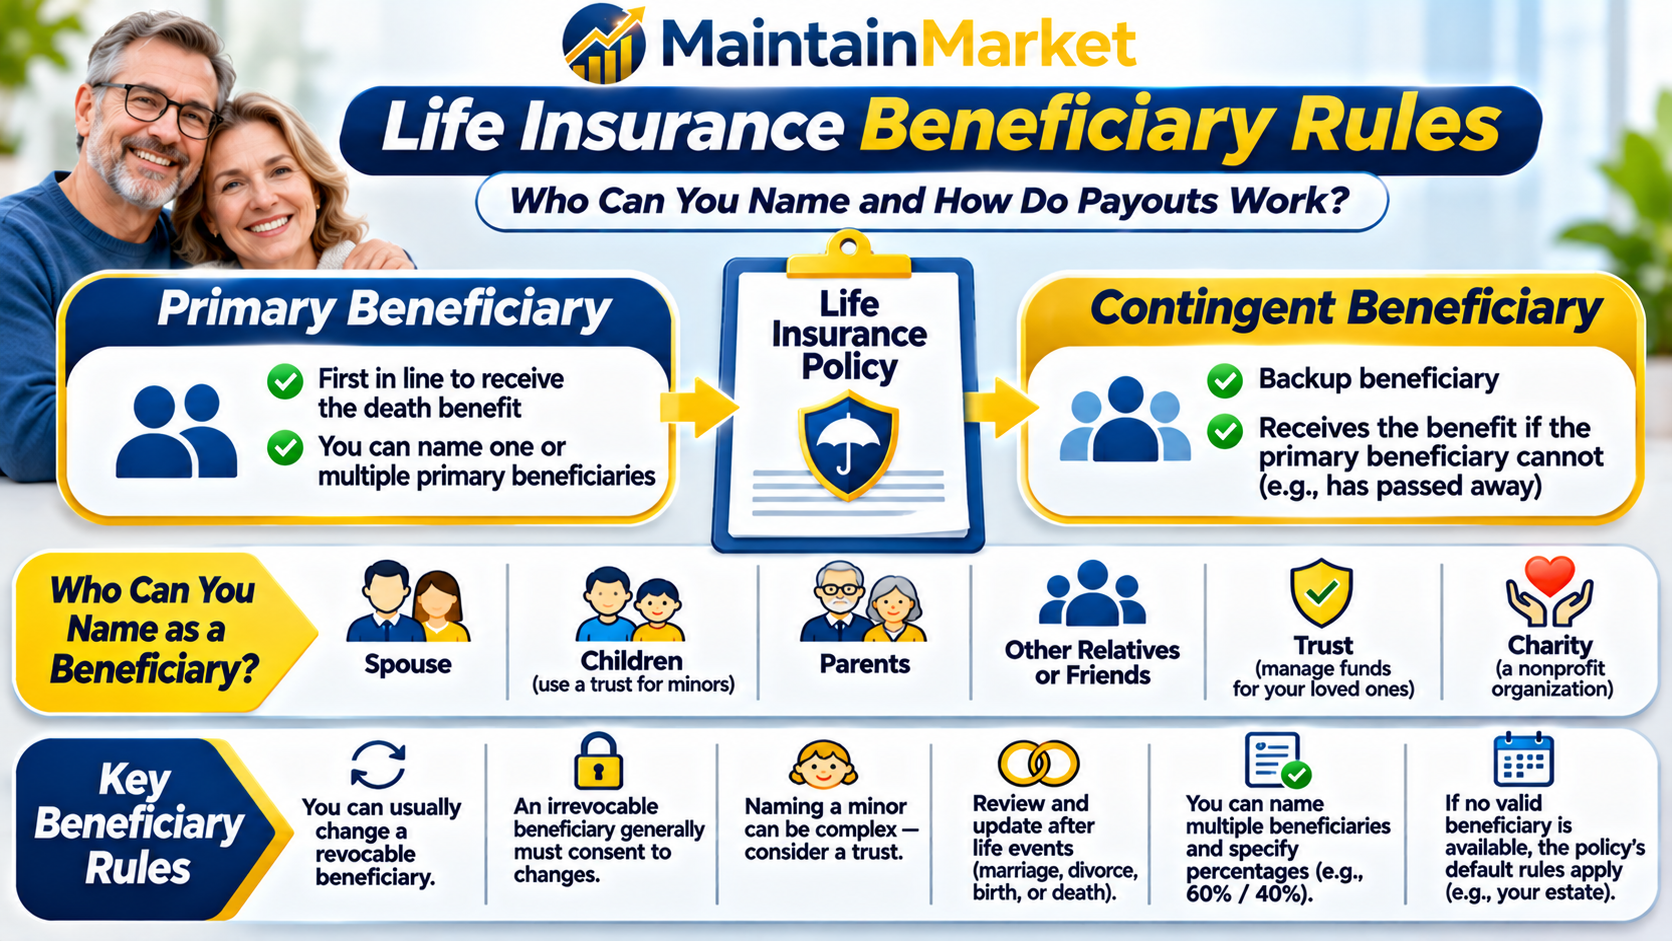
Understanding life insurance beneficiary rules is important when purchasing a policy or updating an existing one. Your beneficiary designation determines who is intended to receive the life insurance death benefit after your death, subject to the policy contract and applicable law.
In the United States, you can generally name a spouse, child, parent, relative, friend, trust, charity, or another eligible person or entity as your beneficiary. You may also name more than one beneficiary and specify how the death benefit should be divided.
However, certain situations require extra attention. Naming a minor child, getting divorced, choosing an irrevocable beneficiary, or failing to update your policy can affect how the proceeds are distributed.
This guide explains how life insurance beneficiaries work, who you can name, how to change a designation, and what happens when no named beneficiary can receive the money.
Quick Answer: What Are the Rules for Life Insurance Beneficiaries?
A life insurance beneficiary is the person or entity designated to receive the policy’s death benefit when the insured person dies.
The main rules to understand are:
- You can generally name one or multiple beneficiaries, subject to policy terms and applicable law.
- A primary beneficiary is first in line to receive the death benefit.
- A contingent beneficiary receives the benefit if the primary beneficiary cannot receive it.
- You can usually change a revocable beneficiary by following the insurer’s procedures.
- An irrevocable beneficiary generally must consent to certain changes.
- Naming a minor child directly can create legal and administrative complications.
- Divorce, marriage, births, deaths, and other family changes are reasons to review your designation.
- If no eligible beneficiary is available, the policy’s default provisions determine where the proceeds go.
Important: Beneficiary rules are not identical across every U.S. state or insurance policy. Read your policy and check applicable state law before making important changes.
What Is a Life Insurance Beneficiary?
A life insurance beneficiary is a person, trust, charity, or other eligible entity named to receive the policy’s death benefit after the insured person’s death.
For example, suppose you purchase a $500,000 life insurance policy and name your spouse as the primary beneficiary.
If you die while the policy is active and the claim is approved, the insurer generally pays the death benefit to your spouse according to the policy terms.
You can also name multiple beneficiaries and allocate specific percentages of the death benefit to each.
Example of a Beneficiary Designation
Suppose your life insurance policy has a $400,000 death benefit.
You designate:
| Beneficiary | Designation | Share |
|---|---|---|
| Spouse | Primary | 60% |
| Child 1 | Primary | 20% |
| Child 2 | Primary | 20% |
If all three beneficiaries are eligible to receive their designated shares, the proceeds would generally be divided according to those percentages.
You should make sure the percentages add up to 100% and that the policy clearly identifies each beneficiary.
Who Can You Name as a Life Insurance Beneficiary?
In many situations, you have considerable flexibility when choosing beneficiaries. The insurer’s application and policy requirements, state law, and any applicable legal agreements may affect your choices.
Common beneficiary options include:
1. Your Spouse
Many people name their spouse as their primary beneficiary.
The death benefit may help the surviving spouse manage:
- Mortgage payments
- Household expenses
- Outstanding debts
- Childcare and education costs
- Other financial responsibilities
If you name your spouse, use their full legal name rather than simply writing “my husband” or “my wife.” This can help avoid confusion after remarriage or other family changes.
Some states and certain employer-sponsored plans may have additional spousal rights or consent requirements.
2. Your Children
You can generally name your children as beneficiaries.
For example, you may allocate equal shares to two adult children or specify different percentages based on your financial and family circumstances.
However, naming a child who is under the legal age of majority can create complications when the insurer needs to pay the benefit.
A minor generally cannot manage a large insurance payout independently. Consider a properly established trust or another legally appropriate arrangement.
3. Your Parents
You may name one or both parents as beneficiaries.
This may be suitable if you financially support your parents or want to provide funds for their living expenses after your death.
Clearly identify each parent by their full legal name and specify the percentage each should receive.
4. Other Family Members or Friends
Depending on the policy and applicable law, you may name siblings, grandchildren, relatives, or friends.
You do not necessarily have to choose a family member. However, provide accurate identifying information so the insurer can locate and verify the beneficiary.
5. A Trust
A trust can receive life insurance proceeds and hold or distribute the money according to its terms.
This may be useful when:
- Your beneficiaries are minor children.
- You want to control when beneficiaries receive money.
- A beneficiary needs ongoing financial support.
- You have specific estate-planning objectives.
Trust arrangements should be established carefully with qualified legal and tax advice.
6. A Charity or Organization
You may be able to name an eligible nonprofit organization or charity as a beneficiary.
This can allow your policy to provide financial support to an organization after your death.
Confirm the organization’s exact legal name and required identifying information with the insurer.
Primary vs. Contingent Beneficiary: What Is the Difference?
Life insurance policies commonly allow you to designate primary and contingent beneficiaries.
Understanding the difference helps prevent problems if someone named in your policy dies before you.
Primary Beneficiary
A primary beneficiary is the first person or entity designated to receive the death benefit.
You may name one or multiple primary beneficiaries.
For example:
- Spouse: 70%
- Child: 30%
If both beneficiaries survive the insured and are eligible, the insurer generally distributes the proceeds according to the stated shares.
Contingent Beneficiary
A contingent beneficiary is a backup beneficiary.
This person or entity generally receives the death benefit if the primary beneficiary has died before the insured, cannot receive the proceeds, or otherwise meets the conditions for the contingent designation to take effect.
For example:
| Beneficiary | Role |
|---|---|
| Spouse | Primary beneficiary |
| Two adult children | Contingent beneficiaries |
If your spouse dies before you and the contingent beneficiaries are eligible under the policy, your children may receive the death benefit.
Primary vs. Contingent Beneficiary Comparison
| Feature | Primary beneficiary | Contingent beneficiary |
|---|---|---|
| Position | First in line | Backup |
| Receives proceeds | If eligible under the policy | If the primary beneficiary cannot receive them |
| Can name multiple people? | Generally yes | Generally yes |
| Percentage allocation | Can be specified | Can be specified |
Practical tip: Naming contingent beneficiaries can help prevent your policy from being left without an available named recipient if your original beneficiary dies before you.
What Is the Difference Between Revocable and Irrevocable Beneficiaries?
Another important part of life insurance beneficiary rules is whether the designation is revocable or irrevocable.
Revocable Beneficiary
A revocable beneficiary is someone you can generally change or remove without obtaining that beneficiary’s consent, subject to the policy and applicable law.
For example, if you name your spouse as a revocable beneficiary, you may generally be able to update the designation after a divorce or other major family change.
You must still follow the insurer’s required procedures.
Irrevocable Beneficiary
An irrevocable beneficiary has stronger rights under the policy.
You generally cannot remove or change an irrevocable beneficiary without their written consent or another legally permitted basis.
Depending on the contract, consent may also be required for certain policy changes, assignments, or other transactions affecting their rights.
Revocable vs. Irrevocable Beneficiary
| Feature | Revocable | Irrevocable |
|---|---|---|
| Can the policyholder generally change the designation? | Yes | Usually requires consent |
| Beneficiary consent required? | Generally no | Generally yes |
| Flexibility | Greater | More limited |
| Common consideration | Personal and family planning | Legal agreements or specific financial arrangements |
Before naming an irrevocable beneficiary, understand the long-term consequences. Changing family circumstances may not give you the freedom to update the policy without consent.
Can You Name a Minor Child as a Life Insurance Beneficiary?
You may be able to name a minor child as a beneficiary, but doing so directly can create complications.
Insurance companies generally cannot simply hand a large death benefit to a child who is legally unable to manage the funds.
Depending on state law and the policy, a court-appointed guardian or another legally authorized arrangement may be required.
This can delay access to the money and create additional administrative costs.
What Are Your Options?
Option 1: Establish a Trust
You can create a trust and name it as the life insurance beneficiary.
A trustee manages the money according to the trust document and uses it for the child’s benefit.
You can specify when and how the child receives the money, subject to the trust’s terms.
Option 2: Consider a Custodial Arrangement
Depending on state law, a custodial account under the Uniform Transfers to Minors Act (UTMA) may be an option.
A custodian manages the assets for the child until the applicable transfer age.
Option 3: Obtain Legal Advice
An estate-planning attorney can help determine the most appropriate structure based on your state, family circumstances, and financial goals.
Important: Naming a trusted adult as beneficiary instead of a child is not automatically the same as creating a legal obligation for that adult to use the money for the child. Choose the arrangement carefully.
What Happens to Life Insurance Beneficiaries After Divorce?
Divorce can create important beneficiary issues.
Suppose you purchased a life insurance policy while married and named your spouse as the primary beneficiary. You later divorce but never update the policy.
The original designation may still appear in the insurer’s records.
Whether the former spouse can receive the death benefit depends on several factors, including:
- State law
- The policy contract
- Whether the policy is individually owned or employer-sponsored
- The divorce decree or settlement agreement
- Any court order requiring life insurance coverage
- Whether the beneficiary designation was formally changed
Some states have laws that may revoke certain beneficiary designations after divorce. However, these laws do not apply identically everywhere, and federal law may affect certain employer-sponsored plans.
What Should You Do After Divorce?
- Review your existing life insurance policies.
- Check who is currently listed as primary and contingent beneficiary.
- Review your divorce decree and settlement agreement.
- Check whether a court order requires you to maintain coverage for a former spouse or children.
- Contact the insurer about changing the designation.
- Obtain legal advice if the policy is connected to a divorce settlement or court order.
Do not assume that a divorce automatically removes a former spouse from every life insurance policy.
Can You Change Your Life Insurance Beneficiary?
In many cases, yes.
If your beneficiary designation is revocable, you can generally change it by submitting the required information to your insurance company.
However, the procedure depends on the insurer and policy.
How to Change a Life Insurance Beneficiary
Follow these general steps:
Step 1: Review Your Current Policy
Find your current beneficiary designation and check whether it is revocable or irrevocable.
Step 2: Contact Your Insurance Company
Ask for its beneficiary change form or access the relevant policy-management service.
Step 3: Provide Updated Information
You may need to provide:
- Beneficiary’s full legal name
- Relationship to the insured
- Date of birth
- Address and contact information
- Percentage of the death benefit
- Other identifying details requested by the insurer
Step 4: Submit the Required Form
Follow the insurer’s instructions. Some insurers accept electronic submissions, while others require signed documents.
Step 5: Confirm the Change
Request confirmation that the new designation has been received and recorded.
Do not assume that writing a new beneficiary in your personal records or will automatically updates your insurance policy.
What Happens If You Do Not Name a Life Insurance Beneficiary?
If you do not name a beneficiary, or no named beneficiary survives you, the insurer will generally follow the policy’s default beneficiary provisions.
Depending on the contract, the proceeds may be payable to:
- A surviving spouse
- Children or other specified relatives
- Your estate
- Another recipient identified in the policy
There is no universal default order that applies to every life insurance policy.
Does Life Insurance Go Through Probate?
If the death benefit is payable directly to a valid named beneficiary, it generally passes outside the insured person’s probate estate.
However, if the proceeds are payable to the estate under the policy, they may become part of the probate process.
Probate requirements vary by state and by the circumstances of the estate.
Review your policy’s default provisions so you understand what happens if your named beneficiaries cannot receive the benefit.
What Happens If a Beneficiary Dies Before the Policyholder?
If your primary beneficiary dies before you, the insurer generally looks at the remaining beneficiary designations and the policy’s terms.
Possible outcomes include:
- A surviving co-beneficiary receives their designated share.
- A contingent beneficiary receives the proceeds.
- The policy’s default provisions determine the recipient.
- A specific distribution method in the policy or designation applies.
The result may depend on whether you selected a per stirpes or per capita distribution arrangement, if the insurer and applicable law permit those designations.
What Does Per Stirpes Mean?
Per stirpes generally means that a deceased beneficiary’s share passes down that person’s family branch to eligible descendants.
For example, suppose you name two children as beneficiaries in equal shares.
If one child dies before you and has two children of their own, a per stirpes arrangement may allow those grandchildren to share their parent’s portion.
What Does Per Capita Mean?
Per capita generally means that eligible surviving beneficiaries receive equal shares at the applicable distribution level.
Under some per capita arrangements, a deceased beneficiary’s descendants may not automatically receive that person’s share.
The exact result depends on the designation language, policy, and applicable law. Ask the insurer or an estate-planning attorney how the wording will operate before submitting it.
How Are Life Insurance Death Benefits Paid to Beneficiaries?
After the insured person dies, the beneficiary generally needs to contact the insurance company and submit a claim.
The insurer will review the policy and required documents before paying an approved claim.
Common Documents Required
A beneficiary may be asked to provide:
- Completed claim form
- Certified death certificate
- Policy number or identifying policy information
- Government-issued identification
- Proof of relationship or other information, if required
- Additional documents requested by the insurer
The insurer’s requirements vary depending on the policy and claim circumstances.
How Long Does It Take to Receive Life Insurance Money?
There is no single payment timeline for every claim.
Processing time depends on factors such as:
- Whether the policy is active
- Whether the claim form is complete
- Whether the insurer needs additional documents
- Whether beneficiary identity can be verified
- Whether the claim requires further investigation
- State insurance laws and applicable claim-handling requirements
A straightforward, complete claim may be processed more quickly than one involving missing documents or a disputed beneficiary designation.
If payment is delayed, contact the insurer and ask what information is still required.
Are Life Insurance Beneficiary Payouts Taxable?
Generally, life insurance proceeds paid to a beneficiary because of the insured person’s death are not included in the beneficiary’s federal gross income.
However, certain exceptions and additional tax considerations may apply.
For example:
- Interest paid on delayed or installment proceeds may be taxable.
- Certain policy transfers for valuable consideration can affect the income-tax exclusion.
- Large life insurance policies may raise separate federal estate-tax questions depending on ownership and estate circumstances.
Important distinction: Income-tax treatment and estate-tax treatment are different issues. A death benefit may generally be income-tax-free to the beneficiary but still need to be considered in an estate-tax analysis in some circumstances.
For more information, review the IRS guidance on life insurance proceeds.
Common Life Insurance Beneficiary Mistakes to Avoid
1. Naming Only One Beneficiary
If your only beneficiary dies before you, the policy’s default provisions may determine who receives the money.
Consider naming contingent beneficiaries.
2. Forgetting to Update Your Policy After Major Life Changes
Marriage, divorce, births, adoptions, and deaths can change your intentions.
Review your beneficiary designation after these events.
3. Naming Minor Children Without a Legal Arrangement
A minor may not be able to receive and manage the money directly.
Consider a trust or another appropriate arrangement with legal guidance.
4. Forgetting to Allocate Percentages
If you name multiple beneficiaries, clearly state how the death benefit should be divided.
Check that the percentages total 100%.
5. Assuming Your Will Automatically Overrides the Policy
A life insurance beneficiary designation generally controls who receives the proceeds, subject to applicable law and policy terms.
A will does not automatically replace or update the insurer’s beneficiary records.
6. Ignoring an Irrevocable Designation
An irrevocable beneficiary may have rights that limit your ability to make changes.
Understand these rights before making the designation.
7. Failing to Keep Confirmation of Changes
Keep a copy of the completed form and the insurer’s confirmation.
This can help resolve questions about which designation was recorded.
Life Insurance Beneficiary Checklist
Use this checklist when purchasing a policy or reviewing an existing one.
- Confirm the policyholder and insured person’s details.
- Name a primary beneficiary.
- Name contingent beneficiaries where appropriate.
- Use full legal names and accurate identifying information.
- Allocate clear percentages if naming multiple beneficiaries.
- Check whether the designation is revocable or irrevocable.
- Consider a trust or custodial arrangement for minor children.
- Review divorce agreements and court orders where relevant.
- Understand the policy’s default beneficiary provisions.
- Obtain written confirmation of any changes.
- Review the designation after major family changes.
Frequently Asked Questions
1. Who can be named as a life insurance beneficiary?
Depending on the policy and applicable law, you may be able to name a spouse, child, parent, relative, friend, trust, charity, or another eligible entity. Check the insurer’s requirements before submitting your designation.
2. Can I have more than one life insurance beneficiary?
Yes. Many policies allow multiple primary and contingent beneficiaries. You can generally specify the percentage of the death benefit each should receive.
3. Can a life insurance beneficiary be changed?
A revocable beneficiary can generally be changed by following the insurer’s procedures. An irrevocable beneficiary usually has to consent to certain changes.
4. Does a spouse automatically receive life insurance money?
Not necessarily. The person named in the beneficiary designation generally receives the proceeds, subject to the policy, state law, and applicable legal agreements. Some policies and jurisdictions have additional spousal protections or consent requirements.
5. Can I name my child as a life insurance beneficiary?
You may be able to name your child, but naming a minor directly can create payment and management complications. A trust or other legally appropriate arrangement may be worth considering.
6. Does divorce automatically remove an ex-spouse as a beneficiary?
Not in every situation. State law, federal law, the policy type, divorce agreements, and court orders can affect the outcome. Review the policy and obtain legal advice when necessary.
7. What happens if my primary beneficiary dies before me?
The insurer generally checks for surviving primary beneficiaries, contingent beneficiaries, and any default provisions in the policy. The result depends on the designation and contract.
8. What happens if I do not name a beneficiary?
The insurer generally follows the policy’s default provisions. The proceeds may become payable to a person identified by the contract or to your estate.
9. Are life insurance payouts taxable to beneficiaries?
Death benefits are generally excluded from federal gross income. However, interest on proceeds may be taxable, and separate estate-tax or transfer-for-value rules may apply in certain circumstances.
10. Does a will override a life insurance beneficiary?
A will generally does not automatically override a valid beneficiary designation recorded with the insurer. If you want to change the recipient, follow the insurer’s beneficiary-change process and obtain legal advice if necessary.
Final Thoughts: Review Your Life Insurance Beneficiary Designation Regularly
Choosing a life insurance beneficiary is an important part of protecting your family’s financial future. The person or entity you name determines who is intended to receive the policy’s death benefit, subject to the contract and applicable law.
Name primary and contingent beneficiaries, provide accurate information, and consider the needs of minor children. Review your designation after marriage, divorce, births, deaths, or other major changes.
Most importantly, do not assume your will or family circumstances automatically update your insurance policy. Confirm any changes directly with your insurer and keep written records.
At Maintain Market, our goal is to make insurance and personal finance easier to understand so you can make informed decisions for yourself and your loved ones.
Disclaimer: This article provides general educational information for U.S. consumers and is not individualized legal, tax, estate-planning, or insurance advice. Beneficiary rights and payout rules can vary by state, policy contract, ownership structure, and applicable federal law. Consult a qualified attorney, tax professional, or licensed insurance professional about your circumstances.
References
- National Association of Insurance Commissioners (NAIC) – Life Insurance Consumer Information
- Iowa Department of Administrative Services – Beneficiary Designation FAQs
- Internal Revenue Service – Life Insurance and Disability Insurance Proceeds
- IRS Publication 525 – Taxable and Nontaxable Income
- American Bar Association – Beneficiary Designations in Estate Plans
Editorial Review: Reviewed for U.S. consumer relevance, beneficiary terminology, and general policy considerations. State laws, employer-sponsored plan rules, and insurance contracts may produce different outcomes.