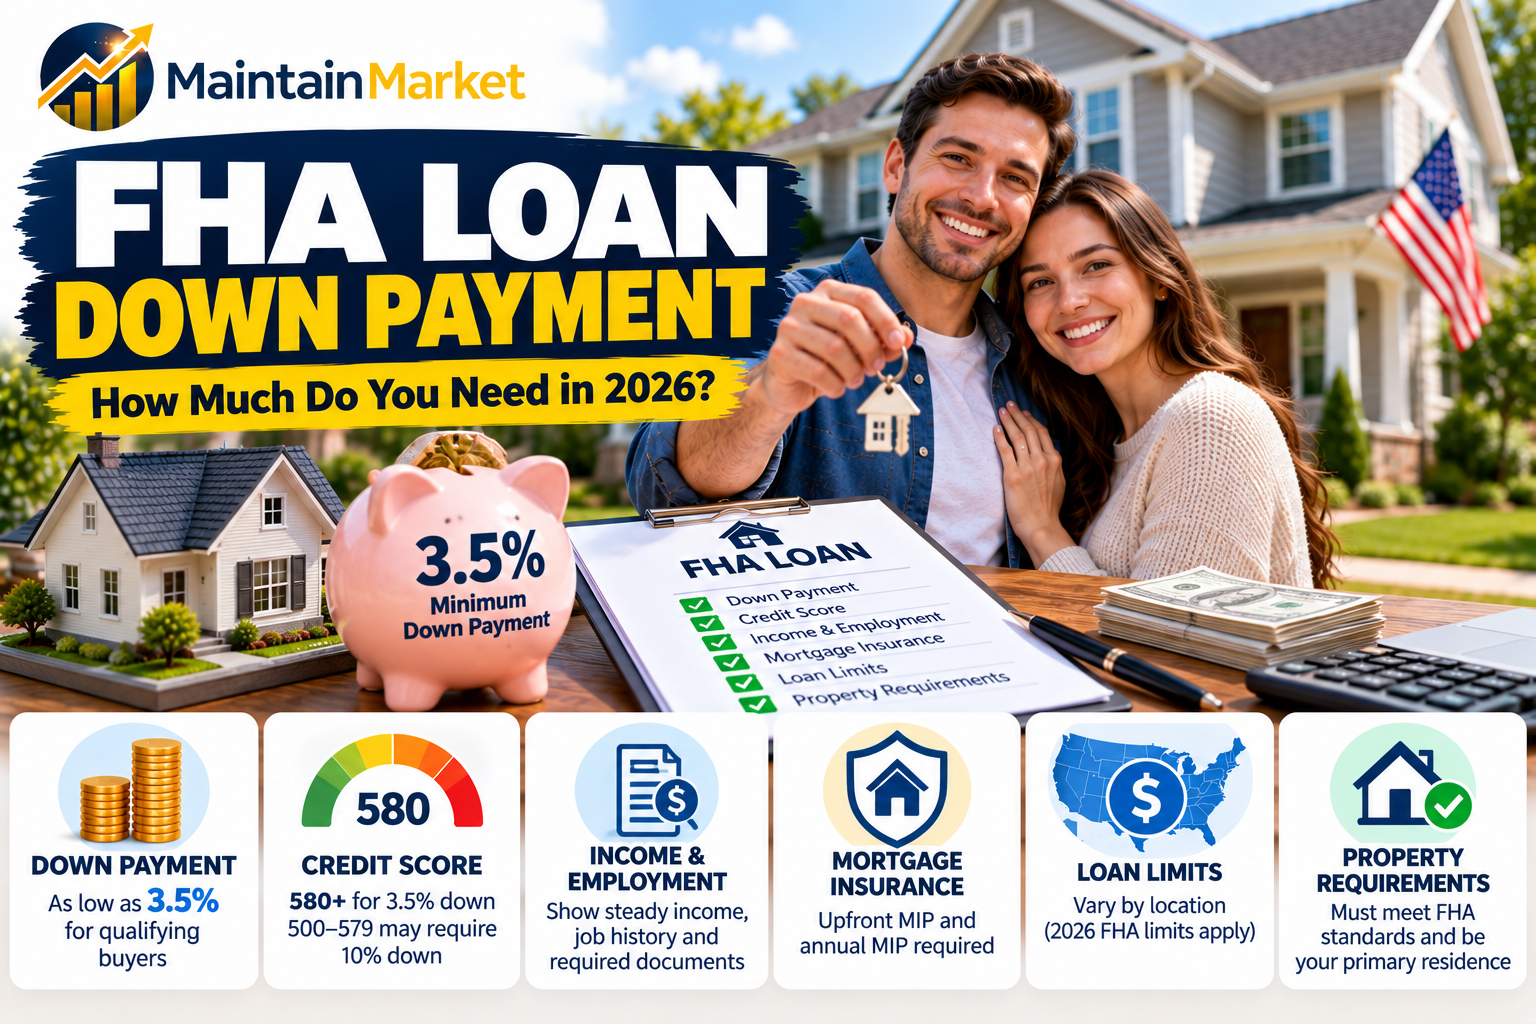
If you’re considering an FHA mortgage, understanding the FHA loan down payment is one of the first things you should know. For eligible borrowers, the minimum required investment can be as low as 3.5% of the property’s adjusted value, although the amount you need can change based on your credit profile, property price, and available assistance.
1. What Is the Minimum FHA Loan Down Payment?
For many FHA borrowers, the minimum required investment is 3.5%.
For example:
| Home Price | 3.5% Down Payment |
|---|---|
| $150,000 | $5,250 |
| $200,000 | $7,000 |
| $250,000 | $8,750 |
| $300,000 | $10,500 |
| $350,000 | $12,250 |
| $400,000 | $14,000 |
| $500,000 | $17,500 |
The 3.5% figure is the minimum required investment for borrowers who meet the applicable FHA requirements. FHA loans are made by private lenders and insured by the Federal Housing Administration.
2. Do You Always Need Only 3.5% Down?
No.
The 3.5% minimum is not a guarantee that every borrower will qualify for that down payment.
Your lender can consider factors such as:
- Credit history
- Credit score
- Income
- Employment history
- Existing debts
- Debt-to-income ratio
- Property value
- Loan limits
- FHA property requirements
A borrower may also choose to put more than 3.5% down.
For example, someone purchasing a $300,000 home could potentially put down:
- 3.5%: $10,500
- 5%: $15,000
- 10%: $30,000
- 20%: $60,000
A larger down payment reduces the amount borrowed, but it also means using more cash upfront.
3. What Credit Score Do You Need for a 3.5% FHA Down Payment?
FHA’s credit framework generally allows borrowers with a qualifying credit score of 580 or higher to use the 3.5% minimum required investment.
Borrowers with scores between 500 and 579 may generally need a 10% minimum required investment.
That means a $250,000 home could look like this:
| Credit situation | Example minimum investment |
|---|---|
| 580+ | $8,750 at 3.5% |
| 500–579 | $25,000 at 10% |
Your lender may also apply its own underwriting requirements, so meeting the FHA minimum does not automatically mean approval.
4. Can Gift Money Be Used for an FHA Down Payment?
Potentially, yes.
FHA rules allow certain acceptable sources of funds, including eligible gift funds, subject to documentation and other requirements.
Depending on the circumstances, an acceptable donor can include:
- A family member
- An employer or labor union
- Certain charitable organizations
- Certain governmental or public entities
- Other eligible sources permitted under FHA rules
The gift generally needs to be properly documented. The lender may require a gift letter and evidence showing the transfer of funds.
Important: Don’t assume that money from any person can automatically be used for an FHA down payment. The source must meet FHA and lender requirements.
5. Can Down Payment Assistance Help With an FHA Loan?
Yes, potentially.
Some borrowers may qualify for down-payment assistance programs that can help with the required cash investment.
Assistance programs can vary significantly by:
- State
- County
- City
- Income
- First-time buyer status
- Property location
- Household circumstances
- Program rules
Some assistance may come through grants, secondary financing, or other approved structures.
Before relying on assistance, confirm that the specific program is compatible with your FHA transaction and that you meet its eligibility requirements.
6. Your Down Payment Is Not the Same as Your Total Cash Needed
This is one of the biggest mistakes first-time homebuyers make.
Suppose you purchase a $300,000 home and qualify for the 3.5% minimum investment.
Your minimum down payment would be:
$300,000 × 3.5% = $10,500
But you may still need money for other expenses, such as:
- Closing costs
- Prepaid property taxes
- Homeowners insurance
- Initial escrow funding
- Inspections
- Appraisal
- Other transaction expenses
So having $10,500 does not necessarily mean you have enough cash to close.
Ask your lender for an estimate of your total cash needed to close, rather than focusing only on the down payment.
7. Can You Put 10% or 20% Down on an FHA Loan?
Yes.
You are not required to stop at 3.5%.
For a $300,000 home:
3.5%: $10,500
10%: $30,000
20%: $60,000
A larger down payment means borrowing less money.
However, putting more money down isn’t automatically better for every borrower. You should consider how much cash you will have left after closing for:
- Emergency savings
- Moving expenses
- Repairs
- Furniture
- Home maintenance
- Other financial needs
The right amount depends on your overall financial situation.
8. Does a Larger FHA Down Payment Reduce Your Monthly Payment?
Generally, borrowing less means having a smaller principal balance, which can reduce the principal-and-interest portion of the monthly mortgage payment.
For example:
$300,000 home
With 3.5% down:
- Down payment = $10,500
- Approximate base loan amount = $289,500
With 10% down:
- Down payment = $30,000
- Approximate base loan amount = $270,000
The actual FHA mortgage payment can also include mortgage insurance, taxes, homeowners insurance and other costs.
So don’t compare FHA loans using only the down payment. Look at the complete monthly payment and total borrowing cost.
9. Can You Buy a Home With No Down Payment Using an FHA Loan?
A standard FHA loan is generally associated with a minimum required investment of 3.5%, so it is not normally a true zero-down-payment mortgage.
However, eligible borrowers may be able to use permitted sources such as:
- Gift funds
- Down-payment assistance
- Secondary financing that complies with FHA rules
That can reduce the amount of the buyer’s own cash needed.
This is different from saying that FHA itself requires zero dollars down.
10. What Should You Save Before Applying for an FHA Mortgage?
Don’t save only for the down payment.
A practical FHA homebuying savings plan should account for:
Down payment
Start with the required investment based on your expected purchase price.
Closing costs
Ask lenders for a Loan Estimate so you can see expected transaction costs.
Emergency savings
Try not to use every dollar you have to purchase the home.
Moving costs
Transportation, furniture and setup costs can add up quickly.
Repairs and maintenance
Even a home that looks move-in ready can require unexpected expenses.
Homeowners insurance
Your lender will generally want evidence of appropriate property insurance.
Taxes and escrow
Depending on the transaction, you may need money for prepaid or escrowed expenses.
FHA Loan Down Payment Example
Imagine you’re buying a $350,000 home.
At 3.5%:
$350,000 × 0.035 = $12,250
So the minimum required investment would be approximately $12,250, assuming you qualify for the 3.5% FHA structure and the applicable value used for the calculation supports that amount.
But your total cash requirement could be higher because of closing costs and other prepaid expenses.
This is why a buyer should ask:
“How much total cash will I need to close?”
rather than only:
“How much is the FHA down payment?”
FHA Down Payment vs. Conventional Down Payment
| Feature | FHA Loan | Conventional Loan |
|---|---|---|
| Potential minimum down payment | 3.5% for qualifying borrowers | Can be as low as 3% for some programs |
| Mortgage insurance | FHA mortgage insurance generally required | Private mortgage insurance may apply depending on down payment |
| Credit requirements | FHA can accommodate some lower-credit borrowers | Requirements vary by lender/program |
| Down-payment assistance | May be available depending on program | May be available depending on program |
| Loan limits | Vary by location | Vary by program/location |
| Property requirements | FHA standards apply | Conventional lender/program requirements apply |
The lowest possible down payment should not be the only factor you compare. Look at the interest rate, mortgage insurance, closing costs, monthly payment and total loan cost.
5 Common FHA Down Payment Mistakes
1. Saving only 3.5%
The minimum down payment isn’t necessarily the total amount you’ll need to close.
2. Forgetting closing costs
Your transaction can involve several expenses beyond the down payment.
3. Assuming any gift money is acceptable
Gift funds must meet applicable FHA and lender requirements.
4. Using all your savings
Buying a home can create unexpected expenses. Keeping an emergency reserve can be important.
5. Assuming 3.5% guarantees approval
Your lender still evaluates your income, debts, credit history, property and other requirements.
FHA Loan Down Payment Checklist
Before making an offer, consider having these items ready:
- Estimated home price
- 3.5% down-payment calculation
- Credit report
- Proof of income
- Employment information
- Bank statements
- Estimated closing costs
- Emergency savings
- Gift-fund documentation if applicable
- Down-payment assistance research
- Preapproval from an FHA-approved lender
Frequently Asked Questions
How much is the minimum FHA loan down payment?
For qualifying borrowers, the minimum required investment can be 3.5%. Your eligibility depends on FHA requirements and your lender’s underwriting.
Can I put 5% down on an FHA loan?
Yes. The FHA minimum is not a maximum. A borrower can generally choose to make a larger down payment if they have the funds and meet the lender’s requirements.
Can I use gift money for my FHA down payment?
Potentially. FHA permits certain eligible gift funds when the source and transfer are properly documented and meet applicable requirements.
Can FHA loans have a 0% down payment?
A standard FHA loan generally requires a minimum required investment, commonly 3.5% for qualifying borrowers. However, eligible assistance or other permitted funding sources may help cover that investment.
Is 10% down better than 3.5% on an FHA loan?
A larger down payment means borrowing less, but it also uses more cash upfront. The appropriate choice depends on the buyer’s overall finances, monthly payment, reserves and other costs.
Does FHA require mortgage insurance?
Yes. FHA loans generally require mortgage insurance, which adds to the cost of the loan. The exact structure and cost depend on the applicable FHA rules and loan circumstances.
Final Takeaway
The FHA loan down payment can be as low as 3.5% for qualifying borrowers, making FHA financing an option for buyers who may not have a large amount of cash available upfront.
But don’t stop your calculation at 3.5%. Consider closing costs, mortgage insurance, prepaid expenses, emergency savings and your total cash needed to close before deciding how much to put down.
The best starting point is to get an FHA loan estimate from a lender and compare the total cost of the mortgage, not just the initial down payment.
Why Maintain Market Is Different
Maintain Market focuses on breaking down complicated financial topics into practical information that everyday U.S. consumers can understand.
For mortgage topics, we separate the minimum requirement from the actual cash a buyer may need, helping readers understand the difference between qualifying for a loan and being financially prepared to close.
References
- CFPB — FHA Loans
- HUD — FHA Single Family Housing Policy Handbook 4000.1
- HUD — National Homeownership Month / FHA Resources
Editorial Review
Reviewed for clarity, U.S. mortgage terminology, FHA down-payment concepts, and distinction between the FHA minimum required investment and other homebuying costs.