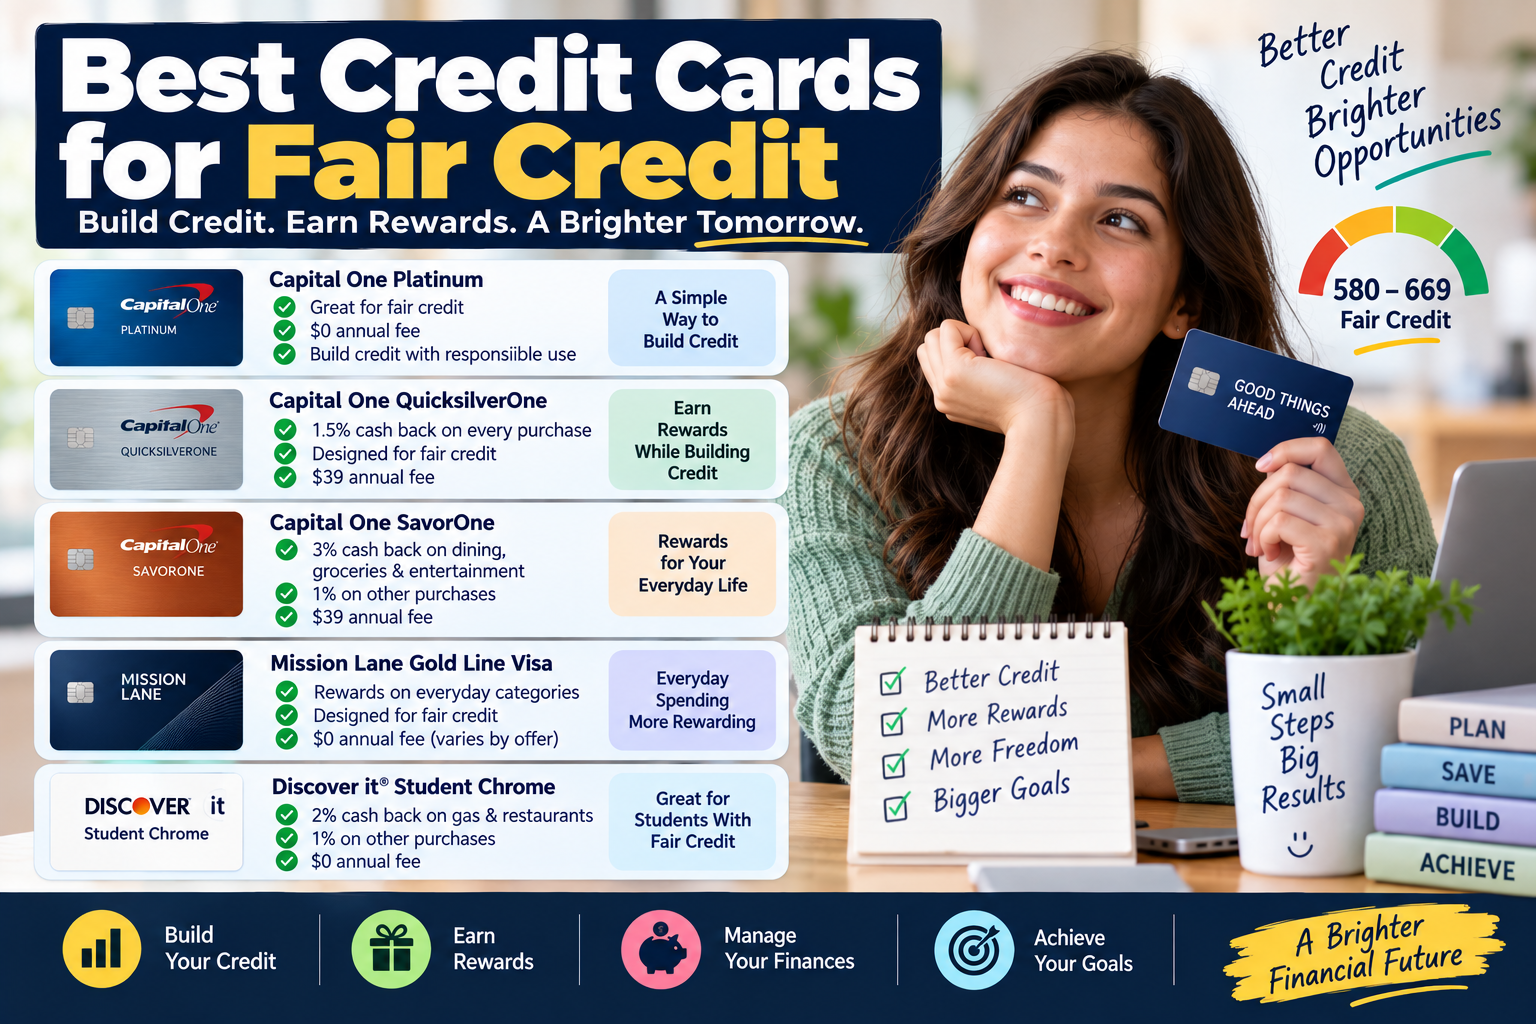
Finding the best credit cards for fair credit can be easier than you might think. If your FICO® Score is generally between 580 and 669, you may qualify for several credit cards designed for fair or average credit, including cards that offer cash back, no annual fee, or tools to help you continue building your credit.
The key is choosing a card that matches your current credit profile rather than applying for cards designed primarily for good or excellent credit.
Quick Answer: What Are the Best Credit Cards for Fair Credit?
Some of the strongest options to research in 2026 include Capital One Platinum, Capital One QuicksilverOne, Capital One SavorOne, Mission Lane Gold Line Visa, AvantCard, Credit One Bank Wander, and selected Discover student cards.
| Credit Card | Best For | Annual Fee | Main Benefit |
|---|---|---|---|
| Capital One Platinum | Simple credit building | $0 | No annual fee |
| Capital One QuicksilverOne | Flat-rate cash back | $39 | 1.5% cash back |
| Capital One SavorOne | Dining & entertainment | $39 | 3% cash back in select categories |
| Mission Lane Gold Line Visa | Rewards on everyday categories | $0 | Cash back on selected spending |
| AvantCard | Credit-building accessibility | Varies | Designed for credit builders |
| Credit One Bank Wander | Travel rewards | Varies | Rewards on travel-related spending |
| Discover it® Student Chrome | Eligible students | $0 | Cash back on gas and restaurants |
| Secured credit card | Applicants needing another path | Varies | Deposit-backed credit line |
Card availability, approval criteria, annual fees, APRs, rewards and other terms can change. Always check the issuer’s current terms before applying.
1. Capital One Platinum — Best for Simple Credit Building
Capital One Platinum is one of the simplest cards to consider if you have fair credit and don’t need a complicated rewards structure.
Capital One currently lists the Platinum card under its fair-credit options and shows a $0 annual fee. The card is positioned around building credit through responsible use.
Why consider it?
- $0 annual fee
- Designed for fair credit
- Simple card structure
- No rewards program to manage
- Useful if your priority is improving your credit profile
This can be a good choice if you’re more interested in building credit than maximizing rewards.
2. Capital One QuicksilverOne — Best for Flat-Rate Cash Back
If you want to earn cash back while working on your credit, Capital One QuicksilverOne is worth comparing.
Capital One currently lists QuicksilverOne as a fair-credit card with a $39 annual fee and 1.5% cash back on every purchase. Capital One also describes QuicksilverOne as suitable for credit builders and people with fair credit.
Why consider it?
- 1.5% cash back on purchases
- Designed for fair credit
- No rotating bonus categories
- Can combine everyday spending with credit-building
Watch out for:
The $39 annual fee matters. If you don’t spend enough to earn meaningful rewards, a $0-annual-fee card could be a better fit.
3. Capital One SavorOne — Best for Dining and Entertainment
Capital One SavorOne is another fair-credit option for consumers who spend heavily on dining, entertainment and groceries.
Capital One currently lists SavorOne under its fair-credit cards, with a $39 annual fee and 3% cash back at grocery stores, dining and entertainment, plus 1% on other purchases.
Why consider it?
- 3% cash back in selected categories
- Designed for fair credit
- Useful for frequent dining and entertainment spending
- Can help combine rewards with responsible credit use
Before applying, compare the annual fee with the rewards you realistically expect to earn.
4. Mission Lane Gold Line Visa — Best for Everyday Category Rewards
The Mission Lane Gold Line Visa is another card currently appearing among leading fair-credit options.
NerdWallet’s September 2026 fair-credit review identifies it as a strong option for gas, dining and travel rewards, noting that Mission Lane markets it toward consumers with fair or average credit.
Why consider it?
- Designed for consumers with fair or average credit
- Rewards on common spending categories
- No annual fee according to current market listings
- Potential credit-limit reviews
Because issuer terms can vary, check the specific offer you’re shown before accepting it.
5. AvantCard — Best for Credit-Building Accessibility
AvantCard is another option that appears in current fair-credit card comparisons.
It can be worth considering if your priority is finding a card designed for consumers who may not qualify for premium rewards cards.
Why consider it?
- Focused on credit building
- Designed for consumers with less-than-good credit
- May provide another option when mainstream rewards cards aren’t realistic
The important thing is to compare the actual offer you receive, especially the annual fee, APR and other account costs.
6. Credit One Bank Wander — Best for Travel Rewards
If travel rewards matter to you, Credit One Bank Wander can be another card to investigate.
Current fair-credit comparisons list the Wander card among options for consumers looking for travel rewards.
Why consider it?
- Travel-oriented rewards
- Can be useful for frequent travelers
- May be accessible to some applicants with fair credit
However, travel rewards shouldn’t automatically make a card a good deal. Always compare the annual fee, APR and reward structure against your actual spending.
7. Discover it® Student Chrome — Best for Students With Fair Credit
College students with fair credit may have access to student-oriented credit cards that offer rewards while helping establish stronger credit habits.
Discover’s current Student Chrome card offers 2% cash back at gas stations and restaurants on up to $1,000 in combined purchases each quarter, plus 1% cash back on other purchases, with no annual fee.
Why consider it?
- $0 annual fee
- Student-focused
- Cash back on gas and restaurants
- Can be useful for eligible students building credit
Student eligibility requirements still apply, and approval isn’t guaranteed.
8. A Secured Credit Card — Best Alternative When Approval Is Difficult
If your fair credit is near the lower end of the range or your credit history contains negative information, a secured card can be another option.
Unlike a traditional unsecured card, a secured credit card generally requires a refundable security deposit that supports the credit line.
Why consider it?
- Can provide another route to building credit
- Deposit can reduce the issuer’s risk
- Some secured cards have no annual fee
- Some issuers may eventually return the deposit or allow an upgrade
A secured card isn’t necessarily your first choice if you qualify for a good unsecured card, but it can be useful when your approval options are limited.
What Is Considered Fair Credit?
According to FICO®, 580 to 669 is generally considered a fair credit score range.
FICO categorizes scores as:
| FICO Score | Category |
|---|---|
| 300–579 | Poor |
| 580–669 | Fair |
| 670–739 | Good |
| 740–799 | Very Good |
| 800–850 | Exceptional |
Different scoring models can use different ranges. For example, VantageScore uses somewhat different terminology and ranges.
Your credit score is only one factor a card issuer can consider. Income, payment history, existing debt, credit history and other information may also affect an approval decision.
Fair Credit vs. No Credit vs. Bad Credit
These terms are often confused.
| Credit Profile | What It Usually Means | Cards to Consider |
|---|---|---|
| No credit | Little or no established credit history | Student or secured cards |
| Fair credit | Established history with a mid-range score | Fair-credit unsecured cards |
| Bad credit | Significant negative credit history | Secured or credit-building cards |
| Good credit | Stronger established credit | Broader rewards-card selection |
| Excellent credit | Very strong credit profile | Premium rewards cards |
This distinction matters because a person with fair credit may qualify for products that aren’t realistic for someone with severely damaged credit.
How to Choose the Best Credit Card for Fair Credit
Don’t choose based solely on the phrase “easy approval.”
Consider these factors first.
1. Annual Fee
A card with a $0 annual fee can be attractive when you’re rebuilding or improving your credit.
If a card charges an annual fee, make sure its rewards or benefits justify the cost.
2. APR
Fair-credit cards can have relatively high APRs.
If you expect to carry a balance, interest costs can quickly outweigh cash-back rewards.
3. Rewards
Look at where you actually spend money.
For example, a dining-focused card may be useful if you frequently eat out, while a flat-rate cash-back card may be simpler for someone whose spending is spread across many categories.
4. Credit-Building Features
Look for issuers that report account activity to the major credit bureaus and offer tools that help you manage your account responsibly.
5. Prequalification
If an issuer offers a prequalification or eligibility-check tool, consider using it before submitting a full application.
A prequalification check may use a soft inquiry, while a full application can result in a hard inquiry.
6. Credit Limit
Don’t automatically choose a card because it offers a larger credit limit.
A manageable limit that you can use responsibly may be more useful than a large limit that encourages overspending.
How to Improve Your Approval Odds With Fair Credit
You can’t guarantee approval, but you can make your application stronger.
Check your credit reports
Review your credit reports for inaccurate information before applying.
Pay existing accounts on time
Payment history is an important component of credit scoring.
Reduce credit-card balances
Lower balances can help improve your overall credit profile.
Avoid multiple applications
Applying for several cards in a short period can create multiple hard inquiries and make it harder to manage your accounts.
Consider prequalification
When available, use an issuer’s eligibility tool to see whether you may have a reasonable chance before submitting a full application.
Apply for a realistic card
Don’t apply only for premium cards that generally target good or excellent credit.
Should You Get a Credit Card With Fair Credit?
A credit card can be useful if you can manage it responsibly.
It may help you:
- Establish stronger payment history
- Improve your credit profile over time
- Earn cash-back rewards
- Increase your available revolving credit
- Eventually qualify for better credit-card products
But a credit card can also make your financial situation worse if you consistently carry balances or miss payments.
The goal should be responsible credit management, not simply obtaining a higher credit limit.
How to Use a Fair-Credit Card to Build Better Credit
Once you’re approved, your habits matter more than the card’s marketing.
Pay on time
Never intentionally miss a payment.
Pay the statement balance when possible
Paying the statement balance in full can help you avoid interest on purchases when your card’s terms provide a grace period.
Keep balances manageable
Don’t spend more simply because you have available credit.
Monitor your account
Check statements for unauthorized transactions and unexpected fees.
Don’t close accounts impulsively
Before closing an older account, consider how it could affect your credit profile and overall available credit.
Common Mistakes People With Fair Credit Make
Applying for too many cards
More applications don’t necessarily mean more approvals.
Chasing rewards while ignoring fees
A high rewards rate isn’t valuable if an annual fee or interest charges erase the benefit.
Carrying a balance to “build credit”
You generally don’t need to pay interest to build credit.
Maxing out the card
Using the entire available limit can make your credit profile look riskier.
Ignoring APR
Fair-credit cards can have high interest rates, so understand the cost before carrying a balance.
Frequently Asked Questions
Q1. What are the best credit cards for fair credit?
The best options depend on whether you prioritize no annual fee, cash back, dining rewards, travel rewards or credit building. Current fair-credit options include Capital One Platinum, QuicksilverOne, SavorOne and several other cards designed or marketed for fair or average credit.
Q2. What credit score is considered fair?
FICO generally considers 580 to 669 to be fair credit. However, different scoring models can use different ranges, and lenders can consider more than your credit score when evaluating an application.
Q3. Can I get a credit card with a 600 credit score?
Possibly. A 600 FICO score falls within the fair-credit range, and some issuers offer cards for fair or average credit. Approval still depends on your complete application, income, existing debt and other factors.
Q4. Can I get a credit card with a 650 credit score?
Yes, you may have several options. A 650 FICO score is within the fair-credit range, although the cards and terms available to you may differ from those offered to applicants with good or excellent credit.
Q5. Are fair-credit credit cards worth it?
They can be worthwhile if you use them responsibly. A fair-credit card can provide access to credit and potentially help you build toward a stronger credit profile, but fees and high APRs should be considered carefully.
Q6. Should I choose a secured card or an unsecured card?
If you qualify for a suitable unsecured card with reasonable terms, it may be preferable because it doesn’t require a security deposit. A secured card can be useful when your approval options are limited or you want a deposit-backed path to building credit.
Q7. Does applying for a credit card hurt your credit?
A full credit-card application can result in a hard inquiry, which may temporarily affect your credit score. Some issuers offer prequalification or eligibility checks that use a soft inquiry instead.
Q8. Can I get cash back with fair credit?
Yes. Several cards marketed toward fair-credit consumers offer cash-back rewards. However, compare the annual fee, reward categories and APR before choosing one.
Q9. How long does it take to improve fair credit?
There is no guaranteed timeline. Your credit profile can change as new payment history, balances and account information are reported. Consistent on-time payments and responsible credit use are important for long-term improvement.
Q10. Can I get a credit card with fair credit and no annual fee?
Yes. Several credit cards for fair or average credit have $0 annual fees, although eligibility varies by issuer. Before applying, compare the APR, rewards, fees, credit-building features, and whether you can prequalify without a hard credit inquiry.
Final Takeaway
The best credit cards for fair credit are the ones that fit your current financial situation without creating unnecessary costs.
If you want simplicity, a $0-annual-fee card such as Capital One Platinum may be worth considering. If rewards matter, cards such as QuicksilverOne or SavorOne may be more attractive, while students and people with limited approval options may have additional alternatives.
Before applying, compare the annual fee, APR, rewards, eligibility, credit-building features and prequalification options. Most importantly, choose a card you can manage responsibly.
Your next goal shouldn’t simply be getting a better card—it should be moving from fair credit toward good credit and eventually qualifying for stronger financial products.
Why Maintain Market Is Different
At Maintain Market, we don’t treat every credit-card applicant the same.
We separate fair credit, bad credit and no credit history, explain why a particular card may fit a specific borrower, and focus on the costs and trade-offs that matter before an application.
Credit-card terms can change, so readers should always verify the current issuer terms, fees, APRs, rewards and eligibility requirements before applying.
References
- Capital One — Credit Cards for Fair Credit
- Capital One — Credit Cards for Average Credit
- Discover — Credit Cards for Fair Credit
- Discover — Discover it Chrome
- NerdWallet — Best Credit Cards for Fair or Average Credit
- Bankrate — Best Credit Cards for Fair/Average Credit
- myFICO — FICO Score Ranges
Editorial Review
Reviewed for: U.S. credit-card information, fair-credit score ranges, current card availability, rewards, annual fees, credit-building considerations and application guidance.
This article is for educational purposes only and does not constitute financial advice. Credit-card approval, pricing, rewards and eligibility vary by issuer and applicant.