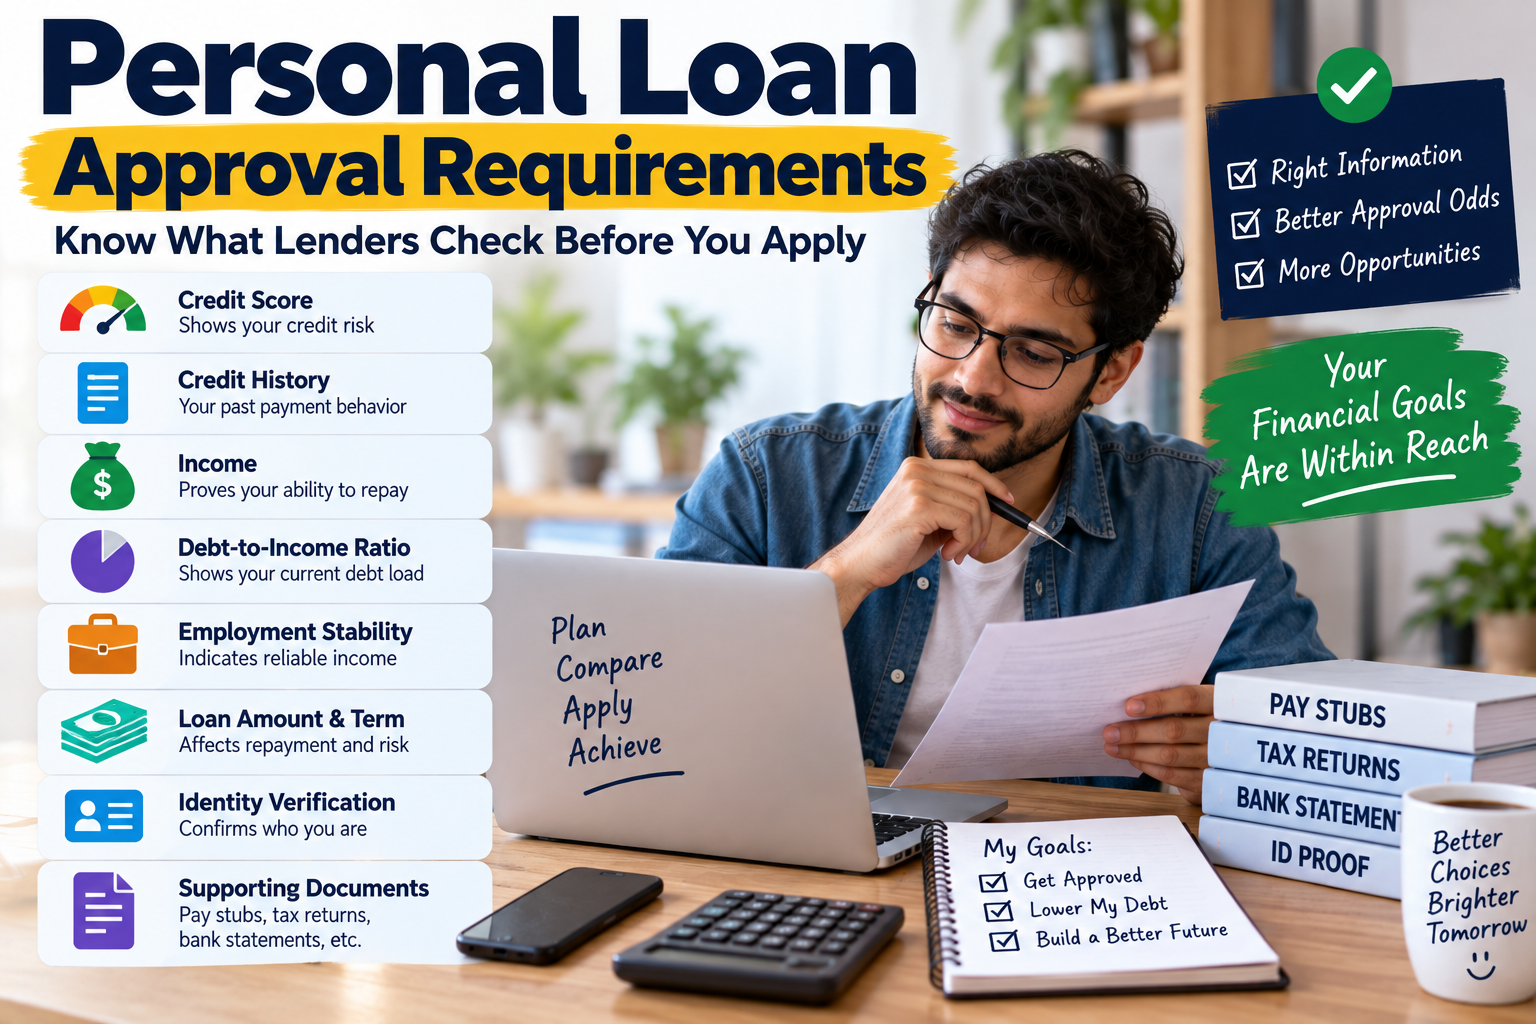
Understanding personal loan approval requirements before you apply can save you time, protect your credit score from unnecessary inquiries, and help you compare lenders more effectively. While every lender has its own eligibility rules, most personal-loan applications involve some combination of credit history, income, existing debt, identity verification, employment or income stability, and your requested loan amount.
The good news is that there is no single credit score or income level that guarantees approval with every lender. Your entire financial profile matters, and different lenders may evaluate the same borrower differently.
Quick Answer: What Are the Main Personal Loan Approval Requirements?
Most lenders look at several factors when deciding whether to approve a personal loan.
| Requirement | What the Lender May Check | Why It Matters |
|---|---|---|
| Credit score | Credit score and credit report | Helps assess credit risk |
| Credit history | Payment history, accounts and delinquencies | Shows how you have handled debt |
| Income | Salary, self-employment or other qualifying income | Helps establish repayment ability |
| Debt-to-income ratio | Monthly debt compared with gross income | Shows existing debt burden |
| Employment/income stability | Employment or recurring income | Helps evaluate income reliability |
| Loan amount | Amount you want to borrow | Affects repayment risk |
| Loan term | Length of repayment | Affects monthly payment and total cost |
| Identity | Name, address, SSN and other details | Helps verify the applicant |
| Bank information | Account and transaction information, when requested | May help verify income or cash flow |
| Documentation | Pay stubs, tax returns, bank statements and other records | Supports information on your application |
CFPB guidance explains that lenders may consider credit score and reports, income, debts, loan amount and term, applicable state-law limits, and other factors when determining personal-loan terms.
1. Credit Score
Your credit score is one of the most common factors lenders consider.
A higher credit score generally makes it easier to qualify and can improve your chances of receiving more favorable interest rates and terms. However, there is no universal minimum credit score for every personal loan. Different lenders have different standards.
For example, one lender may accept applicants with fair credit while another may primarily target borrowers with good or excellent credit.
Your credit score is also not the same thing as your complete credit profile.
2. Credit History
Lenders may look beyond your score and examine your actual credit history.
This can include:
- Payment history
- Current and past accounts
- Outstanding balances
- Collections
- Recent credit applications
- Delinquencies
- Bankruptcy history
- Length of credit history
Two people can have similar credit scores but receive different loan offers because their underlying credit histories are different.
The CFPB notes that credit scores are based on information in credit reports and that different scoring models can produce different scores.
3. Income
Income is another major part of many personal-loan applications.
A lender wants to determine whether you have enough reliable income to make the required monthly payments.
Depending on the lender, qualifying income may include:
- Full-time employment
- Part-time employment
- Self-employment
- Retirement income
- Pension income
- Certain government benefits
- Other recurring income
Federal lending rules generally prohibit creditors from automatically excluding certain protected sources of income simply because of where the income comes from. Lenders can still consider the amount of income and whether it is likely to continue.
4. Debt-to-Income Ratio
Your debt-to-income ratio, commonly called DTI, compares your monthly debt payments with your gross monthly income.
The basic formula is:
DTI = Total Monthly Debt Payments ÷ Gross Monthly Income × 100
For example, if your monthly debt payments are $800 and your gross monthly income is $4,000:
$800 ÷ $4,000 × 100 = 20% DTI
A lower DTI generally indicates that less of your income is already committed to debt payments.
However, there is no single DTI percentage that guarantees personal-loan approval. Different lenders and loan products can have different requirements.
5. Employment or Income Stability
Lenders may also want to understand how reliable your income is.
Traditional employees may provide employment information and pay stubs.
Self-employed borrowers may instead provide documents such as:
- Tax returns
- 1099 forms
- Bank statements
- Profit-and-loss statements
- Business records
Freelancers and contractors may also need additional documentation to demonstrate recurring income.
Being self-employed does not automatically prevent you from getting a personal loan. The important issue is whether you can adequately document your income and demonstrate your ability to repay.
6. Loan Amount
The amount you request can affect your application.
A $2,000 loan and a $30,000 loan represent very different levels of repayment risk.
If your income and existing debts don’t support a large monthly payment, requesting a smaller amount may be more realistic.
Before applying, determine exactly how much you need.
Don’t borrow more simply because a lender offers you a larger amount.
7. Loan Term
The repayment period can also affect the lender’s decision and the cost of your loan.
A longer term can reduce the required monthly payment, but you may pay more interest over the life of the loan.
A shorter term can increase your monthly payment while potentially reducing the total interest paid.
For example:
| Shorter Term | Longer Term | |
|---|---|---|
| Monthly payment | Usually higher | Usually lower |
| Repayment period | Shorter | Longer |
| Total interest | Often lower | Often higher |
| Budget impact | Higher monthly burden | Lower monthly burden |
Always compare the monthly payment and total repayment amount.
8. Identity and Personal Information
Before approving a loan, a lender generally needs to verify that you are who you say you are.
You may be asked for information such as:
- Full legal name
- Date of birth
- Social Security number
- Residential address
- Phone number
- Email address
- Government-issued identification
This information can also be used to obtain or verify your credit information and comply with applicable requirements.
Be careful when entering sensitive information online. Make sure you are dealing with a legitimate lender before submitting your Social Security number or bank details.
9. Financial Documentation
Depending on your situation and the lender, you may need to provide documentation supporting the information in your application.
Common documents can include:
- Recent pay stubs
- W-2 forms
- Tax returns
- 1099 forms
- Bank statements
- Proof of address
- Employment information
- Other income documentation
Not every lender will request every document.
Some lenders may be able to verify information electronically, while others may require you to upload documents.
10. Your Overall Ability to Repay
Ultimately, lenders want to determine whether you can reasonably repay the loan.
That means your application can be affected by the combination of:
- Income
- Existing debt
- Credit history
- Requested loan amount
- Loan term
- Monthly payment
- Other financial information
This is why focusing on a single requirement—such as “What credit score do I need?”—can be misleading.
A lender may approve someone with a lower score but strong income and manageable debt, while rejecting another applicant with a higher score but substantial existing obligations.
Personal Loan Approval Requirements by Borrower Type
Different borrowers may need to emphasize different parts of their application.
| Borrower | Important Factors to Prepare |
|---|---|
| W-2 employee | Pay stubs, employment information, credit history |
| Self-employed borrower | Tax returns, 1099s, bank statements, business records |
| Freelancer | 1099s, tax returns, bank statements, recurring income |
| Retired borrower | Retirement or pension income documentation |
| Low-income borrower | Stable income, manageable debt and affordable loan amount |
| Bad-credit borrower | Credit history, income, debt and realistic loan request |
| First-time borrower | Credit history, income and repayment capacity |
| Debt-consolidation borrower | Existing debts, income and new loan payment |
What Credit Score Do You Need for a Personal Loan?
There is no universal minimum credit score.
Experian notes that some lenders work with borrowers across a broad range of credit profiles, while lenders offering more favorable terms generally tend to prefer stronger credit.
A credit score should therefore be viewed as one part of your application, rather than an automatic pass-or-fail number.
If your credit score is low, you may still have options, but you could face higher APRs, smaller loan amounts or fewer lenders.
Is Income More Important Than Credit Score?
Neither should be viewed in isolation.
A strong credit score can help demonstrate responsible borrowing history, while sufficient income helps demonstrate repayment ability.
For example:
Borrower A
- Strong credit
- Low income
- High existing debt
Borrower B
- Average credit
- Stable income
- Low existing debt
Depending on the lender’s underwriting model, Borrower B could potentially have a stronger application despite having a lower credit score.
Lenders use different criteria, which is why comparing multiple offers can be valuable.
Do Personal Loans Require Proof of Income?
Many lenders require some form of income verification, although the exact process varies.
Traditional employees may use pay stubs or W-2 forms.
Self-employed applicants may use tax returns, 1099s or bank statements.
Some lenders may verify information electronically instead of asking you to manually upload documents.
The important distinction is that “no pay stub” does not necessarily mean “no income verification.”
Can You Get a Personal Loan Without a Job?
Possibly, depending on your income sources and the lender.
Being unemployed does not necessarily mean you have no qualifying income.
Certain sources of income may be considered when evaluating a credit application, including some retirement benefits, public assistance and other income sources. However, lenders can consider the amount and expected continuation of income.
If you have no reliable income at all, getting an affordable personal loan can be considerably more difficult.
Do Personal Loans Require Collateral?
Not always.
Many personal loans are unsecured, meaning you don’t pledge an asset such as a car or home as collateral.
Some lenders offer secured personal loans, where an asset supports the loan.
Secured financing can provide another borrowing option, but it also creates additional risk because the collateral may be at risk if you fail to repay according to the agreement.
Can You Get a Personal Loan With Bad Credit?
Yes, some lenders offer personal loans to borrowers with less-than-perfect credit.
However, approval can be more difficult and the cost of borrowing may be higher.
If you have poor credit, focus on:
- Comparing multiple lenders
- Checking APR rather than just monthly payment
- Reviewing all fees
- Borrowing only what you need
- Considering a smaller loan
- Improving your credit before applying if the expense isn’t urgent
You can also read our guide to Personal Loans for Bad Credit in the USA.
What Happens When You Apply for a Personal Loan?
The process typically looks like this:
Step 1: Check Your Credit
Review your credit score and credit reports so you know where you stand.
Step 2: Determine How Much You Need
Avoid requesting more money than necessary.
Step 3: Estimate Your Monthly Payment
Make sure the payment fits comfortably into your budget.
Step 4: Compare Lenders
Look at APR, fees, loan amounts and repayment terms.
Step 5: Prequalify When Available
Some lenders allow you to check potential rates before completing a full application.
Step 6: Submit the Application
Provide accurate personal, financial and employment information.
Step 7: Complete Verification
The lender may request income or identity documentation.
Step 8: Review the Final Offer
Don’t accept the loan until you understand the APR, fees, payment and total repayment.
Step 9: Receive the Funds
If approved and accepted, the lender will provide the funds according to its stated funding process.
Will Applying for a Personal Loan Hurt Your Credit?
It can, depending on the type of credit inquiry.
A formal application commonly involves a hard inquiry, which can affect your credit score.
However, simply asking about rates does not necessarily result in a hard inquiry, and some lenders may use soft inquiries during prequalification.
Before submitting an application, check whether the lender’s prequalification process uses a soft or hard credit inquiry.
How to Improve Your Chances of Approval
Pay Your Bills on Time
Payment history is an important part of your credit profile.
Reduce Existing Debt
Lower monthly debt obligations can improve your overall financial position.
Check Your Credit Reports
Look for inaccurate information and address errors before applying.
Request a Realistic Amount
Don’t ask for substantially more money than you need.
Keep Income Documentation Ready
Having your financial records organized can make the application process easier.
Compare Multiple Lenders
Different lenders can evaluate the same borrower differently.
Consider Waiting
If the loan isn’t urgent, improving your credit or reducing debt before applying may lead to better options.
What Can Cause a Personal Loan Application to Be Denied?
Common reasons may include:
- Insufficient income
- High debt-to-income ratio
- Weak credit history
- Recent missed payments
- Too many recent credit applications
- Requested loan amount too high
- Insufficient documentation
- Lender-specific eligibility requirements
If a lender denies your application, you generally have the right to receive the principal reasons for the decision or information about how to obtain them.
Instead of immediately applying elsewhere, use the denial information to identify what needs improvement.
Personal Loan Approval Checklist
Before applying, ask yourself:
- Have I checked my credit?
- Do I know my monthly income?
- Do I know my existing monthly debt payments?
- Have I calculated my DTI?
- Do I know exactly how much I need?
- Can I afford the estimated monthly payment?
- Do I have income documentation ready?
- Have I compared multiple lenders?
- Have I checked the APR and fees?
- Have I reviewed the total repayment amount?
If you can answer these questions before applying, you’ll be in a much better position to compare loan offers.
Frequently Asked Questions
Q1. What are the basic personal loan approval requirements?
Most lenders consider factors such as credit score, credit history, income, existing debt, debt-to-income ratio, requested loan amount and repayment term. Lenders may also verify your identity and income through documentation or electronic methods.
Q2. What credit score is needed for a personal loan?
There is no universal minimum credit score. Some lenders accept borrowers with fair or poor credit, while others have higher standards. Your credit score is only one part of the overall approval decision.
Q3. Do I need proof of income for a personal loan?
Many lenders require income verification, but the type of documentation varies. Employees may provide pay stubs or W-2s, while self-employed borrowers may use tax returns, 1099s or bank statements.
Q4. How much income do I need to qualify for a personal loan?
There is no universal minimum income requirement across all lenders. The lender may consider your income alongside your existing debts, requested loan amount and ability to repay.
Q5. Can I get a personal loan with bad credit?
Yes, some lenders work with borrowers who have bad credit. However, you may receive higher APRs, smaller loan amounts or less favorable terms than borrowers with stronger credit.
Q6. Can I get a personal loan if I’m self-employed?
Yes. Self-employed borrowers can qualify for personal loans, although they may need to provide additional documentation to verify their income. Tax returns, 1099s and bank statements are examples of documents a lender may request.
Q7. Do personal loans require collateral?
No. Many personal loans are unsecured and don’t require collateral. Some lenders also offer secured personal loans, which use an asset as security for the debt.
Q8. Does a personal loan application affect my credit score?
A formal loan application may result in a hard credit inquiry, which can affect your score. Some lenders offer prequalification using a soft inquiry, so check the lender’s process before applying.
Q9. What should I do if my personal loan application is denied?
Find out why you were denied before submitting more applications. If the issue is high debt, insufficient income, weak credit or missing documentation, addressing that specific problem may improve your chances of qualifying later.
Q10. Can I get a personal loan if I don’t meet all the approval requirements?
Yes. Some lenders may still consider your application if you have a lower credit score, limited credit history, or variable income. However, you may face higher interest rates, a smaller loan amount, or stricter terms.
Final Takeaway
Understanding personal loan approval requirements before applying can help you avoid unnecessary applications and make better borrowing decisions.
The most common factors include credit, income, existing debt, DTI, loan amount, repayment term, identity verification and supporting documentation. However, lenders use different underwriting criteria, so there is no single checklist that guarantees approval.
Before applying, check your credit, calculate your budget, organize your income documentation and compare multiple lenders. Most importantly, don’t judge a loan solely by whether you qualify.
A loan is only useful if you can comfortably repay it.
Why Maintain Market Is Different
Maintain Market focuses on explaining financial products in practical, straightforward language rather than simply telling readers which loan to choose.
With personal loans, approval is only one part of the decision. We also look at the factors that affect affordability—including APR, fees, repayment terms, existing debt and the borrower’s ability to manage the new payment.
The goal is to help readers understand the process before they take on new debt.
References
CFPB — What Is a Personal Installment Loan?
CFPB — What Is a Credit Score?
CFPB — When Will a Lender Run a Credit Check?
CFPB — Income and Lending Decisions
CFPB — What to Do if Your Credit Application Is Denied
Experian — Personal Loan Requirements
Experian — Credit Score Needed for a Personal Loan
NerdWallet — Requirements for a Personal Loan
Editorial Review
This article is for general educational purposes and does not constitute financial advice. Personal-loan requirements, APRs, fees, loan amounts, credit standards and documentation requirements vary by lender and can change over time. Review the lender’s current disclosures and loan agreement before borrowing.
Recommended Reads
Personal Loans for Bad Credit in the USA