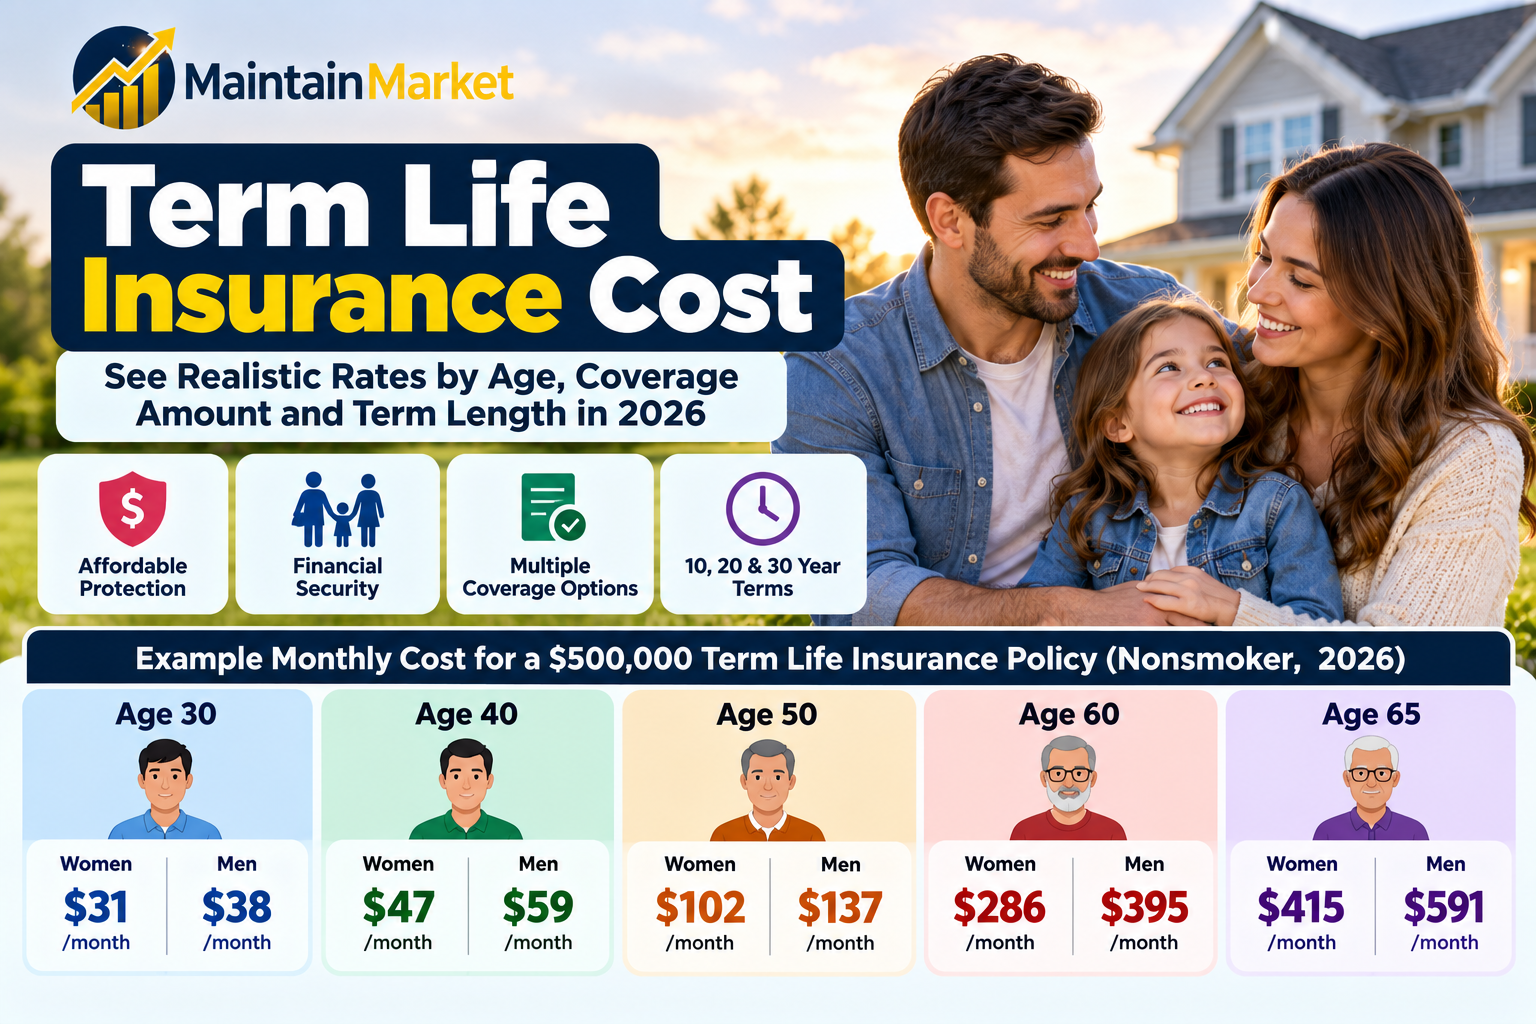
Term life insurance cost can vary significantly from one person to another. Age, coverage amount, term length, health, tobacco use, and the insurer’s underwriting rules can all affect the premium you pay. Data shows that a healthy nonsmoker may pay relatively affordable premiums for a $500,000 policy when applying at a younger age, while costs can rise sharply as age increases.
The numbers in this guide are illustrative rate examples, not guaranteed quotes. Your actual premium can be different because insurers evaluate applicants individually.
Quick Answer: How Much Does Term Life Insurance Cost?
For a healthy nonsmoker, a 20-year, $500,000 term life insurance policy can cost roughly $30–$60 per month in the 20s and 30s, depending on age, sex, insurer and underwriting class.
By age 40, current 2026 rate research shows averages around $47 per month for women and $59 per month for men for a $500,000, 20-year policy.
At older ages, the increase can be substantial. For example, one 2026 rate analysis shows average monthly premiums of approximately $102 for a 50-year-old woman and $137 for a 50-year-old man for the same $500,000, 20-year policy.
These figures are only benchmarks. Your actual quote may be higher or lower.
1. What Is the Average Term Life Insurance Cost?
There is no single price that applies to everyone.
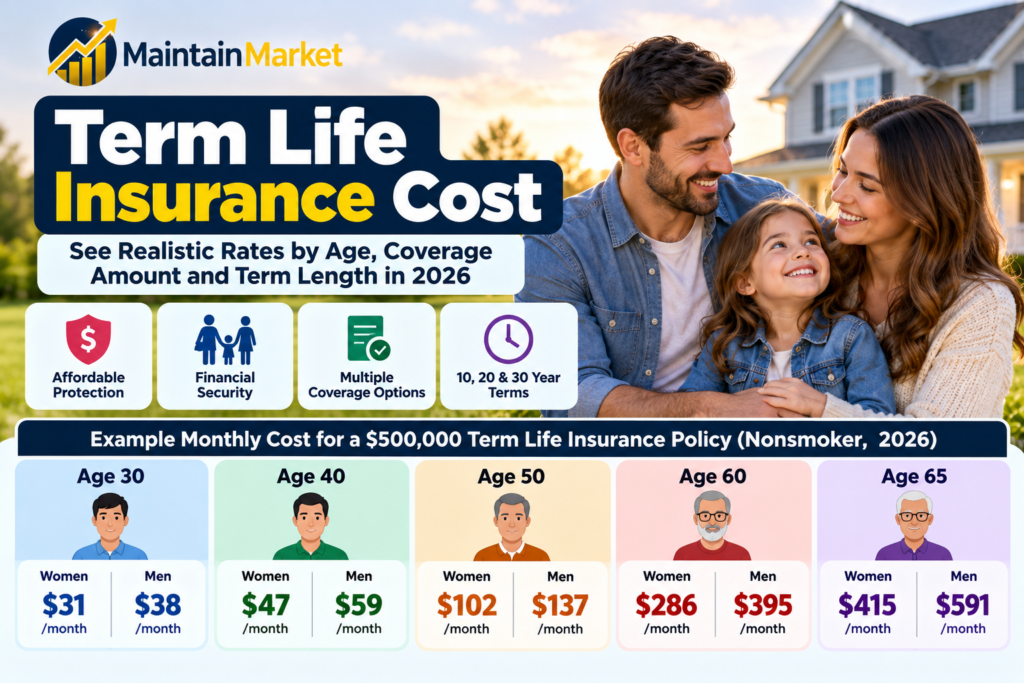
For example, current 2026 published rate data for a $500,000, 20-year term policy gives the following approximate monthly averages for healthy nonsmokers:
| Age | Women | Men |
|---|---|---|
| 25 | $30 | $32 |
| 30 | $31 | $38 |
| 35 | $37 | $47 |
| 40 | $47 | $59 |
| 45 | $69 | $90 |
| 50 | $102 | $137 |
| 55 | $168 | $231 |
| 60 | $286 | $395 |
| 65 | $415 | $591 |
These figures come from a 2026 analysis of term life insurance quotes and assume a $500,000, 20-year policy for nonsmokers with average health.
Your actual premium can differ based on your health, tobacco use, location, coverage amount, insurer and underwriting classification.
Important: Treat online rate tables as a starting point, not a personalized quote.
2. Why Does Term Life Insurance Cost Increase With Age?
Age is one of the most important factors insurers consider when pricing life insurance.
The basic reason is straightforward: as people get older, the statistical risk of death during the policy period generally increases.
That means an insurer may charge a younger applicant less for the same amount of coverage and term length.
For example, a $500,000, 20-year policy might have a much lower quoted premium for someone in their 20s than for someone applying in their 50s.
The difference becomes especially noticeable after age 40–50 in many published rate tables.
Example
Consider two applicants seeking:
- $500,000 coverage
- 20-year term
- Nonsmoker status
- Similar health
A 30-year-old could see a substantially lower premium than a 50-year-old.
That doesn’t mean the older applicant is being overcharged. The insurer is pricing two different risk profiles.
3. How Much Does a $500,000 Term Life Insurance Policy Cost?
A $500,000 policy is a common coverage level used in published rate comparisons.
For a healthy nonsmoker, current 2026 data gives examples such as:
| Applicant | Policy | Approx. monthly cost |
|---|---|---|
| Woman, age 30 | $500K / 20 years | $31 |
| Man, age 30 | $500K / 20 years | $38 |
| Woman, age 40 | $500K / 20 years | $47 |
| Man, age 40 | $500K / 20 years | $59 |
| Woman, age 50 | $500K / 20 years | $102 |
| Man, age 50 | $500K / 20 years | $137 |
These are published market averages rather than guaranteed offers.
The actual price could change considerably if the applicant has a different health classification, uses tobacco, chooses a different term, lives in a different state or selects a different insurer.
4. How Much Does a $1 Million Term Life Insurance Policy Cost?
A larger death benefit generally means a higher premium.
However, the premium does not necessarily double when coverage doubles.
For example, current 2026 rate data for a healthy 40-year-old nonsmoker shows approximately:
| Coverage | 20-Year Term | Woman | Man |
|---|---|---|---|
| $500,000 | 20 years | $47/month | $59/month |
| $1 million | 20 years | $86/month | $109/month |
This illustrates an important point:
More coverage costs more, but the cost per dollar of coverage can become more efficient at higher coverage levels.
That is one reason it can be useful to compare multiple coverage amounts rather than automatically choosing the smallest policy available.
5. How Much Does a 20-Year Term Life Insurance Policy Cost?
A 20-year term policy provides coverage for 20 years, assuming you continue meeting the policy requirements and paying premiums.
For a healthy nonsmoker, a $500,000 policy can have substantially different premiums depending on age.
For example:
- Age 30: around $31–$38 per month
- Age 40: around $47–$59 per month
- Age 50: around $102–$137 per month
- Age 60: around $286–$395 per month
The numbers above are examples from current published rate data.
A 20-year policy can make sense when your financial need has a defined time period, such as:
- Replacing income while children are dependent
- Covering a mortgage
- Protecting a spouse’s finances
- Covering other long-term financial obligations
6. How Much Does a 30-Year Term Life Insurance Policy Cost?
A 30-year term generally costs more than a comparable 20-year term because the insurer is providing coverage for an additional decade.
For example, 2026 published rate research for a healthy 40-year-old nonsmoker shows approximately:
| Coverage | 10-Year | 20-Year | 30-Year |
|---|---|---|---|
| $500K — Woman | $34/mo | $47/mo | $82/mo |
| $500K — Man | $41/mo | $59/mo | $104/mo |
| $1M — Woman | $60/mo | $86/mo | $154/mo |
| $1M — Man | $74/mo | $109/mo | $198/mo |
These figures demonstrate why term length matters.
A longer policy may cost more each month, but it can provide protection for a longer period.
7. How Much More Does Term Life Insurance Cost for Smokers?
Tobacco use can have a major effect on life insurance premiums.
Insurers generally consider tobacco use an important underwriting factor because of the associated health risks.
Current 2026 published rate data shows the difference can be substantial.
For example, for a $500,000, 20-year policy:
| Applicant | Nonsmoker example | Smoker example |
|---|---|---|
| Woman, age 30 | ~$182/year | ~$645/year |
| Man, age 30 | ~$213/year | ~$795/year |
| Woman, age 40 | ~$278/year | ~$1,157/year |
| Man, age 40 | ~$321/year | ~$1,455/year |
| Woman, age 50 | ~$636/year | ~$2,560/year |
| Man, age 50 | ~$810/year | ~$3,495/year |
These are published rate examples and not guaranteed quotes.
The difference illustrates how strongly tobacco status can affect pricing.
If you stop using tobacco, ask insurers about their current underwriting rules. Some companies may reconsider your classification after a qualifying period, but requirements vary.
8. How Does Your Health Affect Term Life Insurance Cost?
Your health can have a significant impact on your premium.
During underwriting, an insurer may consider information such as:
- Medical history
- Current health conditions
- Height and weight
- Prescription medications
- Blood pressure
- Cholesterol
- Tobacco use
- Family medical history
- Lifestyle factors
- Certain hazardous activities
The exact underwriting process differs by insurer.
A healthy applicant may qualify for a more favorable risk class than someone with significant health conditions.
That doesn’t automatically mean someone with a health condition cannot get affordable coverage.
Different insurers have different underwriting guidelines.
9. Does Gender Affect Term Life Insurance Cost?
Published life insurance rate tables often show different average premiums for men and women.
For example, current 2026 rate data for a $500,000, 20-year policy shows an average of about:
- $47/month for a 40-year-old woman
- $59/month for a 40-year-old man
These are averages from a specific rate analysis, not universal prices.
Insurers also consider many other variables, including age, health, tobacco use, coverage amount and term length.
When comparing quotes, focus on the actual premiums offered to you rather than assuming a published average will apply to your situation.
10. How Does the Coverage Amount Affect Term Life Insurance Cost?
The amount of coverage you purchase directly affects the premium.
Common coverage amounts include:
- $100,000
- $250,000
- $500,000
- $750,000
- $1 million
- $2 million or more
For example, 2026 published rate data for a 40-year-old nonsmoker shows approximately:
| Coverage | Woman | Man |
|---|---|---|
| $100K | $16/month | $19/month |
| $250K | $28/month | $35/month |
| $500K | $47/month | $59/month |
| $750K | $67/month | $85/month |
| $1M | $86/month | $109/month |
These figures show why you shouldn’t choose coverage based only on the monthly premium.
A $100,000 policy may be inexpensive, but it may not provide enough money to replace income, pay debts or support dependents.
11. What Are the Biggest Factors That Determine Term Life Insurance Cost?
Your premium can depend on several variables.
Age
Older applicants generally pay more because the insurer is covering a higher mortality risk.
Coverage amount
A $1 million policy generally costs more than a $250,000 policy.
Term length
A 30-year policy generally costs more than a comparable 10- or 20-year policy.
Health
Your health and medical history can affect your underwriting classification.
Tobacco use
Smoking and other tobacco use can significantly increase premiums.
Policy type
Term life insurance is generally less expensive than permanent life insurance for comparable death-benefit protection during the early policy period.
Insurer
Different companies use different underwriting guidelines and pricing models.
That’s why comparing multiple quotes can matter.
12. Term Life Insurance Cost vs. Whole Life Insurance Cost
Term and permanent life insurance are structured differently.
Term insurance provides coverage for a specified period.
Permanent insurance is designed to provide coverage for a longer period and may include cash-value features depending on the policy.
Because of these differences, premiums can be dramatically different.
For example, current published 2026 data for a 40-year-old shows a $500,000, 20-year term policy averaging roughly $47–$59 per month in one rate analysis, while whole life averages hundreds of dollars per month.
This isn’t an apples-to-apples comparison because the policies have different features and purposes.
The important question is not simply:
“Which premium is cheaper?”
Instead ask:
“What type and amount of coverage fits the financial need I am trying to protect?”
13. Does No-Medical-Exam Life Insurance Cost More?
It can.
“No medical exam” does not necessarily mean “no underwriting.”
Depending on the insurer and product, the company may use:
- Application questions
- Prescription databases
- Medical records
- Electronic health information
- Automated underwriting
- Other third-party data
Some applicants may receive an accelerated underwriting decision without a traditional medical exam.
Others may still be asked for additional medical information or an exam.
Because underwriting methods vary, compare the actual premium and policy terms rather than assuming no-exam coverage will always be cheaper or more expensive.
14. How Much Does Term Life Insurance Cost at Age 30?
Age 30 is a useful example because published 2026 rates are still relatively low for many healthy nonsmokers.
For a $500,000, 20-year policy, one current rate analysis gives approximate averages of:
- Woman: $31/month
- Man: $38/month
A 30-year-old may also choose a longer term if the financial need is expected to last longer.
For example, someone with young children and a long mortgage may compare 20-year and 30-year coverage.
The decision should be based on the financial obligation being protected, not simply on getting the lowest monthly premium.
15. How Much Does Term Life Insurance Cost at Age 40?
For a healthy nonsmoker seeking $500,000 of coverage for 20 years, current published 2026 data gives approximate averages of:
- Woman: $47/month
- Man: $59/month
The same data shows that choosing a 30-year term can increase the premium considerably.
This is why the term length should be considered alongside the coverage amount.
Someone who only needs protection until a mortgage is substantially paid down may have a different coverage period from someone who wants to protect children who are currently very young.
16. How Much Does Term Life Insurance Cost at Age 50?
At age 50, premiums can be considerably higher than they are at age 30 or 40.
For a $500,000, 20-year policy, one 2026 rate analysis gives approximately:
- Woman: $102/month
- Man: $137/month
Health and tobacco status can create even larger differences.
Someone applying at 50 should compare multiple insurers because underwriting guidelines can vary substantially.
17. Why Do Two People Get Different Life Insurance Quotes?
Two people of the same age can receive very different premiums.
For example, two 40-year-olds may both request $500,000 of coverage for 20 years, but one could receive a lower quote because of differences in:
- Health
- Tobacco use
- Medical history
- Family history
- Weight
- Prescription medications
- Underwriting class
- Lifestyle
- Insurer pricing
This is why published “average cost” tables should never be treated as guaranteed quotes.
18. How Can You Lower Your Term Life Insurance Cost?
You can’t control every factor insurers use, but you can make some decisions that may affect your premium.
Compare multiple insurers
Different companies can price the same applicant differently.
Apply when you’re younger
Age is an important pricing factor, and premiums generally increase as you get older.
Avoid tobacco
Tobacco use can significantly increase life insurance premiums.
Choose the right coverage amount
Don’t automatically buy more coverage than your financial situation requires.
Choose an appropriate term
A longer term generally costs more.
Maintain healthy habits
Health can influence underwriting.
Be accurate on your application
Don’t hide medical or tobacco information to try to obtain a lower premium.
Misrepresentation can create serious problems with a policy.
19. What Should You Compare Besides the Monthly Premium?
Price is important, but it isn’t the only thing to examine.
Before purchasing a term life policy, compare:
| Factor | Why It Matters |
|---|---|
| Monthly premium | Determines your ongoing cost |
| Death benefit | Amount paid to beneficiaries if the insured dies during the covered term |
| Term length | Determines how long the coverage lasts |
| Premium guarantee | Shows whether the premium is fixed for the stated period |
| Renewability | Explains whether coverage can continue after the initial term |
| Conversion option | May allow conversion to certain permanent coverage |
| Underwriting | Determines how your risk is evaluated |
| Exclusions | Explains circumstances that may affect coverage |
| Financial strength | Important when evaluating an insurer |
| Policy riders | Additional features may affect cost |
Read the policy documents carefully before purchasing.
20. A Simple Term Life Insurance Cost Example
Imagine a 40-year-old nonsmoker wants:
- $500,000 coverage
- 20-year term
- Level premiums
A 2026 published rate analysis puts the average around:
$47/month for women
or
$59/month for men
That would represent approximately:
- $564/year for the $47 monthly example
- $708/year for the $59 monthly example
Over 20 years, ignoring any changes, taxes, fees or policy-specific provisions, those simple monthly figures would equal approximately:
- $11,280
- $14,160
This is only an illustration using published average rates. Actual premiums can be different.
Term Life Insurance Cost Calculator: Simple Formula
You can estimate your annual premium from a monthly quote:
Annual Premium = Monthly Premium × 12
For example:
$50 × 12 = $600 per year
To estimate the total premiums over a level-premium period:
Estimated Total Premiums = Monthly Premium × 12 × Number of Years
Example:
$50 × 12 × 20 = $12,000
This is only a premium calculation. It should not be interpreted as the financial return or “value” of the insurance policy.
Is Cheap Term Life Insurance Always Better?
Not necessarily.
The cheapest policy may not provide the coverage period, death benefit, conversion feature or other policy terms you need.
Instead of searching only for the lowest premium, compare:
- Coverage amount
- Term length
- Premium guarantee
- Insurer financial strength
- Policy features
- Conversion options
- Renewability
- Exclusions
- Underwriting requirements
A slightly higher premium may be reasonable if the policy better matches your financial needs.
Common Mistakes When Comparing Term Life Insurance Cost
Looking at only one quote
One insurer’s price isn’t necessarily representative of the market.
Assuming online averages are guaranteed
Published averages are benchmarks. Your actual underwriting result can be different.
Buying too little coverage
Saving money on premiums isn’t useful if the death benefit is insufficient for the financial need.
Choosing a term that’s too short
A low-cost 10-year policy may not protect a 25-year financial obligation.
Ignoring tobacco classification
Tobacco use can have a significant effect on premiums.
Hiding medical information
Always provide accurate information on the application.
Comparing only premiums
Policy terms and insurer requirements also matter.
Waiting too long
Age is an important factor in life insurance pricing.
Frequently Asked Questions
How much does term life insurance cost per month?
It depends on age, coverage, term length, health, tobacco use and other underwriting factors. For example, current 2026 published data shows a healthy 40-year-old nonsmoker buying $500,000 of 20-year coverage might average about $47 per month for a woman or $59 for a man.
Is $500,000 term life insurance expensive?
For some healthy younger applicants, $500,000 of term coverage can cost relatively little compared with permanent life insurance. However, premiums can rise significantly with age, tobacco use, health conditions and longer policy terms.
How much is a $1 million term life insurance policy?
The cost depends heavily on age and underwriting. For example, current 2026 published data shows a healthy 40-year-old nonsmoker may average around $86 per month for a woman and $109 per month for a man for a 20-year, $1 million policy.
Is term life insurance cheaper than whole life insurance?
Generally, term life insurance has lower premiums than permanent life insurance for comparable death-benefit protection during the early policy period. The policies have different structures and features, so they shouldn’t be compared on price alone.
Does smoking make term life insurance more expensive?
Yes. Tobacco use can substantially increase life insurance premiums. Current 2026 published rate data shows much higher average premiums for smokers than nonsmokers with otherwise comparable coverage.
Does age affect term life insurance cost?
Yes. Age is one of the major factors used in life insurance underwriting and pricing. Published 2026 rate tables show premiums generally increasing as the applicant gets older.
Does a longer term cost more?
Generally, yes. A 30-year term usually costs more than a comparable 20-year term because the insurer is providing coverage for a longer period.
Can I get cheap term life insurance with health problems?
Possibly. Having a health condition doesn’t automatically mean you cannot obtain coverage. Different insurers have different underwriting guidelines, so comparing companies can be useful.
Is no-medical-exam term life insurance cheaper?
Not necessarily. No-exam policies can use different underwriting methods, and premiums depend on the applicant and product. Compare actual quotes and policy terms rather than assuming an exam-free policy will cost less.
Can I renew term life insurance after the policy ends?
Many term policies provide renewal provisions, but the terms vary. NAIC notes that premiums can be higher when a policy is renewed, so review the policy’s renewal provisions and future premium schedule before relying on renewal.
Term Life Insurance Cost Checklist
Before buying a policy, check:
- Your desired death benefit
- Your required coverage period
- Your current age
- Your health classification
- Tobacco status
- Monthly premium
- Annual premium
- Whether the premium is level
- Renewal provisions
- Conversion provisions
- Policy exclusions
- Insurer financial strength
- Available riders
- Quotes from multiple insurers
Final Takeaway
Term life insurance cost is highly personal.
A healthy nonsmoker in their 20s or 30s may find a $500,000 policy relatively inexpensive, while premiums can rise considerably for applicants in their 40s, 50s and beyond. Tobacco use, health, coverage amount and term length can also make a major difference.
The best way to evaluate a policy is not to ask only, “What is the cheapest term life insurance?”
Instead, ask:
“How much coverage do I need, how long do I need it, and which insurer offers terms that fit my situation at a price I can maintain?”
Published rate tables are useful for understanding the market, but your actual quote is what matters when making a purchase decision.
Why Maintain Market Is Different
At Maintain Market, we don’t want readers to make insurance decisions based on a single advertised premium.
For term life insurance, we focus on:
- Explaining what actually determines the premium
- Showing real-world cost examples
- Separating published averages from personalized quotes
- Explaining how age, health and tobacco use affect pricing
- Comparing coverage amounts and term lengths
- Using authoritative insurance sources
- Encouraging readers to compare actual policy terms before purchasing
Insurance prices change, and underwriting differs between insurers. That’s why we focus on helping readers understand the numbers rather than presenting one price as if it applies to everyone.
References
- NAIC — Life Insurance
- NAIC — Life Insurance Topics
- NAIC — Life Insurance Buyer’s Guide
- NAIC — What Type of Life Insurance Is Right for You?
- NAIC — Life Insurance Purchase Tips
- MoneyGeek — 20-Year Term Life Insurance Rates
- Fidelity — How Much Does Life Insurance Cost in?
- NAIC — Life Insurance Roadmap
- NAIC — Consumer Life Insurance Publications
Editorial Review
Reviewed for U.S. term life insurance terminology, premium factors, coverage amounts, term lengths and published rate examples.
Rate examples are illustrative and based on datasets. Actual premiums vary according to insurer, state, age, health, tobacco use, coverage amount, term length, underwriting classification and other factors. Readers should obtain personalized quotes and review policy documents before purchasing coverage.