When choosing health insurance in the United States, understanding your out-of-pocket costs is just as important as comparing monthly premiums. Two terms you’ll frequently encounter are copay and coinsurance. Both determine how much you pay for medical services, but they work differently.
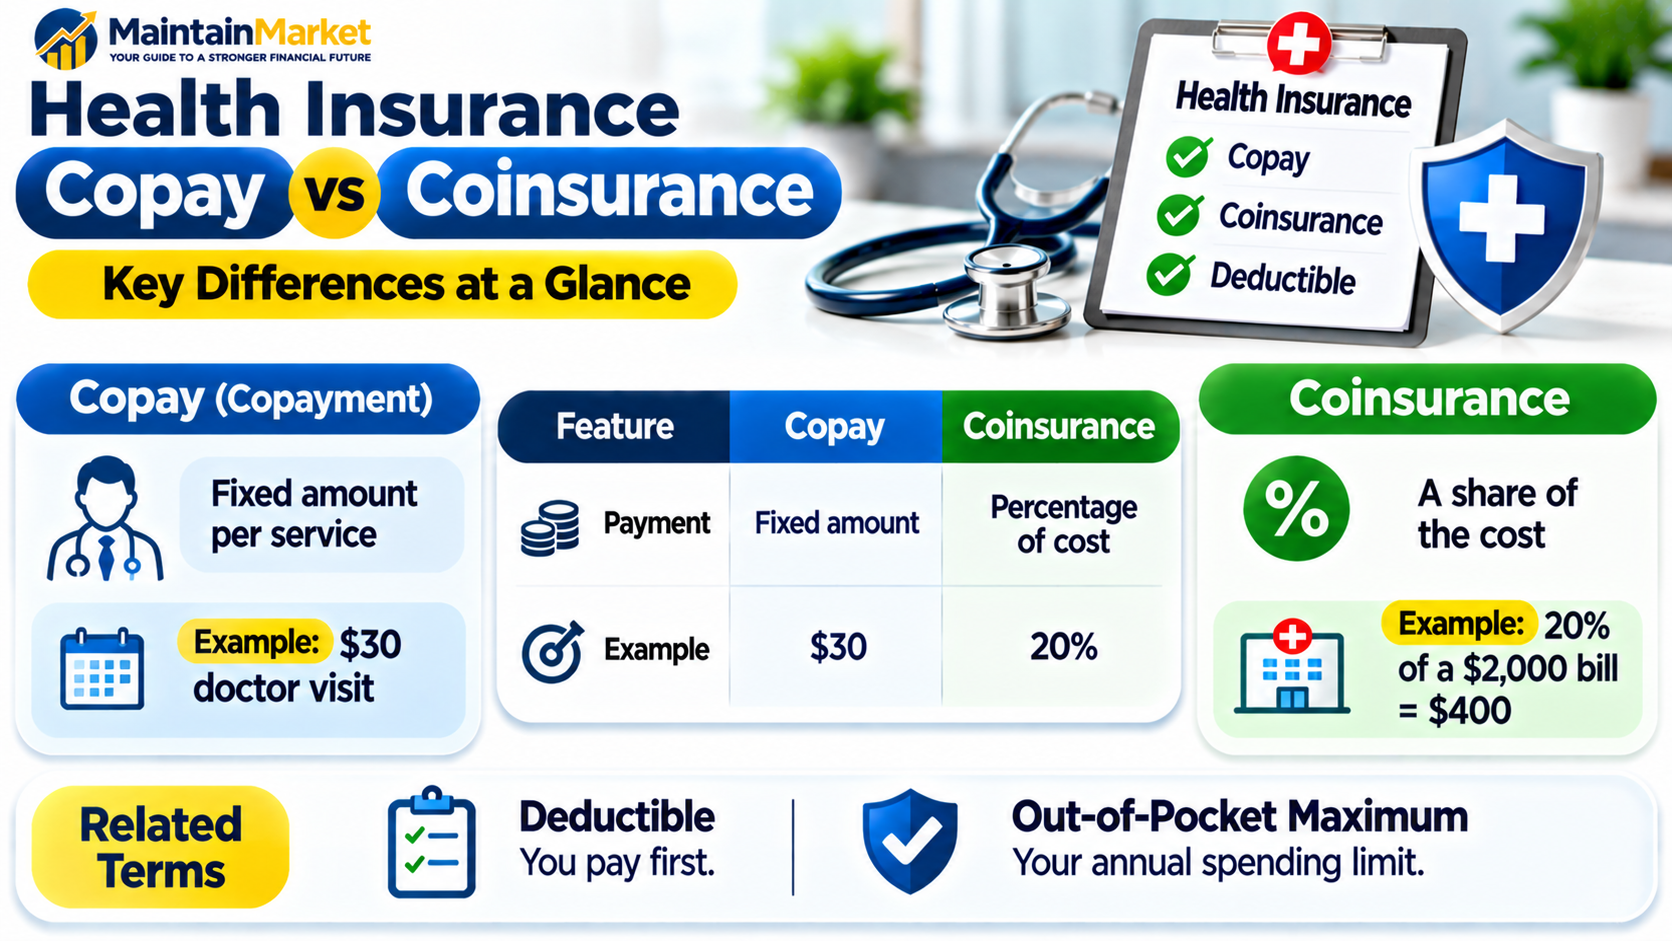
A copay (copayment) is a fixed dollar amount you pay for a covered healthcare service, while coinsurance is a percentage of the allowed cost of a covered service that you pay.
For example, your health insurance plan might require a $30 copay for a primary care visit or 20% coinsurance for a covered medical procedure after you meet your deductible.
Understanding the difference between health insurance copay vs coinsurance can help you estimate medical expenses, compare insurance plans, and avoid unexpected healthcare bills.
In this guide, we’ll explain how both work, how deductibles affect your payments, and how to calculate your potential healthcare costs.
What Is a Copay in Health Insurance?
A copay, also called a copayment, is a fixed amount you pay for a covered healthcare service.
The amount generally depends on the type of service you receive and the terms of your insurance plan.
For example, your health insurance policy might require:
- $25 for a primary care visit.
- $50 for a specialist consultation.
- $20 for certain prescription medications.
- $150 for an eligible emergency room visit.
These are illustrative amounts, not standard prices.
Unlike coinsurance, a copay is generally a predetermined dollar amount rather than a percentage of the medical bill.
How Does a Copay Work?
Imagine your health insurance plan requires a $30 copay for a primary care visit.
You visit an in-network doctor, and the plan’s allowed amount for the appointment is $150.
Your payment would generally be:
| Expense | Amount |
|---|---|
| Allowed cost of doctor visit | $150 |
| Your copay | $30 |
| Insurance plan pays | $120 |
In this simplified example, you pay $30, and the insurance company covers the remaining $120.
However, the actual payment depends on your plan’s rules. Some services may be subject to a deductible before the copay applies.
Advantages of Copayments
- Predictable costs: You generally know the fixed copay amount before receiving many covered services.
- Easier budgeting: Fixed payments can make routine healthcare expenses easier to estimate.
- Convenient payments: Many copays are collected when you receive medical care.
- Different service categories: Plans can set different copays for primary care, specialists, urgent care, and prescriptions.
Disadvantages of Copayments
- Multiple visits add up: Frequent doctor visits can create substantial expenses over time.
- Not every service has a fixed copay: Hospital procedures and expensive treatments may use coinsurance instead.
- Deductible conditions may apply: Some services require you to pay the allowed cost until you meet your deductible.
- Plan restrictions: Copays may differ between in-network and out-of-network providers.
What Is Coinsurance in Health Insurance?
Coinsurance is the percentage of the allowed cost of a covered healthcare service that you pay.
Unlike a copay, which is a fixed amount, coinsurance changes depending on the cost of the service.
It generally applies after you have met your health insurance deductible, although the exact rules depend on your plan.
For example, if your plan has 20% coinsurance, you pay 20% of the allowed cost of an eligible service, while the insurance company pays the remaining 80%.
How Does Coinsurance Work?
Suppose you have a health insurance plan with:
- Allowed medical expense: $2,000
- Coinsurance: 20%
- Deductible: Already met
Your payment would be:
$2,000 × 20% = $400
| Expense | Amount |
|---|---|
| Allowed medical expense | $2,000 |
| Your coinsurance (20%) | $400 |
| Insurance pays (80%) | $1,600 |
In this example, you pay $400, and your health insurance plan pays $1,600.
The actual amount may differ if the service is subject to additional limits, exclusions, or cost-sharing rules.
Advantages of Coinsurance
- Shared medical expenses: You and your insurer share the allowed cost of covered services.
- Percentage-based structure: Your share is calculated according to the plan’s coinsurance rate.
- Out-of-pocket protection: Eligible coinsurance payments generally count toward your plan’s annual out-of-pocket maximum.
- Potentially manageable costs: Your share may be reasonable for less expensive services.
Disadvantages of Coinsurance
- Unpredictable expenses: Your payment depends on the cost of the medical service.
- Higher costs for expensive treatment: A percentage of a large medical bill can still be substantial.
- Deductible requirements: You may have to pay the full allowed amount before coinsurance begins.
- Out-of-network costs: Coinsurance may be higher for eligible out-of-network services.
Health Insurance Copay vs Coinsurance: What’s the Difference?
The main difference is how your share of medical expenses is calculated.
A copay is usually a fixed dollar amount, while coinsurance is a percentage of the allowed cost.
| Feature | Copay | Coinsurance |
|---|---|---|
| Meaning | Fixed payment for a covered service | Percentage of the allowed cost |
| Payment amount | Usually fixed | Changes with service cost |
| Calculation | Predetermined dollar amount | Allowed cost × percentage |
| Deductible | May apply before or independently of deductible | Generally applies after deductible |
| Example | $30 doctor visit | 20% of allowed medical cost |
| Cost predictability | Generally easier to predict | Depends on medical expense |
| Common use | Doctor visits and prescriptions | Hospital services and procedures |
Remember: Your insurance plan determines when copays and coinsurance apply. Some services may have both types of cost sharing, depending on the plan.
Copay vs Coinsurance: Real-Life Examples
Let’s understand the difference through three practical examples.
Example 1: Doctor Visit With a Copay
Imagine your insurance plan requires a $30 copay for an in-network primary care appointment.
You visit your doctor, and the allowed amount is $150.
Your payment is $30, assuming the visit qualifies for the copay and no additional cost-sharing rule applies.
Example 2: Hospital Treatment With Coinsurance
Suppose you receive a covered hospital service with an allowed cost of $5,000.
Your deductible has already been met, and your coinsurance is 20%.
Your payment:
$5,000 × 20% = $1,000
Your insurance company pays the remaining $4,000.
Example 3: Coinsurance Before Meeting Your Deductible
Suppose your plan has:
- Medical expense: $3,000
- Remaining deductible: $1,500
- Coinsurance: 20%
You first pay the remaining $1,500 deductible.
The remaining allowed cost is:
$3,000 − $1,500 = $1,500
Your coinsurance payment is:
$1,500 × 20% = $300
Your total payment is:
$1,500 + $300 = $1,800
| Calculation | Amount |
|---|---|
| Total allowed medical expense | $3,000 |
| Remaining deductible | $1,500 |
| Remaining cost after deductible | $1,500 |
| Your coinsurance (20%) | $300 |
| Your total payment | $1,800 |
| Insurance pays | $1,200 |
This example assumes the service is covered, subject to the deductible and coinsurance, and no other limits apply.
What Is the Difference Between Copay, Coinsurance, and Deductible?
These three terms are closely related, but they represent different types of healthcare expenses.
- Copay: A fixed amount you pay for a covered service.
- Coinsurance: A percentage of the allowed cost you pay for a covered service.
- Deductible: The amount you generally pay for covered services subject to the deductible before your insurance plan starts sharing those costs.
Comparison Table
| Term | What You Pay | Example |
|---|---|---|
| Copay | Fixed dollar amount | $30 per doctor visit |
| Coinsurance | Percentage of allowed cost | 20% of a covered procedure |
| Deductible | Amount paid before applicable plan payments begin | $2,000 per year |
How Do They Work Together?
Consider a hypothetical insurance plan with:
- Annual deductible: $2,000
- Primary care copay: $30
- Specialist copay: $50
- Coinsurance: 20%
- In-network out-of-pocket maximum: $7,000
You may pay a fixed copay for certain covered office visits, while other services require you to meet your deductible before coinsurance applies.
The plan’s Summary of Benefits and Coverage explains which services are subject to each payment requirement.
What Is an Out-of-Pocket Maximum?
An out-of-pocket maximum is the maximum amount you pay during a plan year for covered services that count toward the plan’s limit.
After reaching this limit, your health insurance plan generally pays 100% of the allowed costs for covered in-network benefits for the remainder of the plan year.
For eligible Marketplace plans, covered in-network deductibles, copayments, and coinsurance generally count toward this limit.
However, monthly premiums, noncovered services, and certain out-of-network expenses do not count.
Example of an Out-of-Pocket Maximum
Suppose your health insurance plan has a $6,000 annual in-network out-of-pocket maximum.
During the year, you pay:
| Healthcare expense | Amount |
|---|---|
| Deductible | $2,000 |
| Copayments | $500 |
| Coinsurance | $3,500 |
| Total | $6,000 |
You have reached your out-of-pocket maximum.
For covered in-network services subject to the limit, your insurer generally pays 100% of the allowed amount for the rest of the plan year.
The exact rules depend on your policy and applicable federal requirements.
Which Is Better: Copay or Coinsurance?
Neither copay nor coinsurance is automatically better.
The better arrangement depends on your healthcare needs, the services you expect to use, and the overall cost structure of your health insurance plan.
When a Copay May Be Better
A plan with predictable copays may be useful if:
- You visit your primary care doctor regularly.
- You frequently consult specialists.
- You want predictable payments for routine services.
- You prefer knowing your payment amount before an appointment.
- You regularly purchase covered prescription medications.
When Coinsurance May Be Manageable
Coinsurance may be manageable if:
- You have relatively low healthcare usage.
- Your plan has an affordable coinsurance percentage.
- You have enough savings to handle unexpected medical expenses.
- Your deductible and out-of-pocket maximum are reasonable.
- You understand how much you may pay for expensive treatments.
However, a lower coinsurance percentage does not automatically make a plan cheaper. A high deductible or high monthly premium can change the overall cost.
How to Compare Copay and Coinsurance When Choosing Health Insurance
Before choosing a health insurance plan, review more than just the monthly premium.
Consider the following factors:
- Monthly premium: Calculate how much you will pay for health insurance throughout the year.
- Annual deductible: Check how much you must pay before deductible-based coverage begins.
- Primary care copay: Find out how much you pay for routine doctor visits.
- Specialist copay: Check whether specialist appointments have a different copay.
- Coinsurance percentage: Review your share of eligible medical costs after the deductible.
- Prescription drug costs: Compare copays or coinsurance for generic, preferred brand-name, and specialty medications.
- Out-of-pocket maximum: Understand the maximum eligible in-network cost sharing you could pay during the year.
- Provider network: Check whether your preferred doctors, hospitals, and pharmacies participate in the plan.
Where Can You Find Copay and Coinsurance Details in Your Health Insurance Policy?
You do not have to guess how much your insurance plan will charge.
You can find these details in your Summary of Benefits and Coverage (SBC) and full plan documents.
Look for these sections:
- Primary care visits
- Specialist visits
- Emergency room services
- Hospital stays
- Diagnostic tests
- Prescription medications
- Outpatient procedures
- Deductible
- Coinsurance
- Out-of-pocket maximum
You can also contact your insurance company and ask for the exact cost-sharing amount for a specific medical service.
Before receiving expensive treatment, ask your provider and insurer to confirm the estimated allowed amount and your expected responsibility.
Frequently Asked Questions About Health Insurance Copay vs Coinsurance
1. What is the difference between copay and coinsurance?
A copay is a fixed amount you pay for a covered medical service, such as $30 for a doctor visit. Coinsurance is a percentage of the allowed cost of a covered service, such as 20% of a medical procedure.
2. Is a copay better than coinsurance?
A copay can make routine medical expenses easier to predict because it is generally a fixed amount. Coinsurance varies with the cost of treatment. Which is better depends on your plan, healthcare needs, and overall expenses.
3. Do you pay coinsurance before or after your deductible?
Coinsurance generally applies after you meet the applicable deductible. Until then, you may have to pay the allowed cost of covered services subject to that deductible. Some services may have different cost-sharing rules.
4. Do copays count toward your deductible?
It depends on your health insurance plan. Some copayments count toward the deductible, while others do not. Check your plan documents to understand how copays are applied.
5. Do copays count toward the out-of-pocket maximum?
Eligible copayments generally count toward the in-network out-of-pocket maximum under ACA-compliant plans. However, your plan documents determine which payments qualify.
6. Can you have both copay and coinsurance in the same health insurance plan?
Yes. Many health insurance plans use both. For example, you might pay a fixed copay for a doctor visit and 20% coinsurance for certain hospital services.
7. What does 20% coinsurance mean?
It means you generally pay 20% of the allowed cost of a covered service after meeting the applicable deductible. Your insurer pays the remaining 80%, subject to the plan’s terms.
8. What does a $40 copay mean?
A $40 copay means you pay a fixed $40 for a covered service when the plan’s copay rules apply. It does not mean you pay 40% of the medical bill.
9. Does coinsurance apply to prescription drugs?
It can. Some insurance plans use coinsurance for certain prescription medications, while others charge fixed copays. The amount depends on the drug formulary and plan design.
10. What happens when I reach my out-of-pocket maximum?
Once you reach the applicable out-of-pocket maximum, your insurer generally pays 100% of covered in-network costs for the rest of the plan year. Premiums, noncovered services, and certain other expenses are not included.
11. Is a $0 copay the same as free health insurance?
No. A $0 copay means you do not pay a copayment for that particular covered service. You may still have to pay monthly premiums, deductibles, coinsurance, or other eligible expenses.
12. How can I calculate my coinsurance payment?
Multiply the allowed cost of the covered service by your coinsurance percentage.
For example, if the allowed cost is $1,000 and your coinsurance is 20%, your payment is $200, assuming you have already met the applicable deductible.
Final Thoughts: Understand Your Healthcare Costs Before Choosing a Plan
When comparing health insurance copay vs coinsurance, remember that both are forms of cost sharing, but they calculate your payment differently.
A copay is generally a fixed dollar amount, making certain healthcare expenses easier to predict. Coinsurance is a percentage of the allowed cost, so your payment changes depending on the medical service.
However, neither should be evaluated separately from your deductible, monthly premium, provider network, and out-of-pocket maximum.
Before selecting a health insurance plan, review the Summary of Benefits and Coverage and estimate how much you could spend on routine visits, prescriptions, and unexpected medical treatment.
Understanding these costs can help you choose a health insurance plan that fits your healthcare needs and budget.
Disclaimer: This article is for general educational purposes only and does not constitute health insurance, financial, or medical advice. Copayments, coinsurance, deductibles, and out-of-pocket limits vary by insurer, plan, provider network, and covered service. Review your plan documents or contact your insurer for exact cost-sharing details.
Authoritative Sources
- HealthCare.gov: Copayment
- HealthCare.gov: Coinsurance
- HealthCare.gov: Deductible
- HealthCare.gov: Out-of-Pocket Maximum
- HealthCare.gov: Understanding Your Total Healthcare Costs
- Centers for Medicare & Medicaid Services: Health Insurance Terms You Should Know
- MedlinePlus: Understanding Your Healthcare Costs