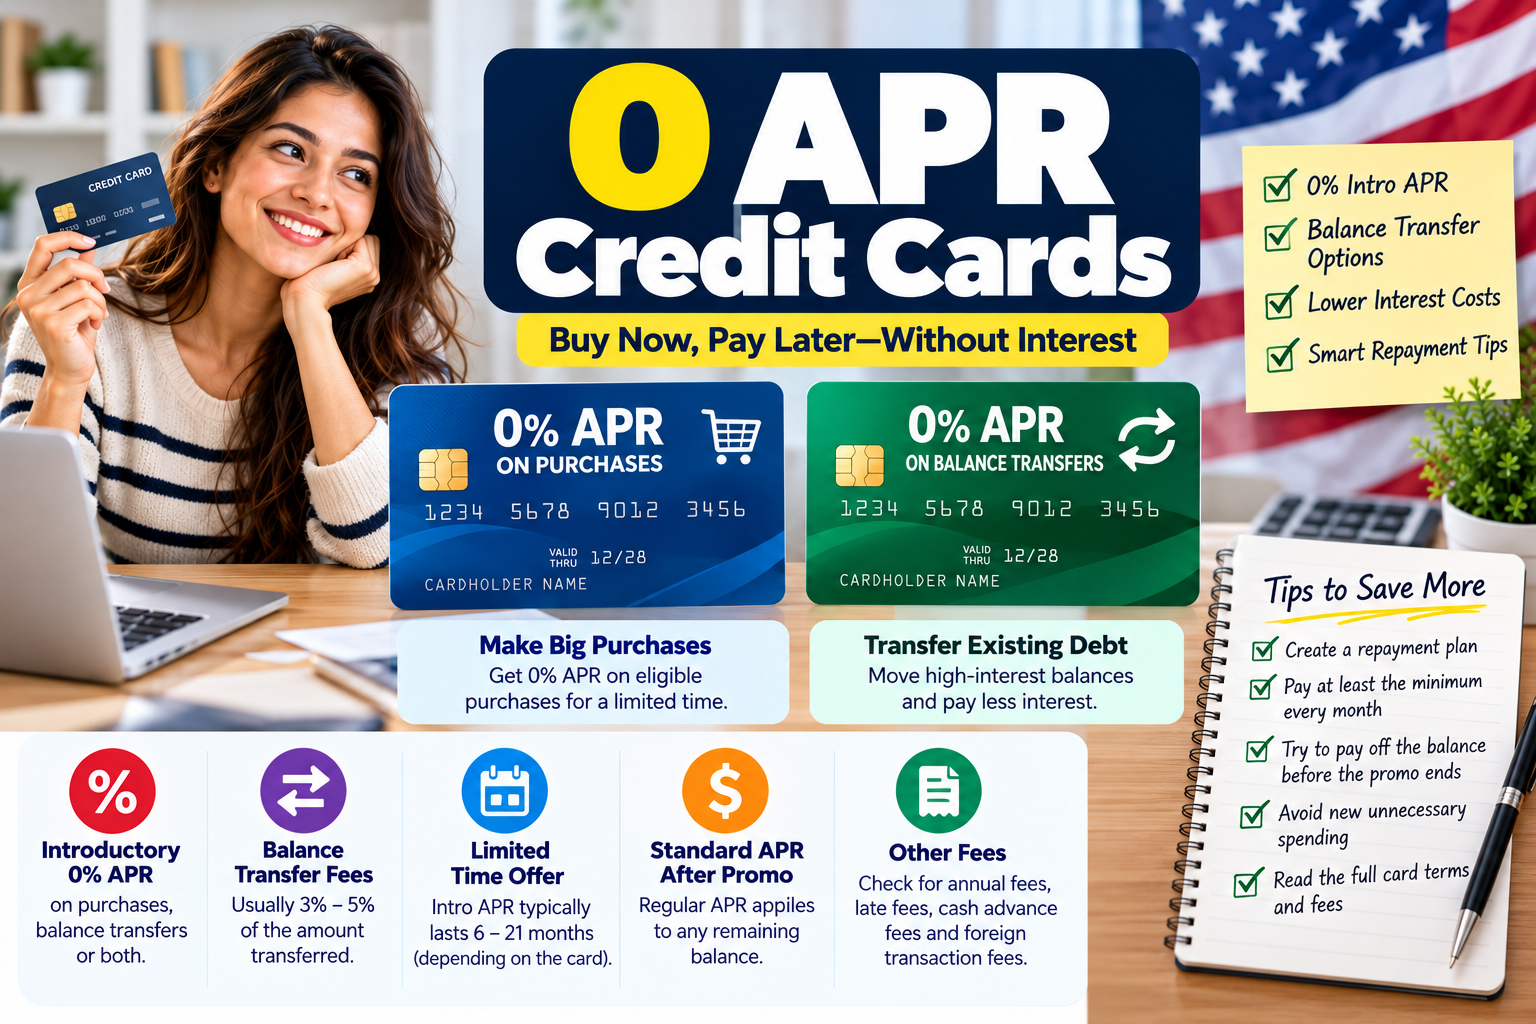
0 APR Credit Cards can help you finance eligible purchases or pay down existing credit card debt without paying interest during a promotional period. However, the offer is temporary, and the standard APR, balance transfer fees, and repayment rules can make a significant difference to your total cost.
The right card depends on whether you want to make a large purchase, transfer an existing balance, or earn rewards while managing your spending. Here is how to compare offers, avoid expensive mistakes, and choose a card that fits your financial situation.
Quick Answer: What Are 0 APR Credit Cards?
0 APR credit cards are credit cards that offer a temporary introductory annual percentage rate (APR) of 0% on eligible purchases, balance transfers, or both.
During the promotional period, qualifying balances generally do not accrue interest. After the introductory period ends, the card’s regular APR usually applies to any remaining balance and eligible new transactions.
Important: A 0% introductory APR does not automatically mean the card has no fees. Balance transfer fees, annual fees, late fees, and other charges may still apply.
How Do 0 APR Credit Cards Work?
When you open a card with a 0% introductory APR, the issuer offers a temporary interest-free period for certain transactions.
For example, suppose you charge $2,400 in eligible purchases to a card offering 0% introductory APR for 12 months. If you make the required payments and pay the balance in full before the promotional period ends, you can avoid interest on those eligible purchases.
However, you must check the offer’s exact terms. Not every 0% APR offer applies to every type of transaction.
There are two main types of offers:
1. 0% APR on Purchases
A purchase offer lets you make eligible purchases without interest during the introductory period.
This may be useful for:
- Buying essential appliances or furniture.
- Paying for planned home improvements.
- Covering a necessary purchase while spreading payments over several months.
- Managing a large expense when you have a reliable repayment plan.
A 0% purchase APR is not free money. You still owe the entire amount you charge, and the regular APR may apply to the remaining balance after the offer expires.
2. 0% APR on Balance Transfers
A balance transfer offer lets you move eligible debt from another credit card to a new card with a promotional interest rate.
This may help you reduce interest costs while paying off existing debt. However, issuers often charge a balance transfer fee, commonly a percentage of the amount transferred.
The new card may also have a separate promotional period for balance transfers and purchases. Always check both.
Best 0 APR Credit Cards to Compare
The following cards are examples worth comparing because their issuers advertise introductory APR offers. Offers and eligibility requirements can change, so verify the current terms before applying.
| Card | Why consider it? | What to check |
|---|---|---|
| Chase Slate® | Advertised introductory APR on purchases and balance transfers | Promotional length, transfer fee, and regular APR |
| Wells Fargo Reflect® | Advertised extended introductory APR on purchases and qualifying balance transfers | Transfer deadline, fee, and post-promotion APR |
| Discover it® Balance Transfer | Advertised introductory APR on purchases and balance transfers | Transfer fee, promotional duration, and regular APR |
These are comparison candidates, not a guarantee of approval or a ranking for every applicant. The best card for you depends on the offer available when you apply and how you plan to use it.
Official card pages:
- Chase: Slate® and other balance transfer offers
- Wells Fargo: Reflect® Card
- Discover: Balance Transfer Credit Cards
Check the issuer’s official pricing and terms page for the exact introductory period, regular APR, fees, and eligibility requirements. Do not rely solely on an advertisement or comparison website.
9 Smart Ways to Choose 0 APR Credit Cards
1. Decide Whether You Need a Purchase or Balance Transfer Offer
Start by identifying your main goal.
If you need to finance a planned purchase, look for a 0% introductory APR on purchases. If you already owe money on another credit card, compare balance transfer offers instead.
Some cards offer both, but the promotional periods and eligibility rules may differ.
Tip: Do not assume that a 0% purchase APR automatically applies to transferred balances.
2. Compare the Length of the Introductory Period
A longer introductory period gives you more time to repay eligible debt without interest.
For example, a 15-month promotion gives you three more months than a 12-month offer. That extra time can reduce the monthly amount you need to pay, provided you do not add more debt.
Compare the promotional period with your realistic repayment timeline, rather than choosing a card simply because it advertises the longest offer.
3. Calculate Balance Transfer Fees
A balance transfer fee can reduce the money you save.
Suppose you transfer $5,000 to a card with a 3% balance transfer fee.
| Calculation | Amount |
|---|---|
| Balance transferred | $5,000 |
| Transfer fee at 3% | $150 |
| Starting balance, including the fee | $5,150 |
You would start with a balance of $5,150 if the fee were added to your transferred balance. Your actual treatment may depend on the issuer’s terms and available credit limit.
Even with a 0% introductory APR, you must account for this fee when deciding whether the transfer is worthwhile.
4. Check the Regular APR After the Promotion
The introductory offer is temporary. Once it ends, any remaining balance subject to the regular APR can begin accruing interest.
Before applying, look at the card’s post-promotion APR range and understand that your approved rate may depend on your creditworthiness.
If you expect to carry a balance beyond the introductory period, the regular APR becomes especially important.
5. Check the Annual Fee and Other Charges
Many introductory APR cards have no annual fee, but you should verify the terms rather than assume.
Review:
- Annual fees.
- Balance transfer fees.
- Late payment fees.
- Foreign transaction fees, if relevant.
- Cash advance fees and APRs.
Cash advances generally have separate, expensive terms and may not qualify for a 0% promotional rate.
6. Make a Repayment Plan Before Applying
A 0% APR card works best when you have a clear plan to repay the balance before the promotional period ends.
Use this simple formula:
Monthly repayment target = Balance to repay ÷ Number of months available
For example, if you transfer $3,600 and have 12 months to repay it, the target is $300 per month, plus any applicable fees or other charges.
This is a planning estimate, not a required payment amount. Continue making at least the minimum payment required by your card agreement.
7. Understand How New Purchases Are Treated
If you transfer a balance and then make new purchases on the same card, those purchases may accrue interest even while the transferred balance has a promotional APR.
The exact treatment depends on the card’s terms and whether you retain the purchase grace period.
A safer approach is to avoid mixing new spending with transferred debt unless you understand how interest will be calculated.
8. Check Your Credit Profile Before Applying
The longest 0% APR offers may require good or excellent credit, although approval criteria vary by issuer.
Before applying:
- Review your credit reports for errors.
- Pay bills on time.
- Reduce existing credit card balances where possible.
- Use an issuer’s prequalification tool if available.
- Avoid submitting multiple applications in a short period.
Prequalification is not a guarantee of approval. A formal application may result in a hard inquiry on your credit report.
9. Read the Full Offer Terms
Before accepting a card, verify the promotional APR, the qualifying transactions, the length of the offer, the transfer deadline, and the regular APR.
Also check what happens if you make a late payment. Do not assume that missing a payment has no effect on your promotional rate.
The issuer’s pricing and terms disclosure and cardholder agreement are more reliable than a short promotional headline.
0 APR Credit Cards: Purchase APR vs. Balance Transfer APR
| Feature | 0% purchase APR | 0% balance transfer APR |
|---|---|---|
| Main purpose | Finance eligible new purchases | Pay down eligible existing card debt |
| Interest during promotion | Usually 0% on qualifying purchases | Usually 0% on qualifying transferred balances |
| Common cost to check | Annual fee and other charges | Balance transfer fee and other charges |
| Main risk | Remaining balance may accrue interest later | Transfer fee and remaining debt may outweigh savings |
| Best suited for | Planned purchases with a repayment schedule | Existing high-interest credit card debt |
A card may offer both types of promotion, but never assume the terms are identical.
Illustrative Example: How Much Could You Save?
Imagine you have $4,000 in credit card debt at a 24% APR and are considering transferring it to a card offering 0% APR for 15 months with a 3% balance transfer fee.
The transfer fee would be $120, making the initial transferred balance approximately $4,120 if the fee is added to the balance.
If you paid off the balance evenly over 15 months, your target would be approximately $275 per month.
Your potential savings would depend on how quickly you would otherwise repay the original debt, the interest that would have accrued, any additional charges, and whether you qualify for the offer. The $120 transfer fee is a cost you would need to compare against those potential interest savings.
This is an illustrative calculation, not a prediction of your actual savings. You can use a credit card payoff calculator to compare different repayment schedules.
Advantages and Disadvantages of 0 APR Credit Cards
| Advantages | Disadvantages |
|---|---|
| Can reduce interest on eligible balances temporarily | Promotional APR eventually ends |
| May help you repay existing card debt faster | Balance transfer fees may apply |
| Can spread the cost of a planned purchase | Remaining balances may accrue interest later |
| Some offers have no annual fee | Approval may require a stronger credit profile |
| May provide time to create a repayment plan | Additional spending can increase debt |
The main benefit is the opportunity to direct more of your payments toward the balance rather than interest during the qualifying period. That benefit is strongest when you avoid unnecessary spending and follow a realistic payoff plan.
Common Mistakes to Avoid
Assuming 0% APR Means No Fees
An introductory APR applies to interest, not necessarily to every fee. Review the card’s full pricing disclosure before applying.
Paying Only the Minimum
Minimum payments may not be enough to clear the balance before the promotion ends. Calculate your own monthly payoff target.
Ignoring the Promotion End Date
Mark the promotional expiration date on your calendar. If a balance remains, the regular APR may apply going forward.
Making New Purchases Without Checking the Terms
A balance transfer promotion may not cover new purchases. Carrying a transferred balance can also affect the interest-free grace period on new spending.
Applying for Too Many Cards
Multiple applications can result in hard inquiries and may make credit management more difficult. Compare offers carefully before submitting an application.
Using a Cash Advance Instead of a Purchase
Cash advances generally have different fees and interest terms. Do not assume that a 0% purchase promotion covers cash withdrawals or similar transactions.
Who Should Consider a 0 APR Credit Card?
A 0% introductory APR card may be worth considering if you:
- Have a planned purchase and can repay it within the promotional period.
- Have high-interest credit card debt and can save more in interest than the transfer fee costs.
- Can make every required minimum payment on time.
- Understand the regular APR and the consequences of carrying a balance after the offer expires.
It may be a poor fit if your budget is already stretched, you expect to miss payments, or you would use the available credit to accumulate more debt.
If you cannot comfortably repay the balance, consider contacting your existing card issuer to ask about hardship options or reviewing other debt repayment strategies before applying for another card.
How to Apply for a 0 APR Credit Card
- Set your goal: Decide whether you need a purchase offer, a balance transfer, or both.
- Compare the offers: Check introductory periods, fees, regular APRs, and annual fees.
- Review your credit: Check your credit reports and consider prequalification where available.
- Read the issuer’s terms: Confirm the qualifying transactions and any deadlines.
- Apply through the official issuer website: Provide accurate information and review the disclosures.
- Plan your payments: Calculate a monthly target that aims to clear the balance before the promotional period expires.
Approval, credit limits, and available offers depend on the issuer’s criteria and your circumstances.
Frequently Asked Questions About 0 APR Credit Cards
1. What does 0 APR mean on a credit card?
A 0% APR introductory offer means eligible transactions do not accrue interest during the specified promotional period, subject to the card’s terms. It does not necessarily eliminate fees or apply to all transactions. Once the promotion ends, the applicable regular APR generally applies to any remaining balance.
2. Are 0 APR credit cards really interest-free?
They can be interest-free on eligible balances during the introductory period. However, you may still pay balance transfer fees, annual fees, late fees, or other charges. Read the card agreement carefully to understand exactly what qualifies for the promotional rate.
3. How long do 0% APR offers last?
The length varies by card and offer. Some introductory promotions last several months, while others last longer. The issuer must disclose the introductory period and the rate that applies afterward. Always verify the current offer before applying.
4. Can I transfer a balance to a 0 APR credit card?
Yes, if the card offers a promotional balance transfer APR and your transfer qualifies under its terms. The issuer may charge a balance transfer fee, impose a transfer deadline, or limit how much debt you can transfer. Confirm these details before proceeding.
5. Do 0 APR credit cards hurt your credit score?
Applying may result in a hard inquiry, which can affect your credit score. Opening a new account can also affect the length of your credit history and your total available credit. Responsible use and on-time payments can support healthy credit habits over time, but no card guarantees a higher score.
6. Can I get a 0 APR credit card with fair or poor credit?
It may be more difficult because many introductory APR offers target applicants with stronger credit profiles. Approval criteria differ among issuers, so check eligibility and prequalification options where available. Avoid applying repeatedly without comparing your chances and reviewing your credit report.
7. What happens when the 0% APR period ends?
The card’s regular APR generally applies to any remaining balance covered by the promotional offer. The balance does not automatically disappear, and interest may make repayment more expensive. Aim to repay the eligible balance before the promotional period ends.
8. Is a 0 APR card better than a balance transfer loan?
It depends on the total cost and repayment terms. A 0% balance transfer card may save interest but can charge a transfer fee and has a limited promotional period. A personal loan may offer a fixed repayment schedule and a different interest rate. Compare fees, interest, monthly payments, and the total amount you would repay before choosing.
9. Can I use a 0 APR credit card for cash advances?
Do not assume so. Cash advances generally have separate APRs and fees, and introductory purchase or balance transfer promotions usually do not automatically cover them. Check the card’s pricing terms before using the card for any cash advance.
Why Maintain Market Is Different
At Maintain Market, our goal is to help readers understand the costs and trade-offs behind financial products rather than focus only on promotional headlines.
When comparing 0 APR credit cards, we emphasize the full introductory period, balance transfer fees, post-promotion APR, payment planning, and the conditions that can affect your savings. These details help you evaluate whether an offer fits your needs instead of choosing a card based on one attractive feature.
Always confirm rates, fees, eligibility, and terms directly with the card issuer before applying.
References
- CFPB — Credit Card Key Terms
- CFPB — Can a balance transfer fee be charged on a zero-percent rate offer?
- CFPB — How long can an introductory rate last?
- Chase — Balance Transfer Credit Cards
- Wells Fargo — Reflect Card
- Discover — Balance Transfer Credit Cards
Editorial Review
This article is intended for general educational purposes for U.S. consumers. Credit card offers, introductory APR periods, fees, eligibility requirements, and standard APRs can change. Review the current issuer disclosures before making a financial decision.