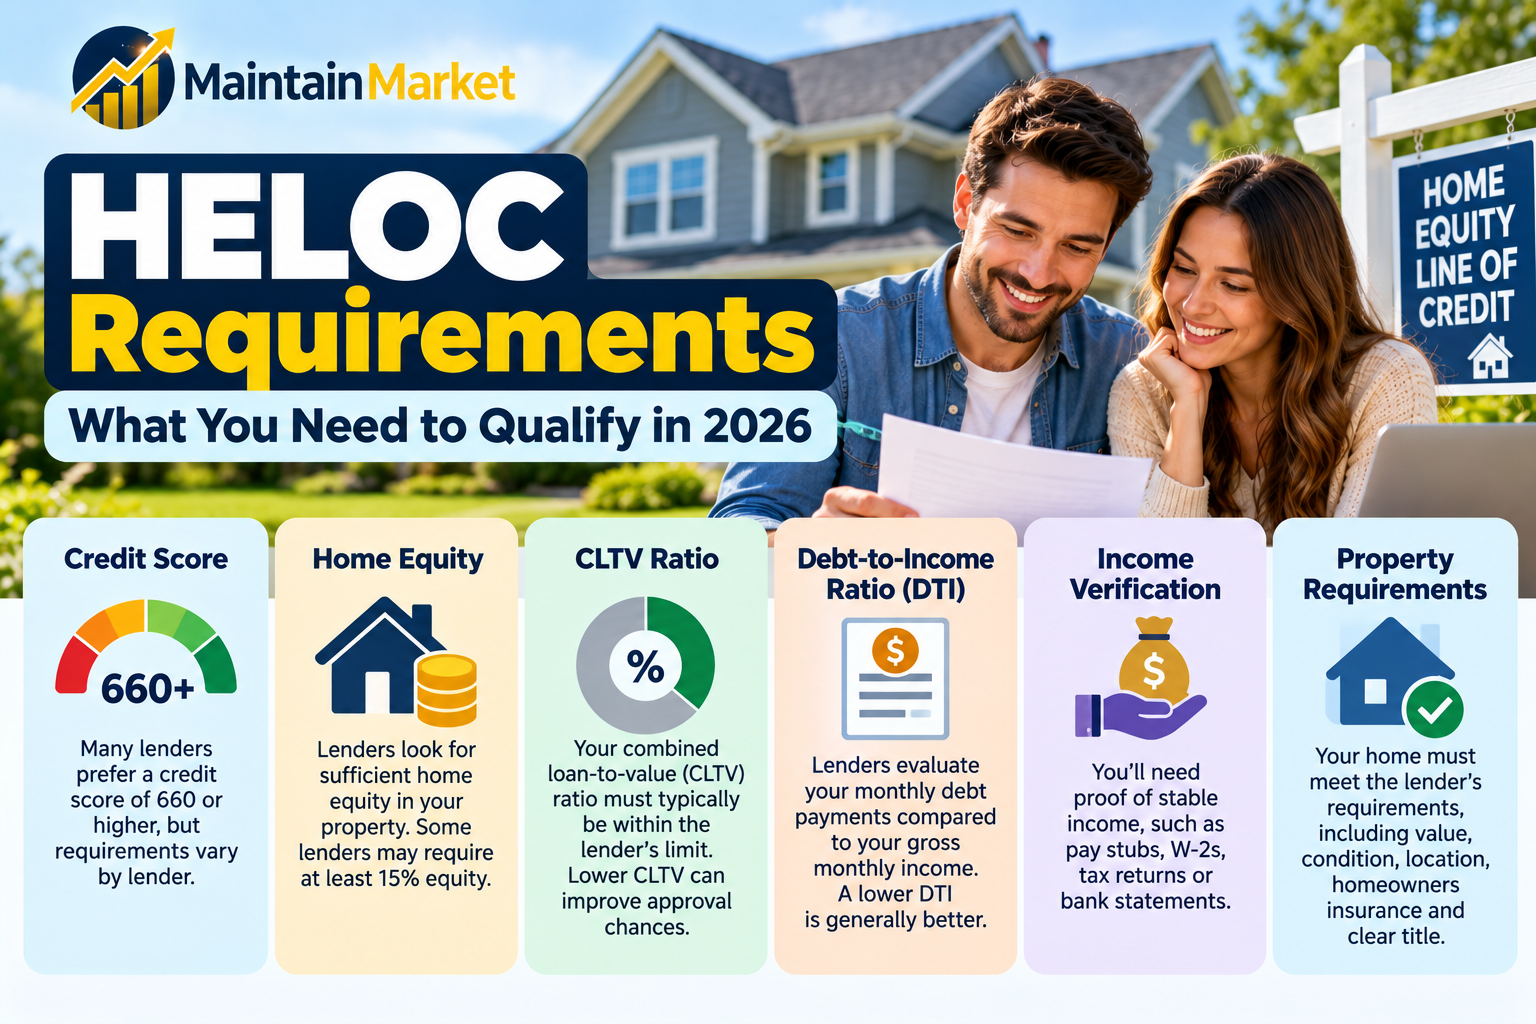
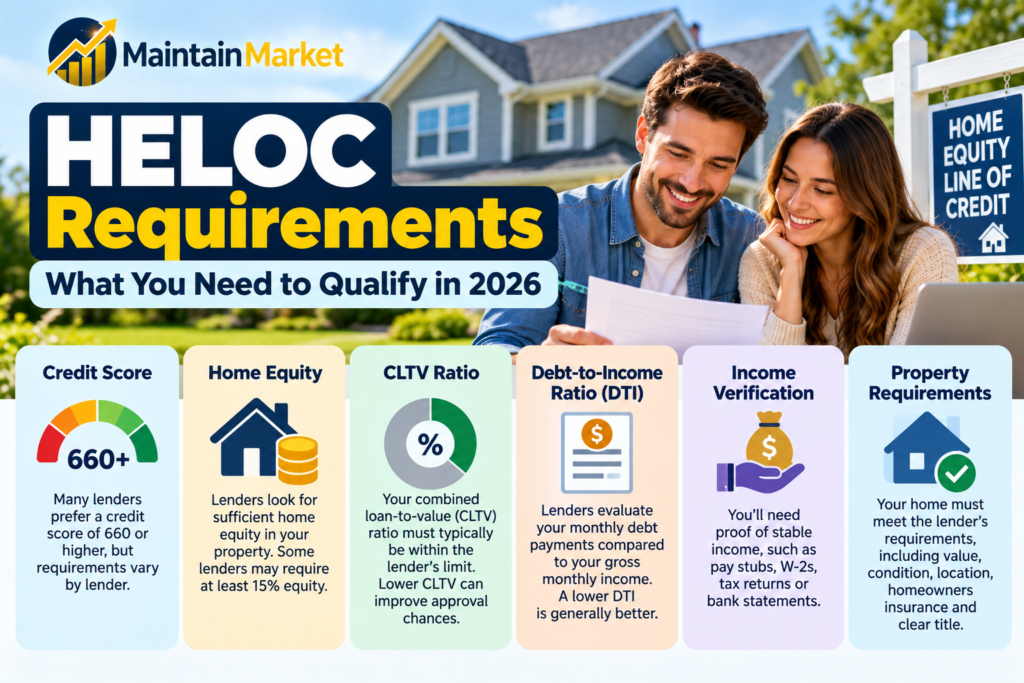
HELOC requirements can vary from one lender to another, but most lenders look closely at your home equity, credit history, income, debt-to-income ratio, property, and ability to repay the line of credit. In 2026, some major lenders publicly list minimum credit scores around 660, but there is no single credit score or equity requirement that applies to every HELOC lender.
If you’re considering a Home Equity Line of Credit, understanding these requirements before applying can help you estimate your approval chances and avoid unnecessary applications.
Quick Answer: What Are the Main HELOC Requirements?
Most lenders evaluate several factors before approving a HELOC:
| Requirement | What the lender may evaluate |
|---|---|
| Home equity | How much of your home you own |
| Credit score | Your credit risk and payment history |
| Credit history | Late payments, collections, bankruptcies and account history |
| Debt-to-income ratio | Your monthly debt compared with income |
| Income | Current and historical ability to repay |
| Property | Value, condition, location and insurance |
| Existing mortgage | Current balance and payment |
| Loan-to-value / CLTV | Total debt secured by the property compared with its value |
| Documentation | Income, mortgage, property and financial records |
| Repayment ability | Whether the new HELOC payment fits your finances |
The exact thresholds depend on the lender and the HELOC program.
For example, U.S. Bank currently says applicants need a FICO score of 660 or higher and also evaluates home equity, credit history, DTI and income history. Bank of America currently lists a 660+ minimum credit score and at least 15% equity for its HELOC. These are lender-specific requirements, not universal industry rules.
1. You Need Sufficient Home Equity
Home equity is one of the most important HELOC requirements.
Your equity is generally:
Home Value − Mortgage Balance = Home Equity
Example
Suppose your home is worth:
$400,000
Your remaining mortgage balance is:
$250,000
Your estimated equity is:
$400,000 − $250,000 = $150,000
That means you have approximately $150,000 in equity before considering other liens or lender-specific calculations.
However, having $150,000 in equity does not mean a lender will automatically give you a $150,000 HELOC.
The lender also considers how much total debt it is willing to allow against the property’s value.
2. Your Credit Score Matters
Your credit score can have a significant impact on whether you qualify and what terms you receive.
However, there is no universal minimum FICO score for every HELOC.
For example:
- U.S. Bank currently lists 660+ FICO as a qualification requirement.
- Bank of America currently lists 660+ for its HELOC.
- Other lenders may have different minimums or additional requirements.
A higher score can also improve your chances of receiving more favorable pricing, depending on the lender.
Credit score example
| Credit Score | General Position |
|---|---|
| 800+ | Very strong credit profile |
| 740–799 | Strong |
| 670–739 | Generally considered good |
| 620–669 | May face more restrictions |
| Below 620 | HELOC options may become more limited |
This table is a general credit-score framework, not a HELOC approval chart.
A lender may approve or deny an application based on the complete financial profile rather than the score alone.
3. Your Debt-to-Income Ratio Can Affect Approval
Debt-to-income ratio, or DTI, compares your monthly debt obligations with your gross monthly income.
The basic formula is:
DTI = Monthly Debt Payments ÷ Gross Monthly Income × 100
Illustrative example
Suppose you earn:
$8,000 per month
Your qualifying monthly debt payments are:
- Mortgage: $2,000
- Car loan: $500
- Credit cards: $300
- Student loan: $200
Total debt payments:
$3,000
Your DTI would be:
$3,000 ÷ $8,000 × 100 = 37.5%
A lender then evaluates whether that debt burden is acceptable under its underwriting standards.
There is no single DTI cutoff that applies to every HELOC.
4. You Need Verifiable Income
Lenders need evidence that you can repay the HELOC.
Depending on your situation, the lender may request:
- Recent pay stubs
- W-2 forms
- Tax returns
- Bank statements
- Employment information
- Proof of other income
- Self-employment documentation
- Information about existing debts
Self-employed applicants may face additional documentation requirements because lenders need to verify income and its stability.
U.S. Bank, for example, says HELOC applicants should be prepared to provide household income information, Social Security number, outstanding balances, mortgage statement, property tax bill and homeowners insurance information.
5. Your Existing Mortgage Balance Matters
The amount you still owe on your first mortgage affects how much equity is available.
Consider two homeowners with identical $500,000 properties.
Homeowner A
Home value: $500,000
Mortgage balance: $150,000
Estimated equity:
$350,000
Homeowner B
Home value: $500,000
Mortgage balance: $400,000
Estimated equity:
$100,000
Even though both homes are worth the same amount, Homeowner A has substantially more equity available.
The lender’s CLTV limits and other underwriting rules will determine how much additional borrowing may be possible.
6. Your Combined Loan-to-Value Ratio Matters
Combined loan-to-value ratio, or CLTV, considers the total debt secured by your property compared with its value.
A simplified formula is:
CLTV = Total Mortgage Debt ÷ Home Value × 100
Example
Home value:
$500,000
Existing mortgage:
$300,000
Proposed HELOC:
$75,000
Total secured debt:
$375,000
CLTV:
$375,000 ÷ $500,000 × 100 = 75%
A lender may have a maximum CLTV it is willing to accept.
But this is another area where you should avoid assuming that every lender uses the same threshold.
Your credit score, property, income, loan amount and other factors may also affect the lender’s decision.
7. Your Property Must Meet the Lender’s Requirements
The property securing the HELOC is important because it serves as collateral.
A lender may evaluate:
- Property value
- Property type
- Location
- Existing liens
- Homeowners insurance
- Property taxes
- Ownership status
- Current mortgage
- Condition of the property
The lender may require an appraisal, automated valuation, or another method of determining property value.
If the lender determines that your home is worth less than expected, the amount you can borrow may be reduced.
The CFPB notes that if the value of your home decreases significantly, a lender may restrict additional borrowing under an existing HELOC in certain circumstances.
8. You Must Have a Reasonable Ability to Repay
A HELOC isn’t simply approved based on your home equity.
The lender also needs to assess your ability to make payments.
This can include considering:
- Income
- Existing debt
- Credit history
- Monthly obligations
- HELOC payment
- Other mortgage-related obligations
Federal lending rules require consideration of repayment-related factors in applicable transactions, including income/assets, debt obligations, DTI or residual income, and credit history. The regulations do not establish one universal DTI percentage for every situation.
This is why someone with substantial home equity can still be denied a HELOC.
9. You May Need Property and Financial Documents
Preparing your documents before applying can make the process easier.
A lender may request:
Income documents
- Pay stubs
- W-2s
- Tax returns
- Bank statements
- Other income documentation
Property documents
- Mortgage statement
- Property tax information
- Homeowners insurance
- Property address
- Ownership information
Debt information
- Credit card balances
- Auto loans
- Student loans
- Other mortgages
- Other monthly obligations
Requirements vary by lender and borrower.
10. Your Credit History Is More Than Your Credit Score
Two people can have the same credit score but receive different lending decisions.
A lender may consider:
- Payment history
- Length of credit history
- Recent credit activity
- Collections
- Charge-offs
- Bankruptcies
- Existing debt
- Credit utilization
- Other factors in its underwriting model
Federal lending rules recognize credit history as a relevant factor and explain that it can include the number and age of credit lines, payment history, judgments, collections and bankruptcies.
So don’t think of the HELOC process as:
Credit score → approval
It’s closer to:
Credit + equity + income + debt + property + repayment ability → underwriting decision
HELOC Requirements Example: Can You Qualify?
Let’s use an illustrative scenario.
Homeowner profile
- Home value: $450,000
- Mortgage balance: $250,000
- Credit score: 735
- Gross monthly income: $8,000
- Existing monthly debt payments: $2,500
- Desired HELOC: $75,000
Step 1: Calculate equity
$450,000 − $250,000 = $200,000
Step 2: Calculate total secured debt
$250,000 + $75,000 = $325,000
Step 3: Calculate CLTV
$325,000 ÷ $450,000 = 72.2%
Step 4: Calculate existing DTI
$2,500 ÷ $8,000 = 31.25%
This applicant appears to have several characteristics that could support a HELOC application: meaningful equity, a relatively strong credit score and manageable existing debt in this simplified example.
But this does not mean the applicant is guaranteed approval.
The lender could use additional requirements involving income verification, property valuation, credit history, CLTV, loan amount and other factors.
What Credit Score Do You Need for a HELOC?
There is no single credit-score requirement across all HELOC lenders.
Some major lenders currently publish minimums around 660.
For example:
| Lender | Published requirement/example |
|---|---|
| U.S. Bank | FICO 660+ |
| Bank of America | Credit score 660+ |
| Other lenders | Requirements vary |
U.S. Bank also states that credit score and history, home equity, DTI and income history are considered. Bank of America states that applicants need at least 15% equity in the home in addition to its 660+ credit-score requirement.
Don’t interpret 660 as a universal HELOC cutoff.
Can You Get a HELOC With a 600 Credit Score?
It may be possible with some lenders or circumstances, but options can be more limited.
A 600 credit score is below the currently published 660 minimums of the U.S. Bank and Bank of America HELOC programs referenced above.
A lower score may make the application more difficult because lenders also evaluate credit history, debt, income, equity and property.
If your score is around 600, consider improving your credit profile and comparing lenders rather than submitting applications indiscriminately.
How Much Equity Do You Need for a HELOC?
There is no universal equity percentage for every lender.
Some lenders publish specific minimums.
For example, Bank of America currently states that borrowers need at least 15% equity for its HELOC.
Other lenders can have different requirements.
Your usable borrowing capacity may also be affected by:
- Home value
- Mortgage balance
- Proposed HELOC amount
- CLTV limit
- Credit score
- Income
- DTI
- Property type
So having 20% equity doesn’t automatically mean you can borrow the remaining 80%.
How Much Can You Borrow With a HELOC?
The amount depends on the lender’s maximum CLTV, your home value, existing mortgage and financial profile.
A simplified calculation can help illustrate the concept.
Suppose:
Home value = $500,000
Lender’s hypothetical maximum CLTV = 80%
Maximum secured debt:
$500,000 × 80% = $400,000
Existing mortgage:
$300,000
Potential HELOC capacity before other lender adjustments:
$400,000 − $300,000 = $100,000
This is only an illustration.
The actual amount a lender offers could be lower because of credit, income, DTI, property type, loan minimums, underwriting or other factors.
HELOC vs. Home Equity Loan
A HELOC and home equity loan both use your home as collateral, but they work differently.
| Feature | HELOC | Home Equity Loan |
|---|---|---|
| Funding | Revolving line | Lump sum |
| Borrow repeatedly | Yes, during draw period | No |
| Interest rate | Usually variable | Often fixed |
| Payment | Can change | Generally more predictable |
| Best suited for | Expenses spread over time | One defined large expense |
| Home as collateral | Yes | Yes |
| Risk of foreclosure if unpaid | Yes | Yes |
The CFPB explains that a HELOC allows repeated borrowing up to a credit limit, while a home equity loan provides a specific amount as a lump sum.
HELOC Requirements vs. Personal Loan Requirements
A HELOC is secured by your home, while a typical personal loan is unsecured.
| Factor | HELOC | Personal Loan |
|---|---|---|
| Collateral | Home | Usually none |
| Home equity required | Yes | No |
| Credit evaluation | Yes | Yes |
| Income verification | Usually | Usually |
| Property valuation | May be required | No |
| Foreclosure risk | Possible if you cannot repay | No home collateral in a typical unsecured loan |
| Borrowing structure | Revolving | Usually fixed amount |
| Interest rate | Usually variable | Often fixed |
A HELOC may offer a lower interest rate than some unsecured borrowing because the lender has collateral, but the trade-off is that your home is at risk if you cannot repay.
What Documents Should You Prepare for a HELOC?
Before applying, consider preparing:
Personal information
- Government-issued identification
- Social Security number
- Current address
Income
- Recent pay stubs
- W-2 forms
- Tax returns if requested
- Other income documentation
Property
- Mortgage statement
- Property tax information
- Homeowners insurance
- Property address
Financial information
- Bank statements
- Credit obligations
- Existing loans
- Credit card balances
Having these documents ready can reduce delays during the application process.
Does a HELOC Affect Your Credit Score?
Applying for a HELOC can involve a credit inquiry, depending on the lender and stage of the process.
Once opened, the HELOC also becomes part of your credit profile.
Your payment behavior can affect your credit history.
For example:
On-time payments → positive payment history
Late payments → potential negative credit impact
Your outstanding HELOC balance can also affect how lenders view your overall debt.
Does a HELOC Have Closing Costs?
It can.
The CFPB says HELOC lenders may charge fees such as:
- Application fees
- Origination fees
- Appraisal fees
- Title fees
- Closing costs
- Annual or membership fees
- Inactivity fees
- Cancellation fees
- Conversion fees
The exact fees depend on the HELOC plan.
Always compare the total cost rather than looking only at the advertised interest rate.
What Happens After You Get a HELOC?
A HELOC usually has two major stages:
Draw period
You can borrow from the available credit line during the draw period.
For example, a lender might provide a 10-year draw period, although terms vary.
Repayment period
After the draw period ends, you generally can no longer borrow from the line and must repay the outstanding balance.
The CFPB notes that payments can become significantly higher once repayment begins, depending on the plan. HELOCs also usually have variable rates, meaning payments can change.
Why a HELOC Can Become Risky
The biggest issue is simple:
Your home secures the debt.
If you cannot repay the HELOC, you could put your home at risk.
The CFPB specifically warns that failure to keep up with HELOC payments can result in losing your home.
Other risks include:
- Variable interest rates
- Higher payments during repayment
- Fees
- Reduced borrowing availability
- Falling home values
- Taking on too much debt
A HELOC should therefore not be treated like free cash.
7 Mistakes to Avoid When Applying for a HELOC
1. Assuming your equity equals your borrowing limit
Your lender will apply its own CLTV and underwriting rules.
2. Applying based only on your credit score
Credit score is only one part of the decision.
3. Ignoring DTI
A large amount of existing debt can reduce your borrowing capacity.
4. Forgetting variable rates
Many HELOCs have adjustable rates.
5. Looking only at the initial payment
Your payment may change, particularly when the draw period ends.
6. Ignoring fees
Application, appraisal, annual, cancellation and other fees can affect the total cost.
7. Borrowing more than you need
Because your home is collateral, borrowing should be approached carefully.
HELOC Approval Checklist
Before applying, check:
- Estimate your current home value
- Calculate your mortgage balance
- Estimate your home equity
- Check your credit reports
- Review your credit score
- Calculate your DTI
- Gather income documents
- Gather mortgage documents
- Check property tax status
- Confirm homeowners insurance
- Compare lender CLTV requirements
- Compare interest rates
- Compare fees
- Understand the draw period
- Understand the repayment period
- Estimate the payment after the draw period
- Make sure the payment fits your budget
Frequently Asked Questions
What are the basic HELOC requirements?
Most lenders consider home equity, credit history, credit score, income, DTI, existing mortgage debt, property value and ability to repay. Specific requirements vary by lender.
What is the minimum credit score for a HELOC?
There is no universal minimum. Some major lenders currently publish minimums around 660. U.S. Bank and Bank of America, for example, currently list 660 as a minimum for their respective HELOC programs.
How much equity do I need for a HELOC?
The requirement varies. Bank of America currently lists at least 15% equity for its HELOC, while other lenders can use different requirements. Your credit, DTI, property and requested credit line can also affect eligibility.
Can I get a HELOC with 20% equity?
Possibly. Whether 20% equity is enough depends on the lender’s CLTV limit and your complete financial profile. Having 20% equity does not guarantee approval.
Can I get a HELOC with a 600 credit score?
It may be difficult with lenders whose published minimum is 660 or higher. You may need to improve your credit profile or find a lender with different underwriting standards.
Does a HELOC require income verification?
Generally, lenders need information that allows them to assess your ability to repay. The exact documents vary by lender and borrower.
Does a HELOC require an appraisal?
It may. Lenders need to determine the property’s value, and the valuation method can vary. Some may use an appraisal while others may use automated valuation methods or other approaches.
Is a HELOC a second mortgage?
If you already have a mortgage, a HELOC is generally a second mortgage or junior lien secured by the same home. The CFPB explains that a HELOC can be a second mortgage when you already have a first mortgage.
Can I use a HELOC for anything?
A HELOC generally provides flexible access to borrowed funds, but you should understand your lender’s terms and any applicable tax rules. Using home equity for discretionary spending can create significant risk because your home secures the debt.
Is a HELOC better than a home equity loan?
It depends on your goal. A HELOC provides a revolving line that you can draw from over time, while a home equity loan generally provides a lump sum. A HELOC may be useful when expenses occur over time; a home equity loan may be easier to budget when you know exactly how much you need.
Final Takeaway
HELOC requirements are based on much more than your credit score.
Lenders typically look at:
Home equity + credit + income + DTI + property + existing debt + repayment ability
There is no universal HELOC approval formula.
For example, major lenders currently publish credit-score requirements around 660, but their other requirements and underwriting standards differ. Your best approach is to calculate your equity and DTI, review your credit profile, prepare your documents, and compare multiple lenders before committing.
Most importantly, remember that a HELOC is secured by your home. If you cannot repay the debt, your home can be at risk.
Why Maintain Market Is Different
Maintain Market focuses on the practical side of financial decisions.
Instead of telling readers that they simply need a certain credit score to get a HELOC, this guide breaks approval into the factors lenders actually evaluate: equity, CLTV, credit, income, DTI, property and repayment ability.
The goal is to help readers understand why they may qualify, how much they might potentially borrow, and what could cause an application to be denied.
References
- CFPB — What Is a Home Equity Line of Credit (HELOC)?
- CFPB — HELOC vs. Home Equity Loan
- CFPB — HELOC Fees
- CFPB — Regulation Z: Home Equity Plans
- U.S. Bank — Home Equity Line of Credit
- U.S. Bank — How to Get a HELOC
- Bank of America — Home Equity Line of Credit
Editorial Review
Reviewed for U.S. HELOC terminology, qualification factors, credit requirements, equity calculations, CLTV, DTI, fees, repayment periods and lender-specific requirements.
Lender requirements change and vary by state, property, borrower and loan program. Any lender-specific requirement in this article should be treated as an example rather than a universal industry standard.