Welcome to Maintain Market; we post finance, investment, insurance, and loan blogs. In this blog, we will talk about How to Invest in 401k Wisely.

A 401(k) plan is one of the most powerful wealth-building tools available to American workers. Yet many people contribute money without knowing how to invest inside their 401(k) wisely. Poor choices can reduce retirement wealth by hundreds of thousands of dollars, while smart strategies can help you retire comfortably.
This guide will explain how a 401(k) works, investment options, asset allocation, risk strategies, common mistakes, and expert tips to maximize your retirement savings.
What Is a 401(k)?
A 401(k) is an employer-sponsored retirement savings plan that allows you to invest pre-tax or after-tax money for retirement.
Key Benefits:
✔ Tax advantages
✔ Employer matching
✔ Automatic investing
✔ Long-term compounding
Why Investing Wisely Matters
Two people saving the same amount can end up with very different retirement balances based on investment choices.
Example:
$500/month for 30 years
6% return → $502,000
9% return → $917,000
Investment strategy makes a huge difference.
Types of 401(k) Plans
| Type | Tax Benefit |
|---|---|
| Traditional 401(k) | Tax-deferred |
| Roth 401(k) | Tax-free withdrawals |
Choose based on expected retirement tax bracket.
Step 1: Get the Employer Match First
If your employer matches contributions, that’s free money. Always contribute enough to get the full match.
Step 2: Choose the Right Asset Allocation
General rule:
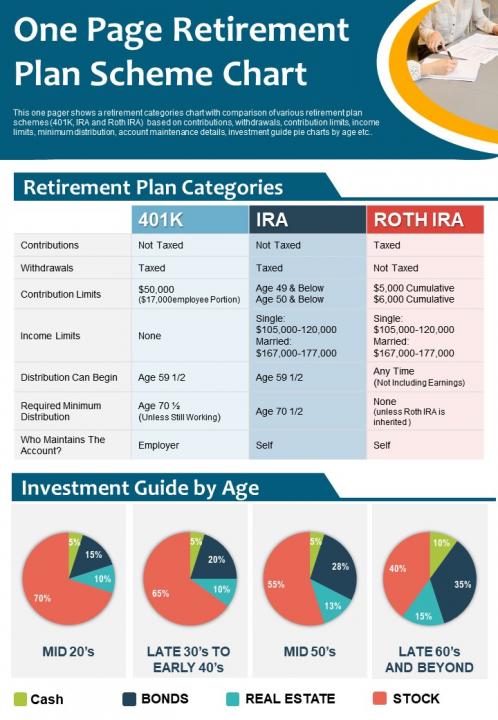
| Age | Stocks | Bonds |
|---|---|---|
| 20s | 80–90% | 10–20% |
| 30s | 70–80% | 20–30% |
| 40s | 60–70% | 30–40% |
| 50s | 50–60% | 40–50% |
Step 3: Use Low-Cost Index Funds
Index funds provide:
✔ Diversification
✔ Low fees
✔ Strong long-term returns
Step 4: Diversify Properly
Mix of:
- U.S. stocks
- International stocks
- Bonds
Avoid putting all money in company stock.
Step 5: Rebalance Annually
Market movements change allocations. Rebalance once a year.
Common 401(k) Mistakes -How to Invest in 401k Wisely
❌ Ignoring fees
❌ Too much cash
❌ Not increasing contributions
❌ Early withdrawals
Market Crash Strategy
Do not panic sell. Continue contributions during downturns.
Target-Date Funds (Simple Option)
Automatically adjust asset allocation as you age.
How Much Should You Contribute?
Aim for 15% of income including employer match.
401(k) vs IRA
401(k) = employer plan
IRA = personal retirement account
Both can be used.
Compounding Example
$10,000 at 8% for 30 years → $100,000+
How Fees Can Secretly Reduce Your 401(k) Growth
Even a small fee difference matters.
| Annual Fee | Balance After 30 Years ($500/mo @ 8%) |
|---|---|
| 0.5% | $745,000 |
| 1.5% | $635,000 |
A 1% fee difference can cost over $100,000. Always choose low-expense funds.
The “Set It and Grow It” Mindset
401(k) investing works best when you:
✔ Automate contributions
✔ Avoid frequent changes
✔ Let compounding work
Emotional decisions often reduce returns.
Contribution Increase Strategy
Each time you get a raise, increase your contribution by 1–2%. Over time this builds wealth without feeling painful.
Roth vs Traditional 401(k): When to Choose
| Situation | Better Choice |
|---|---|
| Lower income now | Roth |
| High income now | Traditional |
| Expect higher taxes later | Roth |
| Expect lower taxes later | Traditional |
Diversification Inside a 401(k)
A well-balanced portfolio often includes:
- Large-cap funds
- Small-cap funds
- International funds
- Bond funds
Avoid concentrating in one fund.
Market Downturn Advantage
When markets drop:
✔ Your contributions buy more shares
✔ Long-term growth potential increases
This is called dollar-cost averaging advantage.
401(k) Contribution Limits
For 2026 (approx):
- Under 50: ~$23,000/year
- 50+: Extra catch-up contribution
Maxing contributions accelerates retirement readiness.
Loans From 401(k) — Should You?
Generally not recommended because:
❌ Stops growth
❌ Risk if job changes
❌ Tax penalties if not repaid
Early Withdrawal Penalties
Withdrawing before age 59½ usually triggers:
- Income tax
- 10% penalty
Avoid unless absolutely necessary.
Rebalancing During Market Swings
Markets shift allocation over time. Annual rebalancing keeps risk level appropriate.
Psychological Rule: Ignore Daily Market News
Retirement investing is long-term. Daily headlines create unnecessary fear.
Target-Date Fund vs DIY Investing
| Feature | Target-Date | DIY |
|---|---|---|
| Simplicity | High | Medium |
| Control | Low | High |
| Fees | Moderate | Low |
Example Retirement Scenario
Saving $600/month for 35 years at 8% = $1.1 million
Consistency matters more than timing.
How Inflation Impacts Your 401(k)
Inflation reduces purchasing power over time. If your investments grow at 6% but inflation averages 3%, your real return is only 3%.
That’s why 401(k) portfolios need:
✔ Stocks for growth
✔ Diversification
✔ Long-term compounding
Keeping too much in cash or bonds may feel safe but can lose value in real terms.
The Rule of 72 for Retirement Growth
Divide 72 by your expected return to see how long your money takes to double.
| Return | Years to Double |
|---|---|
| 6% | 12 years |
| 8% | 9 years |
| 10% | 7 years |
Higher long-term returns dramatically increase retirement wealth.
How Often Should You Check Your 401(k)?
✔ Review once or twice a year
❌ Checking daily causes emotional decisions
Long-term investing works best with patience.
Employer Stock in 401(k): Is It Safe?
While investing in your employer may seem safe, too much concentration increases risk. If company stock falls and you lose your job, both income and retirement savings suffer.
Experts suggest:
✔ Keep employer stock under 10–15%
Sequence of Returns Risk (Near Retirement)
Market drops just before retirement can reduce income potential.
Solution:
- Shift more to bonds as retirement approaches
- Keep emergency funds
- Avoid panic selling
Safe Withdrawal Strategy in Retirement
The 4% rule helps ensure savings last.
Example:
$1,000,000 → $40,000/year income.
Adjust withdrawals during market downturns.
What Happens to Your 401(k) When You Change Jobs?
Options include:
- Leave it in old plan
- Roll over to new employer plan
- Transfer to IRA
Rolling into IRA often provides more investment choices.
Required Minimum Distributions (RMDs)
After a certain age, the IRS requires withdrawals from traditional 401(k)s. Planning ahead reduces tax surprises.
Why Staying Invested Matters
Missing just the best 10 market days over decades can cut returns dramatically. Staying invested improves long-term outcomes.
Behavioral Discipline = Bigger Retirement
Consistent investors outperform emotional traders. Avoid reacting to short-term market swings.
Example Portfolio for a 35-Year-Old
- 60% U.S. index fund
- 20% international fund
- 15% bond fund
- 5% small-cap fund
Balanced for growth and stability.
Emergency Fund Before Investing More
Always keep 3–6 months of expenses in savings so you don’t need early withdrawals.
Frequently Asked Questions (FAQs) About Investing in a 401(k)
Q1. What is the best way to invest in a 401(k)?
The best approach is to:
Contribute enough to get the employer match
Choose low-cost index funds
Diversify across stocks and bonds
Rebalance annually
Q2. How much should I contribute to my 401(k)?
A common recommendation is 10–15% of your salary, including employer match. The more you contribute early, the more compounding works in your favor.
Q3. Should I choose Roth or Traditional 401(k)?
a) Choose Roth if you expect higher taxes in retirement.
b) Choose Traditional if you want tax savings now.
Q4. Is it risky to invest in stocks inside a 401(k)?
Stocks fluctuate short term but historically provide higher long-term growth. Younger investors can hold more stocks, while older investors should balance with bonds.
Q5. What funds should I pick in my 401(k)?
Good options include:
S&P 500 index funds
Total stock market funds
Bond index funds
Target-date funds
Q6. How often should I rebalance my 401(k)?
Rebalancing your 401(k) once a year is often enough to keep your investments aligned with your target asset allocation. You can also rebalance when market movements significantly change your portfolio’s risk level.
Q7. Can I lose money in a 401(k)?
Yes, your 401(k) can lose value because investments such as stocks and mutual funds fluctuate with the market. Staying invested for the long term may help manage short-term volatility, but losses are still possible.
Q8. What happens if I withdraw early?
Withdrawals from a traditional 401(k) before age 59½ generally incur ordinary income tax and may include an additional 10% early-withdrawal penalty. Certain exceptions may apply depending on your circumstances.
Q9. Should I invest all my 401(k) in employer stock?
No, investing all your retirement savings in employer stock can create concentration risk. If your employer’s business struggles, both your income and investments could be affected.
Q10. Are target-date funds good?
Target-date funds automatically adjust their investment mix as your expected retirement date approaches. They can be a convenient option for beginners, although fees, investment strategy, and risk level should be reviewed. ideal for beginners.
Q11. What is the biggest mistake in 401(k) investing?
Common mistakes include contributing too little, ignoring investment fees, and selling investments in panic during market downturns. Failing to take advantage of available employer matching contributions can also reduce your retirement savings.
Q12. How does compounding help in a 401(k)?
Compounding allows your investment earnings to generate additional earnings over time. The longer you remain invested and continue contributing, the more opportunity your savings have to grow.
Q13. Can I move my 401(k) when changing jobs?
YYes, you may be able to roll your old 401(k) into your new employer’s retirement plan or an eligible IRA. You might also be able to leave the money in your previous employer’s plan, depending on its rules.
Q14. What is a good return for a 401(k)?
A good return depends on your investments, fees, time horizon, and market conditions. Stock-heavy portfolios have historically achieved strong long-term returns, but 7–10% annually is not guaranteed, and actual results can vary significantly.
Q15. How can I grow my 401(k) faster?
Increase contributions regularly
Choose low-fee funds
Stay invested during downturns
Reinvest dividends
Final Thoughts
Investing wisely in a 401(k) means:
✔ Get match
✔ Choose low-cost funds
✔ Diversify
✔ Stay consistent
Read: Safest Investment With High Returns USA
Also read: Best Passive Income Investments USA