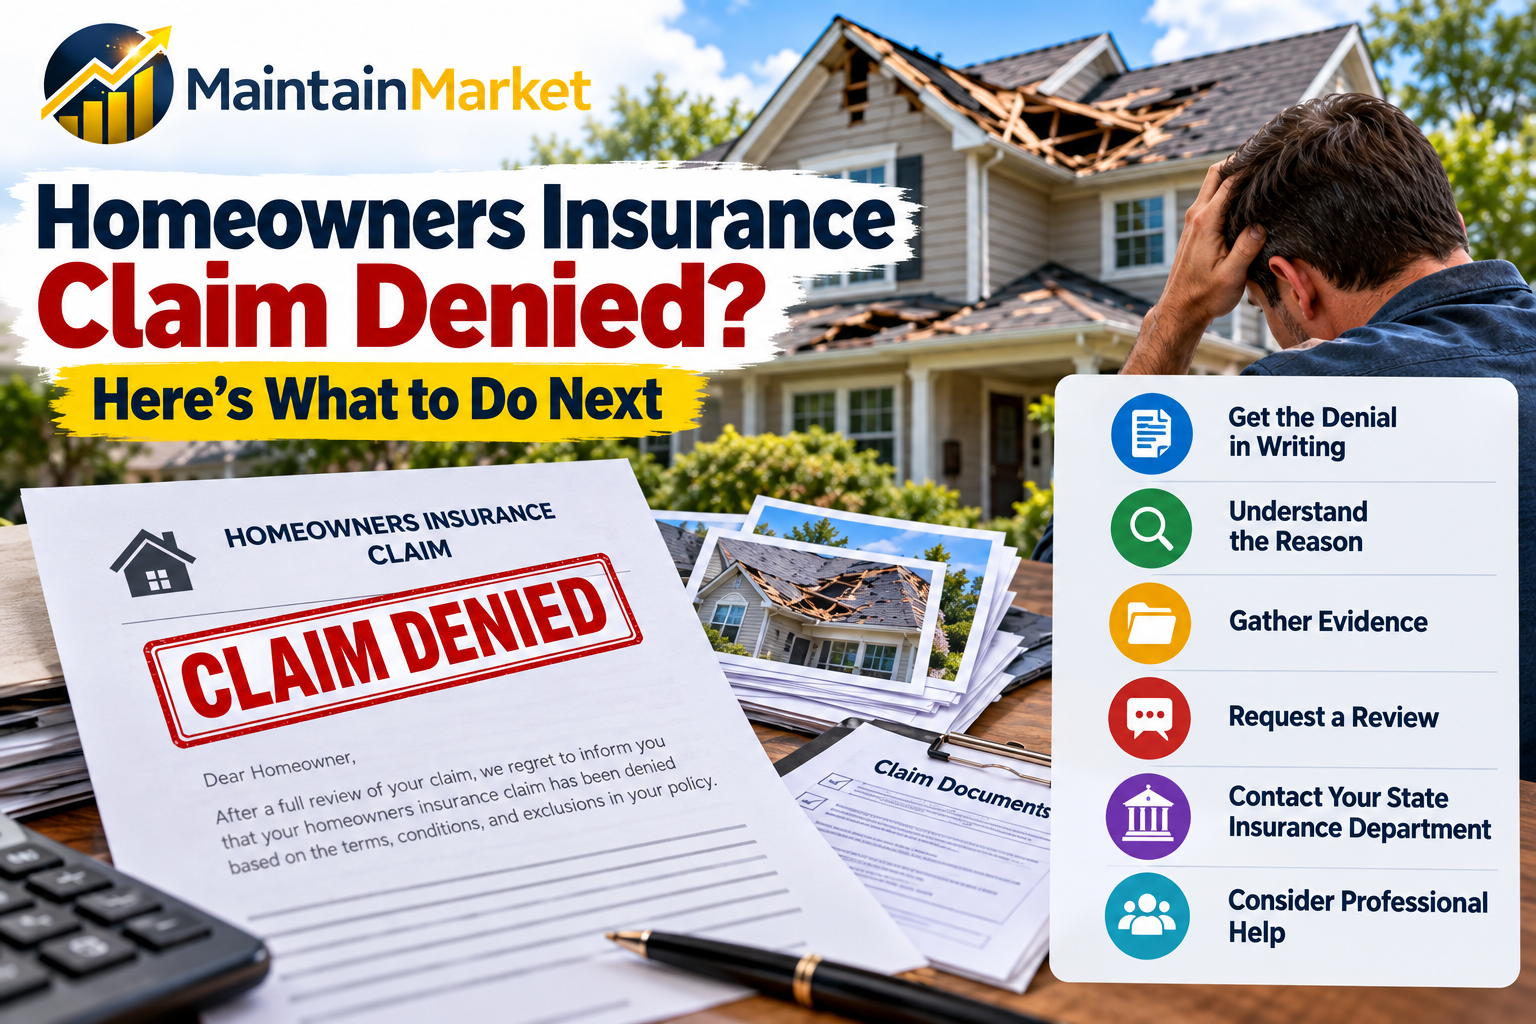
Homeowners insurance claim denied is a stressful message to receive, especially after your home has already been damaged. But a denied claim does not always mean the matter is over. The first thing to do is understand why the insurance company denied the claim, check the exact wording in your policy, gather your records, and ask the insurer to explain its decision in writing.
Quick Answer: What Should You Do If Your Homeowners Insurance Claim Is Denied?
If your homeowners insurance claim is denied, do not immediately assume you have no options.
Start with these steps:
- Ask for the denial in writing.
- Find the exact reason for the denial.
- Read the part of your policy related to the claim.
- Check whether the insurer listed a specific exclusion.
- Gather photos, receipts, repair records, and other proof.
- Ask the insurer to review the claim again if you believe something was missed.
- Keep records of every call, email, and letter.
- Consider getting another professional opinion when the cause or amount of damage is disputed.
- Contact your state’s insurance department if you cannot resolve the issue.
- Consider legal advice for a large or complex dispute.
The NAIC says that when an insurer denies any part of a homeowners claim, you should ask for the denial in writing, keep your paperwork, and contact the insurance company if you disagree. If you still cannot resolve the issue, your state insurance department may be able to help.
1. Why Was My Homeowners Insurance Claim Denied?
There is no single reason why a homeowners claim gets denied.
An insurer may deny a claim because it believes:
- The damage was caused by something your policy does not cover
- An exclusion applies
- The damage happened before the policy started
- The damage was caused by normal wear and tear
- The loss was not reported according to the policy rules
- There is not enough proof of the damage
- The cost of the covered damage is below the deductible
- The policy does not provide enough coverage for the type of loss
- The insurer believes the damage was caused by poor maintenance
- Important information about the claim is missing
The exact reason should come from your insurer.
Do not rely only on a phone conversation. Ask for a written explanation that tells you why the claim was denied and what part of the policy the insurer used to make that decision.
NAIC claims standards say denied claims should be handled according to the policy and state law, and denial notices may need to identify the policy provision or exclusion used as the basis for the denial.
2. Ask for the Denial in Writing
This should be one of your first steps.
If an insurance representative tells you over the phone that your claim is denied, ask:
“Can you please send me the denial and the reason for the decision in writing?”
The written letter can help you understand:
- What the insurer believes happened
- Why it says the loss is not covered
- Which policy section it relied on
- Whether the claim was fully or partly denied
- What you can do if you disagree
Keep the letter with your policy and other claim records.
The NAIC specifically recommends asking for a denial in writing when you disagree with a homeowners claim decision.
3. Find the Exact Reason for the Denial
Do not stop at a sentence such as:
“Your claim is not covered.”
You need to understand why.
For example, an insurer might say:
“The damage was caused by wear and tear.”
That is very different from:
“The damage was caused by sudden water damage, which is excluded under Section X of your policy.”
The difference matters because you need to compare the insurer’s reason with your actual policy.
Look for words such as:
- Excluded
- Wear and tear
- Maintenance
- Neglect
- Water damage
- Flood
- Mold
- Earth movement
- Policy limit
- Deductible
- Late notice
- Pre-existing damage
Write down the exact reason given by the insurer.
4. Read Your Homeowners Insurance Policy
This is one of the most important steps.
Your policy is the contract that explains your coverage.
Look at:
Coverage
What types of damage does your policy cover?
Exclusions
What types of damage does your policy say it does not cover?
Deductible
How much do you have to pay before insurance pays its share?
Limits
What is the maximum amount the insurer will pay for a particular type of loss?
Conditions
Are there rules about reporting the loss, protecting the property, or providing documents?
Do not read only the first few pages.
The reason for the denial may be buried in the exclusions or conditions section.
5. Check Whether the Cause of Damage Is Covered
Homeowners insurance usually does not simply cover all damage to a home.
Coverage often depends on what caused the damage.
For example, your policy may cover certain sudden events but exclude other causes.
Consider these examples:
Example 1: Storm damage
A strong windstorm damages your roof.
Depending on the policy, wind damage may be covered.
Example 2: Flood
Water enters the home from outside because of flooding.
A standard homeowners policy generally does not cover flood damage, and separate flood insurance may be needed.
Example 3: Long-term leak
A pipe has been slowly leaking behind a wall for years.
The insurer may treat the damage differently from a sudden pipe break.
This is why the cause of the damage is so important when a claim is denied.
6. Check Whether Wear and Tear Is the Issue
One common problem is the difference between sudden damage and damage that develops over time.
For example, imagine a roof has become old and worn over many years.
Eventually, water enters through the worn roof.
An insurer may say the underlying roof problem is maintenance or wear and tear rather than a sudden covered event.
Now consider a different situation.
A severe storm suddenly damages the roof, and rain enters through the new opening.
The insurer may look at that situation differently.
The exact result depends on the policy, the cause of loss, and the facts.
If the insurer says “wear and tear,” ask:
- What part of the damage does the insurer believe is wear and tear?
- What evidence supports that finding?
- Which policy section applies?
- Is any part of the damage covered?
That can help you understand whether the entire claim was denied or only part of it.
7. Gather Evidence Before Asking for a Review
If you believe the claim was denied incorrectly, gather as much useful evidence as you can.
This may include:
- Photos of the damage
- Videos
- Repair estimates
- Contractor reports
- Receipts
- Previous inspection reports
- Maintenance records
- Weather records
- Police reports, when relevant
- Emails with your insurer
- Letters from the insurance company
- Your insurance policy
- Previous repair invoices
The goal is simple:
Show what happened, when it happened, and what damage it caused.
The NAIC recommends keeping records and documentation related to a homeowners claim, including photos and information about damaged property.
8. Ask the Insurance Company to Review the Claim Again
If you believe the insurer missed something, you can ask the company to review the claim again.
Write a clear letter or email.
Explain:
- Your claim number
- What happened
- Why you disagree with the denial
- What part of the policy you believe applies
- What evidence supports your position
- What documents you are attaching
Keep the letter focused on facts.
For example:
“The denial states that the roof damage was caused by wear and tear. However, the attached inspection report states that the roof was damaged by the storm on June 10. Please review the claim again based on the attached report and the policy coverage for storm damage.”
This is much more useful than simply saying:
“I don’t agree with the denial.”
The NAIC advises policyholders who disagree with a claim decision to explain why they believe the decision is not correct and provide supporting information.
9. Contact Your State Insurance Department
If you have tried to resolve the problem with your insurance company and still believe the claim was handled incorrectly, your state insurance department may be able to help.
State insurance departments regulate insurance companies within their states.
They can handle consumer complaints involving issues such as:
- Claim denials
- Claim delays
- Failure to honor a policy
- Problems with communication
- Possible violations of state insurance rules
The NAIC says you should generally try to resolve the issue with the insurer first. If you are still not satisfied, you can contact your state insurance department.
You can find your state’s insurance department through the NAIC directory.
10. Consider Professional Help for a Large Dispute
Some insurance disputes are simple.
Others can involve a large amount of money or a disagreement about the cause of serious property damage.
For a major claim, you may consider speaking with:
- A licensed public adjuster
- A property damage expert
- A licensed contractor
- An insurance attorney
A public adjuster can help review the damage and prepare a claim, but they charge a fee, and rules for public adjusters vary by state.
An attorney may be useful when there is a serious dispute about coverage, a large financial loss, or possible legal issues.
Before hiring anyone, understand their fees and what they will actually do for you.
10 Common Reasons Homeowners Insurance Claims Are Denied
Here are some of the most common issues that can lead to a denied or partly denied claim.
| Reason | What It Means |
|---|---|
| Excluded damage | The policy does not cover the cause of the loss |
| Wear and tear | Damage developed through normal aging or use |
| Poor maintenance | The insurer believes the homeowner failed to maintain the property |
| Flood | Standard homeowners insurance generally does not cover flood damage |
| Policy limit | The loss may be higher than the applicable coverage limit |
| Deductible | The damage may not exceed the deductible |
| Lack of proof | The insurer may not have enough evidence of the loss |
| Late reporting | The claim may have been reported outside the policy or legal time limits |
| Pre-existing damage | The damage may have existed before the covered event |
| Incorrect information | The insurer may question information given during the claim |
These are general examples. The reason for a particular denial must be checked against the actual policy and the facts of the loss.
Can a Homeowners Insurance Claim Be Denied After an Inspection?
Yes.
An insurance company may inspect your home before deciding whether to pay a claim.
The inspection can help the insurer determine:
- What caused the damage
- How old the damage appears to be
- Whether the damage is related to a covered event
- Whether maintenance problems were involved
- How much repair may cost
The insurer may then approve the claim, partly approve it, or deny it.
If you disagree with the inspection findings, ask for the findings in writing and consider getting an independent inspection or repair report.
What If the Insurance Company Says the Damage Was Pre-Existing?
A pre-existing damage issue means the insurer believes the problem existed before the event you reported.
For example:
You report roof damage after a storm.
The insurer says the roof already had old damage before the storm.
In that situation, evidence can be very important.
Useful records may include:
- Photos taken before the storm
- Previous inspection reports
- Roof repair invoices
- Maintenance records
- Contractor reports
- Home inspection documents
If you can show the condition of the property before the event, that information may help explain what changed.
What If Only Part of My Claim Was Denied?
A claim does not always have to be completely denied.
An insurer may agree that some damage is covered but disagree about other damage.
For example:
Your total repair estimate is $25,000.
The insurer may agree that $15,000 is covered but say $10,000 is related to excluded wear and tear.
In that case, you can ask for an itemized explanation showing:
- What was approved
- What was denied
- Why each part was treated differently
- Which policy section applies
The NAIC advises homeowners to ask for an explanation when they disagree with a claim settlement or denial.
What If the Insurance Company Says the Damage Is Below My Deductible?
This is different from a coverage denial.
Imagine:
Repair cost: $1,500
Deductible: $2,000
If the loss is covered but costs less than your deductible, the insurer may not make a payment.
That does not necessarily mean the damage itself is excluded.
The deductible is the amount you are responsible for before insurance pays its share.
The NAIC recommends checking your deductible before filing a claim, especially when the damage is small.
What If My Homeowners Insurance Claim Is Denied Because of Flooding?
This is an important situation.
Standard homeowners insurance generally does not cover flood damage.
Flood insurance is a separate type of insurance.
For example, there is a difference between:
Rain damages your roof → water enters through the damaged roof
and
Floodwater rises from outside and enters your home.
Those situations can involve different insurance coverage.
If your claim was denied because the insurer says the damage was caused by flooding, carefully review the policy language and the evidence about where the water came from.
What If My Claim Is Denied Because of Mold?
Mold claims can be complicated.
The insurer may look at:
- What caused the mold
- How long the problem existed
- Whether the water damage was covered
- Whether the policy has a mold exclusion
- Whether there is a special mold limit
For example, mold caused by a sudden covered water loss may be treated differently from mold caused by years of moisture or poor maintenance.
Read the policy carefully before assuming the entire claim is covered or excluded.
What If My Claim Is Denied Because of Poor Maintenance?
Insurance generally is not designed to pay for every repair needed because a home gets old.
For example:
- An old roof gradually wears out
- Pipes slowly corrode
- A foundation develops long-term cracks
- Paint peels over many years
These problems may be treated differently from sudden damage caused by a covered event.
If your insurer says poor maintenance caused the loss, ask for:
- The exact reason
- The policy section
- The evidence used
- An explanation of whether any part of the damage is covered
What Documents Should You Keep After a Claim Denial?
Create one folder for the entire claim.
Keep:
Insurance documents
- Policy
- Declarations page
- Endorsements
- Renewal documents
Claim documents
- Claim number
- Denial letter
- Adjuster reports
- Inspection reports
- Settlement offers
Damage evidence
- Photos
- Videos
- Contractor estimates
- Repair invoices
Communication
- Emails
- Letters
- Text messages
- Notes from phone calls
Other documents
- Police report
- Weather records
- Receipts
- Previous inspection reports
The NAIC recommends keeping records of communications and supporting documents when dealing with an insurance complaint.
Keep a Record of Every Conversation
This simple step can save you a lot of trouble.
Whenever you speak with the insurer, write down:
- Date
- Time
- Name of the person
- Department
- Claim number
- What was discussed
- What the insurer said would happen next
For example:
September 24, 2026 — 2:30 PM
Person: Claims representative
Claim: #123456
Discussion: Representative said the denial was based on wear and tear. Requested written explanation.
This creates a clear timeline.
Can You Appeal a Homeowners Insurance Claim Denial?
You may be able to ask the insurer to reconsider or review a denied claim.
The exact process and deadlines can vary by state and policy.
Start by reading your denial letter and policy.
Look for information about:
- Reconsideration
- Dispute process
- Appraisal
- Mediation
- Arbitration
- Complaint procedures
- Legal deadlines
Do not assume every state or insurance company uses the same process.
For a serious dispute, check your state insurance department’s rules or speak with a qualified professional.
What Is an Appraisal in a Homeowners Insurance Dispute?
Some homeowners policies contain an appraisal process for disagreements about the amount of a loss.
This is different from a dispute about whether the policy covers the loss at all.
For example:
Both sides agree the storm damage is covered, but they disagree about whether repairs cost $20,000 or $35,000.
An appraisal process may be relevant if the policy allows it.
But:
The insurer says the damage is completely excluded.
That is a coverage dispute, which can be different from a disagreement about the amount of damage.
Read your policy carefully before asking for appraisal.
When Should You Contact a Lawyer?
You do not necessarily need a lawyer for every denied claim.
But legal advice may be worth considering when:
- The claim is very large
- Your home has major structural damage
- The insurer denies a large loss
- You strongly disagree about what the policy covers
- There is a serious dispute about the cause of damage
- You believe the insurer violated state insurance rules
- You are facing a legal deadline
Before hiring an attorney, ask about fees and how the lawyer would handle the case.
Should You Hire a Public Adjuster?
A public adjuster works for the policyholder rather than the insurance company.
They can help:
- Review property damage
- Prepare claim documents
- Estimate repair costs
- Negotiate with the insurer
However, public adjusters charge fees, and state rules vary.
The NAIC recommends understanding the fee agreement and checking whether the adjuster is licensed in your state.
For a small claim, paying a professional may not make financial sense.
For a large or complicated loss, some homeowners may decide that professional help is useful.
Homeowners Insurance Claim Denied: What Not to Do
Avoid these mistakes.
Do not ignore the denial letter
It may contain important information about your rights and next steps.
Do not throw away your evidence
Keep photos, receipts, reports, and damaged property when it is safe and practical.
Do not rely only on phone calls
Ask for important decisions and explanations in writing.
Do not exaggerate your claim
Give accurate information about what happened and what was damaged.
Do not make permanent repairs before documenting the damage
If possible, take photos and videos before major repairs.
The NAIC advises homeowners to document damage and avoid permanent repairs before inspection when possible.
Do not miss deadlines
Insurance policies and state laws can have deadlines for reporting losses, requesting reviews, or taking legal action.
Simple Example: Homeowners Insurance Claim Denied
Imagine John owns a home in Texas.
A severe storm damages his roof.
John files a homeowners insurance claim.
The insurer sends an adjuster.
A few weeks later, John receives a denial saying the roof damage was caused by long-term wear and tear rather than the storm.
John believes the storm caused the damage.
Instead of immediately giving up, he:
- Requests the denial in writing.
- Reads the policy.
- Gets the adjuster’s report.
- Collects photos taken before and after the storm.
- Gets a roof inspection from a qualified professional.
- Sends the new information to the insurer.
- Asks for the claim to be reviewed again.
- Contacts the Texas Department of Insurance if the issue cannot be resolved.
This is an illustrative example, not a real claim.
The result of any actual claim depends on the policy, facts, evidence, and applicable state law.
Homeowners Insurance Claim Denied Checklist
Use this simple checklist:
☐ Get the denial in writing
☐ Read the reason carefully
☐ Find the policy section mentioned
☐ Check the exclusions
☐ Check your deductible
☐ Gather photos and videos
☐ Collect repair estimates
☐ Keep receipts and reports
☐ Record every conversation
☐ Ask the insurer to review the claim
☐ Check your state’s insurance department
☐ Consider professional help for a large dispute
Frequently Asked Questions
What should I do if my homeowners insurance claim is denied?
First, ask the insurer for a written explanation of the denial. Then compare the reason with your policy, gather supporting evidence, and ask the insurer to review the decision if you believe something was missed. If you still cannot resolve the issue, your state insurance department may be able to help.
Why would a homeowners insurance claim be denied?
A claim can be denied for many reasons, including an excluded cause of damage, wear and tear, poor maintenance, lack of proof, policy limits, or other policy conditions. The exact reason should be checked against your policy and the insurer’s written explanation.
Can I appeal a denied homeowners insurance claim?
You may be able to ask the insurance company to reconsider or review the claim. The process and deadlines depend on your policy and state. Check the denial letter for instructions and keep copies of everything you submit.
Can an insurance company deny a claim without giving a reason?
Insurance claim rules vary by state. NAIC claims standards say denial notices may need to explain the basis for the denial and identify the relevant policy provision or exclusion where required by law. Ask your insurer for a written explanation.
Can I sue my homeowners insurance company for denying my claim?
A denied claim does not automatically mean you should sue. First review the denial, policy, and evidence and use available claim review or complaint processes. For a large dispute or possible legal issue, consider speaking with an insurance attorney about your specific situation.
Can I file a complaint against my homeowners insurance company?
Yes. If you have tried to resolve the problem with the insurer and remain dissatisfied, you can contact your state department of insurance. State insurance departments can investigate certain complaints involving claim denials, delays, and other insurance issues.
How long do I have to appeal a homeowners insurance claim denial?
There is no single nationwide deadline that applies to every homeowners claim. Your policy and state law can set different deadlines. Check the denial letter and policy as soon as possible and contact your state insurance department if you are unsure.
What if my homeowners insurance claim is only partly denied?
Ask for an itemized explanation showing which parts of the claim were approved and which were denied. The insurer should explain the reason for the disputed portion so you can compare it with your policy and supporting evidence.
Can I get another insurance adjuster to look at my claim?
You can ask your insurer questions about its inspection and claim review process. You may also consider getting an independent inspection or professional opinion, especially when the cause or amount of damage is disputed.
What if my insurance claim was denied because of wear and tear?
Ask the insurer to explain exactly which damage it believes was caused by wear and tear and which policy section supports the decision. If you believe a covered event caused the damage, gather photos, inspection reports, maintenance records, and other evidence that may help show what happened.
Final Takeaway
If your homeowners insurance claim is denied, do not assume that you have no options.
Start by getting the denial in writing and understanding the exact reason.
Then:
Read the policy → gather evidence → ask for a review → keep records → contact your state insurance department if needed.
The most important thing is to compare the insurer’s reason with the actual policy language.
A denial can involve a genuine coverage exclusion, a disagreement about the cause of damage, a problem with documentation, or a dispute about the amount of the loss. The answer depends on the facts of your claim and the policy you purchased.
For a large or complicated dispute, professional advice may be worth considering.
Why Maintain Market Is Different
At Maintain Market, we explain insurance topics in simple, everyday language.
Instead of making readers search through complicated insurance terms, we focus on practical questions:
- Why was my claim denied?
- What should I do next?
- What documents do I need?
- Can I ask the insurer to review it?
- When should I contact my state insurance department?
- When might professional help make sense?
Insurance policies are contracts, and coverage can vary by insurer and state.
Our goal is to help U.S. homeowners understand the basic process so they can ask better questions and make informed decisions about their own claims.
References
- NAIC — Homeowners Insurance
- NAIC — Filing a Homeowners Claim
- NAIC — Settling a Homeowners Insurance Claim
- NAIC — How to File an Insurance Complaint
- NAIC — Get Smart About Your Insurance Coverage
Editorial Review
This article is for general educational purposes for homeowners in the United States. Insurance claim rules, deadlines, coverage, exclusions, and complaint procedures can vary by policy and state. Readers should review their own insurance policy and contact their insurer, state insurance department, licensed public adjuster, or attorney when appropriate for advice about a specific claim.