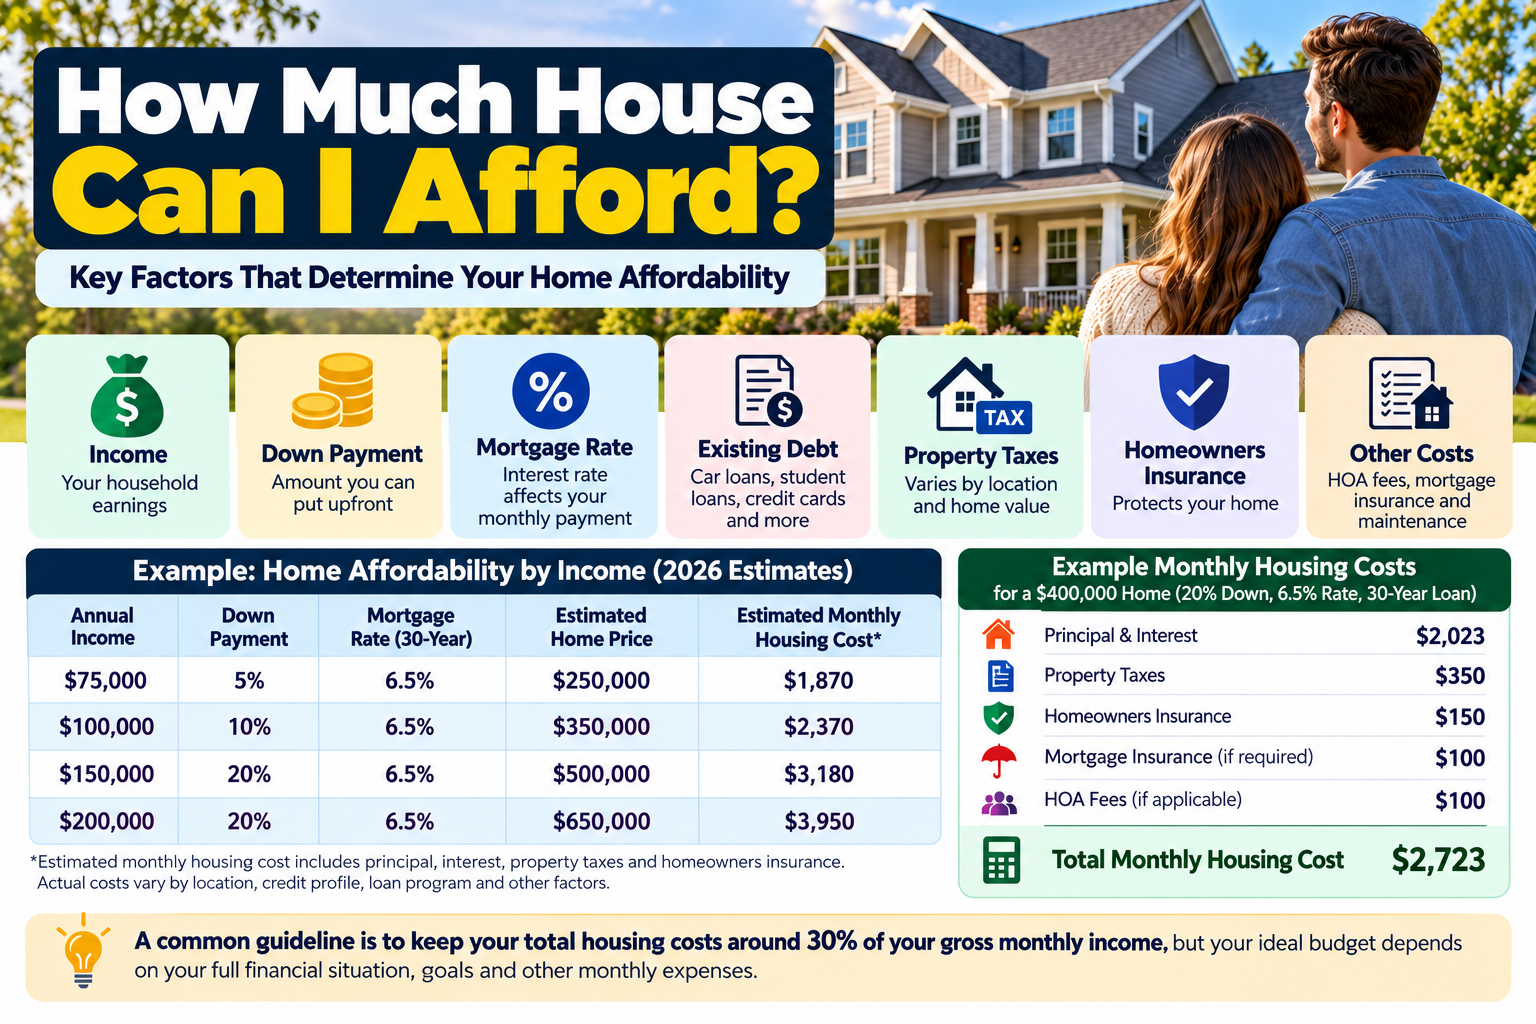
Wondering how much house you can afford? The answer depends on more than your salary. Your down payment, mortgage rate, existing debts, credit profile, property taxes, homeowners insurance, mortgage insurance, HOA fees and other household expenses all affect the home price that fits your budget.
A lender may approve you for a certain mortgage amount, but that doesn’t necessarily mean you should spend that much. The CFPB recommends focusing on a mortgage payment that fits comfortably within your overall budget rather than simply buying the most expensive home a lender will approve.
Quick Answer: How Much House Can I Afford?
There is no single income-to-home-price formula that works for everyone.
As a rough starting point, Freddie Mac says multiplying annual gross income by 2.5 can provide a basic estimate of an affordable home price, but it emphasizes that debt, credit history and interest rates can change the result.
For example:
| Annual Gross Income | 2.5× Income Estimate |
|---|---|
| $50,000 | $125,000 |
| $75,000 | $187,500 |
| $100,000 | $250,000 |
| $125,000 | $312,500 |
| $150,000 | $375,000 |
| $200,000 | $500,000 |
Important: This is only a rough starting point—not a mortgage approval formula.
A more useful calculation considers your monthly housing budget, down payment, interest rate, existing debt and property costs.
1. Start With Your Gross Monthly Income
Your first step is to determine your gross monthly household income.
Gross income means income before taxes and other deductions.
Example
Suppose you earn:
$100,000 per year
Your gross monthly income is:
$100,000 ÷ 12 = $8,333
If you and your spouse both earn income, you may use qualifying household income where appropriate.
However, don’t assume every dollar of household income will automatically qualify for a mortgage. Lenders have their own income-verification and underwriting requirements.
2. Don’t Spend Your Entire Income on the Mortgage
A common mistake is calculating affordability using only the mortgage principal and interest.
Your total monthly housing cost can include:
- Principal
- Interest
- Property taxes
- Homeowners insurance
- Mortgage insurance
- HOA dues
- Flood insurance, if applicable
- Other property-related costs
The CFPB specifically recommends including these costs when determining what you can afford.
Example
Suppose your target total housing budget is:
$2,500/month
You estimate:
- Property taxes: $350
- Homeowners insurance: $150
- Mortgage insurance: $100
That leaves:
$2,500 − $350 − $150 − $100 = $1,900
So approximately $1,900 is available for principal and interest.
That $1,900 figure—not $2,500—is what you would use to estimate the mortgage amount you can support.
3. Calculate Your Debt-to-Income Ratio
Your existing debts can significantly reduce how much house you can comfortably afford.
Debt-to-income ratio, or DTI, compares your monthly debt obligations with your gross monthly income.
Basic formula
DTI = Total Monthly Debt ÷ Gross Monthly Income × 100
Example
Suppose your gross monthly income is:
$8,333
Your existing monthly debts are:
- Car payment: $450
- Student loan: $300
- Credit cards: $250
Total existing debt:
$1,000/month
Your existing DTI before adding the new mortgage is:
$1,000 ÷ $8,333 × 100 = 12%
You then need to consider the proposed housing payment when assessing your overall debt burden.
Freddie Mac explains that lenders use housing expense and DTI measures when evaluating affordability.
4. Use the 30% Housing Expense Guideline Carefully
Freddie Mac says most lenders suggest spending no more than approximately 30% of gross monthly income on the mortgage payment, including principal, interest, taxes and insurance.
For someone earning $8,333 per month:
$8,333 × 30% = approximately $2,500
That gives a rough housing-payment target of about $2,500.
But this is a guideline, not a universal rule.
If you have:
- Large student loans
- Expensive childcare
- High medical expenses
- Significant credit card debt
- Irregular income
- Large financial goals
- High property taxes
you may want a lower housing budget.
5. Your Down Payment Changes How Much House You Can Afford
Your down payment directly affects the amount you need to borrow.
Example
Suppose you want to purchase a:
$400,000 home
With a 10% down payment:
$400,000 × 10% = $40,000
Estimated mortgage:
$400,000 − $40,000 = $360,000
With a 20% down payment:
$400,000 × 20% = $80,000
Estimated mortgage:
$400,000 − $80,000 = $320,000
The larger down payment reduces the amount borrowed.
It can also affect mortgage insurance and loan pricing. CFPB notes that borrowers putting less than 20% down will often need mortgage insurance, depending on the loan.
6. Don’t Use All Your Savings for the Down Payment
This is one of the most important affordability considerations.
Imagine you have:
$80,000 in savings
You shouldn’t automatically assume:
“$80,000 = my down payment.”
You may also need money for:
- Closing costs
- Moving expenses
- Emergency savings
- Repairs
- Furniture
- Immediate maintenance
- Other financial goals
The CFPB recommends maintaining a financial cushion and accounting for costs beyond the down payment. It notes that closing costs are typically around 2%–5% of the purchase price, although actual costs vary.
Example
For a $400,000 home:
2% closing costs = $8,000
5% closing costs = $20,000
So someone with $80,000 available might not want to put the entire $80,000 toward the down payment.
7. Mortgage Rates Can Change How Much House You Can Afford
Your interest rate has a major effect on your monthly principal-and-interest payment.
Consider an illustrative $400,000 mortgage:
| Loan Rate | Term | Approx. Principal & Interest |
|---|---|---|
| 5.5% | 30 years | ~$2,271/month |
| 6.5% | 30 years | ~$2,528/month |
| 7.5% | 30 years | ~$2,797/month |
| 8.5% | 30 years | ~$3,075/month |
These are illustrative calculations, not current mortgage-rate quotes, and they exclude taxes, insurance, mortgage insurance and HOA costs.
The important lesson is that a higher rate can reduce the home price you can comfortably afford even when your income hasn’t changed.
The CFPB identifies interest rate and loan terms as key factors in determining affordable home price.
8. Compare Home Price With the Full Monthly Payment
Don’t ask only:
“Can I afford a $400,000 house?”
Ask:
“Can I comfortably afford the total monthly cost of owning this $400,000 house?”
Illustrative example
Suppose:
Home price: $400,000
Down payment: $80,000
Mortgage: $320,000
Assume:
- Principal & interest: $2,023
- Property taxes: $350
- Homeowners insurance: $150
- HOA: $100
- Mortgage insurance: $0
Total estimated housing cost:
$2,623/month
The home may technically fit a lender’s underwriting rules but still feel expensive if you have substantial non-housing expenses.
This is why affordability should be based on your complete household budget.
9. Use Your Take-Home Pay as a Reality Check
Mortgage underwriting usually focuses on qualifying income and debts, but your personal budget should also consider the money you actually have available after taxes and deductions.
Example
Suppose:
Gross monthly income: $8,333
Take-home income: $6,200
A $2,600 monthly housing payment represents:
$2,600 ÷ $6,200 = 41.9% of take-home pay
That doesn’t automatically mean the home is unaffordable.
But now consider:
- Food
- Transportation
- Childcare
- Healthcare
- Utilities
- Retirement contributions
- Student loans
- Entertainment
- Emergency savings
- Home maintenance
If the remaining money is too tight, the home may not be a comfortable choice.
Your lender’s maximum isn’t necessarily your personal maximum.
10. Account for Home Maintenance
A house costs more than the mortgage payment.
You may eventually need to pay for:
- HVAC repairs
- Plumbing
- Roof maintenance
- Appliances
- Landscaping
- Pest control
- Electrical work
- Exterior maintenance
- Emergency repairs
The CFPB specifically advises homeowners to consider repairs, maintenance and other homeownership expenses when deciding what they can afford.
That’s why leaving some room in your monthly budget can make homeownership less stressful.
How Much House Can I Afford Based on Income?
Here is a rough starting-point table using Freddie Mac’s 2.5× gross-income guideline.
| Annual Income | Rough Home Price |
|---|---|
| $50,000 | $125,000 |
| $60,000 | $150,000 |
| $75,000 | $187,500 |
| $80,000 | $200,000 |
| $100,000 | $250,000 |
| $120,000 | $300,000 |
| $150,000 | $375,000 |
| $175,000 | $437,500 |
| $200,000 | $500,000 |
| $250,000 | $625,000 |
Again, this is only a rough estimate.
Someone earning $100,000 with $1,000 in monthly debt could have a very different affordability profile from someone earning $100,000 with $3,000 in monthly debt.
Freddie Mac itself says the 2.5× method is only a rough estimate and that interest rates, debt and credit history affect affordability.
How Much House Can I Afford With a $75,000 Salary?
Using the rough 2.5× income guideline:
$75,000 × 2.5 = $187,500
So approximately $187,500 would be a starting estimate.
But let’s go one step further.
Suppose you have:
- $6,250 gross monthly income
- $500 monthly car payment
- $300 student loan
- $200 credit card payments
- $50,000 available for down payment and closing
Your realistic budget could be different from the simple $187,500 estimate.
That’s why income alone shouldn’t determine your target price.
How Much House Can I Afford With a $100,000 Salary?
Using the same rough 2.5× method:
$100,000 × 2.5 = $250,000
That gives you a starting home-price estimate of approximately $250,000.
But suppose you have:
- $8,333 gross monthly income
- $1,500 existing monthly debt
- $20,000 available for the down payment
- High property taxes
- HOA fees
Your comfortable home price could be lower than the simple income multiple suggests.
How Much House Can I Afford With a $150,000 Salary?
Using the rough 2.5× income approach:
$150,000 × 2.5 = $375,000
That gives you a starting estimate of approximately $375,000.
But a household earning $150,000 with $3,000 in monthly debt may have less room for a mortgage than a household earning the same amount with minimal debt.
How Much House Can I Afford With a $200,000 Salary?
Using the same rough calculation:
$200,000 × 2.5 = $500,000
So approximately $500,000 is a starting estimate.
However, interest rates, taxes, insurance, down payment and existing debt can move the actual affordable range significantly.
How Much House Can I Afford With $100,000 Down?
The answer depends on your income and monthly budget.
For example, suppose you have:
$100,000 available
You could potentially use it for:
- Down payment
- Closing costs
- Reserves
- Moving
- Repairs
It doesn’t automatically mean you should purchase a $500,000 home.
Example
$500,000 home
20% down = $100,000
That leaves:
$400,000 mortgage
But you would still need to consider closing costs and whether the monthly payment fits your income.
A Better Way to Calculate How Much House You Can Afford
Instead of relying on one rule, use this five-step process.
Step 1: Calculate gross monthly income
Annual income ÷ 12
Step 2: Calculate your existing monthly debt
Include qualifying debts such as:
- Car loans
- Student loans
- Credit cards
- Personal loans
- Other mortgages
Step 3: Set a comfortable total housing budget
Include:
Principal + Interest + Taxes + Insurance + Mortgage Insurance + HOA
Step 4: Subtract taxes and other housing costs
This gives you the approximate amount available for principal and interest.
Step 5: Calculate the mortgage amount
Use an appropriate mortgage calculator with:
- Loan term
- Interest rate
- Monthly principal-and-interest budget
Then add your planned down payment to estimate a target home price.
This approach closely follows the affordability process recommended by the CFPB.
Illustrative Home Affordability Example
Let’s put everything together.
Buyer profile
Annual income: $120,000
Gross monthly income: $10,000
Existing monthly debt: $800
Savings: $100,000
Planned down payment: $70,000
Emergency reserve: $20,000
Estimated closing costs/reserves: $10,000
Step 1: Housing budget
Using a rough 30% housing guideline:
$10,000 × 30% = $3,000
Step 2: Estimate other housing costs
Suppose:
- Property taxes: $400
- Homeowners insurance: $150
- HOA: $100
- Mortgage insurance: $0
Total:
$650
Step 3: Principal and interest budget
$3,000 − $650 = $2,350
So this buyer could use approximately $2,350/month as an illustrative principal-and-interest target.
Step 4: Estimate the mortgage
The exact mortgage amount depends on the interest rate and loan term.
At an illustrative 6.5% rate on a 30-year fixed mortgage, approximately $2,350/month in principal and interest corresponds to a mortgage of roughly $371,000.
Step 5: Add the down payment
Approximately:
$371,000 + $70,000 = $441,000
So a rough target home price could be around $440,000 under these assumptions.
This is not a recommendation or mortgage approval estimate. It demonstrates how income, debt, taxes, insurance, down payment and interest rates interact.
Lender Approval vs. Comfortable Affordability
This distinction deserves its own section.
| Question | Lender’s Perspective | Your Perspective |
|---|---|---|
| Income | Can it be verified? | Is it stable? |
| Debt | Does it fit underwriting? | Does it leave enough cash flow? |
| Mortgage | How much can be approved? | How much feels comfortable? |
| Savings | Is there enough for closing? | Will I still have an emergency fund? |
| Taxes/insurance | Included in qualification | Can I comfortably absorb increases? |
| Repairs | Usually not fully reflected | Can I pay for unexpected repairs? |
| Retirement | Not necessarily your priority | Do I still save enough? |
| Lifestyle | Not considered fully | Can I maintain my lifestyle? |
The CFPB explicitly warns that the amount you qualify to borrow can be different from the amount you can comfortably afford.
What Credit Score Do I Need to Afford a House?
There isn’t one credit score that determines how much house you can afford.
Your credit score can affect:
- Whether you qualify
- Available mortgage programs
- Interest rate
- Mortgage insurance
- Loan costs
A better interest rate can potentially allow the same monthly budget to support a larger mortgage, while a higher rate can reduce purchasing power.
This is one reason buyers should compare actual mortgage offers rather than calculating affordability from the home price alone.
Does a 20% Down Payment Mean I Can Afford More?
Not automatically.
A 20% down payment can reduce the loan amount and may eliminate the need for conventional private mortgage insurance in many situations.
But you still need to consider:
- Monthly mortgage payment
- Property taxes
- Insurance
- HOA
- Repairs
- Emergency savings
- Other debts
A large down payment doesn’t make an otherwise unaffordable monthly payment affordable.
What About FHA, VA and USDA Loans?
Different mortgage programs can change the amount of cash you need upfront and the costs associated with the loan.
For example:
- FHA loans can offer lower down-payment requirements for qualifying borrowers.
- VA loans can offer eligible borrowers financing with no down payment.
- USDA loans can offer qualifying borrowers no-down-payment financing in eligible areas.
But a lower down payment does not automatically mean you can afford a more expensive home.
The monthly payment and total homeownership costs still matter.
For more information, see our guides on FHA loan requirements, FHA loan down payment, and first time home buyer loans.
How Much Should I Spend on a House?
A safer approach is to determine a comfortable monthly housing payment first, then work backward to a home price.
Ask yourself:
- What can I pay every month?
- How much debt do I already have?
- How much can I put down?
- How much cash will remain afterward?
- What are the property taxes?
- What will homeowners insurance cost?
- Is there an HOA?
- Will I need mortgage insurance?
- Can I still save for retirement?
- Can I handle a major repair?
If the answer to several of these questions is uncomfortable, your target home price may be too high.
Costs People Often Forget When Buying a Home
Your mortgage payment isn’t your complete housing budget.
Remember:
Upfront costs
- Down payment
- Closing costs
- Inspection
- Appraisal
- Moving
- Immediate repairs
Monthly costs
- Principal
- Interest
- Property taxes
- Homeowners insurance
- Mortgage insurance
- HOA fees
- Utilities
- Maintenance
Irregular costs
- Roof repairs
- HVAC replacement
- Plumbing
- Appliances
- Landscaping
- Emergency repairs
The CFPB specifically recommends budgeting for costs such as repairs, maintenance, insurance, taxes and HOA fees.
7 Signs You’re Looking at Too Expensive a House
1. You would have almost no emergency savings
Buying a house shouldn’t leave you financially exposed.
2. The payment requires cutting essential expenses
If the mortgage only works by eliminating basic financial priorities, reconsider the price.
3. You can’t continue saving
Homeownership shouldn’t completely stop retirement or emergency savings.
4. You have significant high-interest debt
Paying expensive credit-card debt while stretching for a large mortgage can create financial pressure.
5. Property taxes are unusually high
Two homes with identical prices can have very different monthly costs.
6. Insurance is expensive
Insurance costs can vary substantially by location and property characteristics.
7. You need every dollar of your income to make the payment
A comfortable budget should leave some room for unexpected expenses.
How to Lower the Amount of House You Need
If your target home price feels too high, you don’t necessarily have to abandon homeownership.
Consider:
- Increasing your down payment
- Paying down high-interest debt
- Improving your credit
- Comparing mortgage lenders
- Looking at a less expensive area
- Considering a smaller home
- Comparing property-tax differences
- Avoiding unnecessary HOA costs
- Waiting until you have a larger emergency fund
- Considering different loan options
A lower purchase price can sometimes improve your financial flexibility more than simply trying to qualify for a larger mortgage.
Frequently Asked Questions
How much house can I afford with a $50,000 salary?
A rough Freddie Mac income-multiple estimate would be around $125,000, using 2.5 times annual gross income. However, your actual affordable price could be higher or lower depending on debts, interest rate, down payment, taxes, insurance and other expenses.
How much house can I afford with a $100,000 salary?
Using the same rough 2.5× guideline, $100,000 of annual income produces a starting estimate of about $250,000. But this should not be treated as a mortgage approval or personal affordability limit.
How much house can I afford with a $150,000 salary?
A simple 2.5× gross-income estimate gives approximately $375,000. Your actual budget depends on your debts, down payment, mortgage rate and total property costs.
How much house can I afford with a $200,000 salary?
A rough 2.5× income estimate gives approximately $500,000. However, a borrower with significant existing debt may comfortably afford less.
Is 30% of income a good mortgage rule?
It can be a useful starting point. Freddie Mac says most lenders suggest keeping the mortgage payment, including principal, interest, taxes and insurance, around or below 30% of gross monthly income. But this is a guideline, not a universal affordability rule.
Should I use gross income or take-home pay?
Mortgage qualification generally uses qualifying gross income, but your personal affordability analysis should also consider take-home pay and your actual household expenses. The two numbers answer different questions.
Does my credit score affect how much house I can afford?
Yes. Credit can affect whether you qualify and the mortgage rate and costs available to you. A lower rate can reduce the monthly payment for a given loan amount.
How much should I have saved before buying a house?
You need more than the down payment. You should also consider closing costs, moving expenses, repairs and an emergency cushion. The CFPB recommends accounting for these expenses rather than putting every available dollar into the down payment.
Can I afford a house with 5% down?
Possibly. Many mortgage options allow down payments below 20%, although the specific minimum depends on the loan and lender. A smaller down payment can increase the loan amount and may result in mortgage insurance or other costs.
Does a lender’s preapproval tell me how much house I can afford?
It tells you how much the lender may be willing to lend based on its underwriting, but it doesn’t necessarily tell you what fits comfortably within your household budget. The CFPB specifically distinguishes borrowing qualification from personal affordability.
Simple How-Much-House-Can-I-Afford Checklist
Before setting your home-shopping budget, calculate:
- Gross annual income
- Gross monthly income
- Existing monthly debt
- Target housing payment
- Property taxes
- Homeowners insurance
- Mortgage insurance
- HOA fees
- Down payment
- Closing costs
- Emergency savings
- Mortgage interest rate
- Mortgage term
- Expected maintenance costs
- Retirement savings
- Other household expenses
Then compare the resulting payment with your actual monthly budget.
Final Takeaway
The answer to how much house can I afford isn’t simply a multiple of your salary.
A better calculation combines:
Income + debts + down payment + interest rate + taxes + insurance + mortgage insurance + HOA + other household expenses
A lender may approve a larger mortgage than you actually want.
The goal should be to buy a home that you can comfortably afford while still saving money, handling unexpected expenses and maintaining your other financial priorities.
Before making an offer, run your numbers using a realistic interest rate and actual property taxes and insurance for the home you’re considering. Then compare the result with your monthly budget—not just the lender’s maximum approval.
Why Maintain Market Is Different
Maintain Market doesn’t treat mortgage affordability as a simple salary multiplier.
We combine:
- Income-based estimates
- Monthly payment calculations
- Down-payment scenarios
- Interest-rate sensitivity
- Taxes and insurance
- Mortgage insurance
- Existing debt
- Emergency savings
- Illustrative buyer scenarios
- Comparison tables
- Practical affordability checks
Most importantly, we distinguish what you may qualify for from what you can comfortably afford.
That distinction matters because the largest mortgage a lender will approve isn’t necessarily the smartest mortgage for your household.
References
- CFPB — How Can I Figure Out If I Can Afford to Buy a Home?
- CFPB — Decide How Much You Want to Spend on a Home
- CFPB — Figure Out How Much You Want to Spend
- CFPB — Mortgage Insurance
- CFPB — Determine Your Down Payment
- Freddie Mac — How Much Can You Afford?
- Freddie Mac — What Can You Afford?
- Freddie Mac — Homebuying Budget Calculator
Editorial Review
Reviewed for U.S. mortgage affordability concepts, housing expense calculations, debt-to-income considerations, down payments, mortgage insurance, closing costs and homeownership expenses.
Examples in this article are illustrative calculations rather than personalized financial or mortgage advice. Mortgage rates, lender requirements, property taxes, insurance costs and loan terms vary.