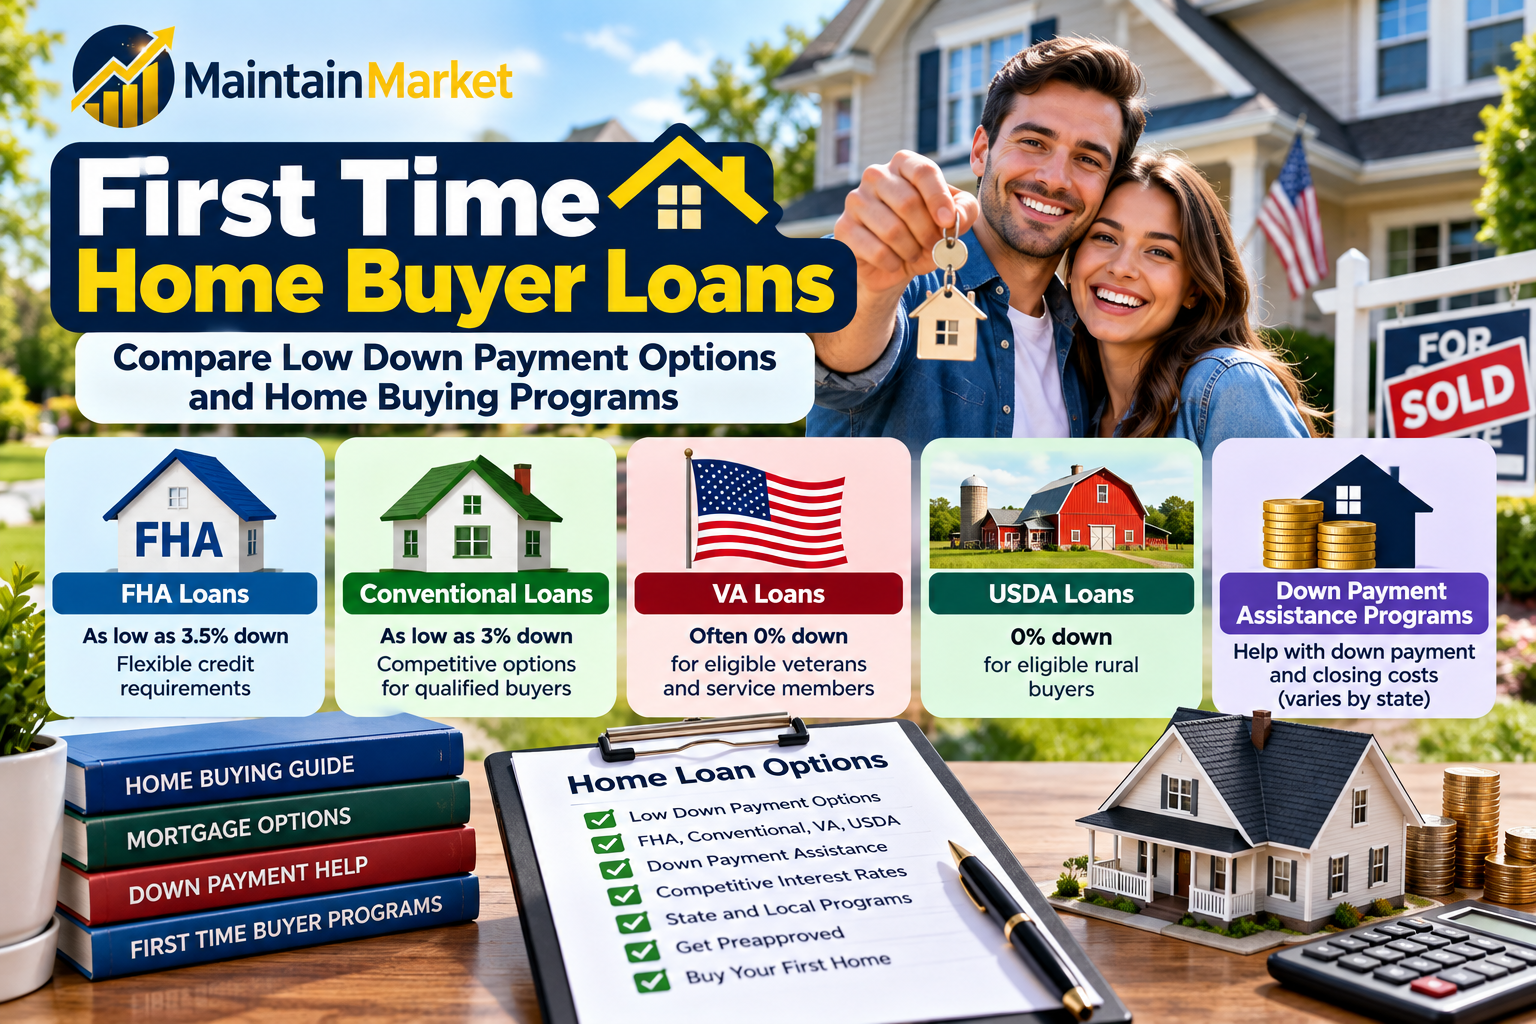
If you’re searching for first time home buyer loans, you have several mortgage options to consider in the United States. FHA, conventional, VA, USDA, and state or local programs can have different down payment, credit, income, property, and eligibility requirements. The right loan depends on your finances, the home you want to buy, and which programs you qualify for.
Quick Answer: What Are the Best First-Time Home Buyer Loan Options?
First-time buyers commonly compare these options:
| Loan or Program | Typical Down Payment | Designed For | Key Feature |
|---|---|---|---|
| FHA Loan | As low as 3.5% | Buyers needing flexible qualification | Lower down payment and credit flexibility |
| Conventional 3% Loan | As low as 3% | Qualified buyers | Low down payment without FHA insurance |
| VA Loan | Often 0% | Eligible veterans/service members | No down payment may be available |
| USDA Loan | 0% | Eligible rural buyers | 100% financing for qualifying borrowers |
| HomeReady | As low as 3% | Eligible low-to-moderate-income buyers | Flexible conventional financing |
| Home Possible | As low as 3% | Eligible low-to-moderate-income buyers | Flexible funds and reduced mortgage insurance |
| HomeOne | As low as 3% | Qualified first-time buyers | Conventional option specifically for first-time buyers |
| State HFA Programs | Varies | Eligible state residents | May combine mortgages with assistance |
| Down Payment Assistance Programs | Varies | Eligible buyers | Help with down payment or closing costs |
| Special Local Programs | Varies | Location or occupation-based buyers | May target specific communities or professions |
The percentages above are program-level starting points, not guarantees. Lenders can have additional requirements, and eligibility depends on the specific loan program.
What Is a First-Time Home Buyer?
The phrase “first-time home buyer” does not always mean you have literally never owned a home.
Many mortgage programs generally use a three-year rule. For example, Fannie Mae defines a first-time homebuyer as someone who is purchasing a principal residence and had no ownership interest in a residential property during the three years before the purchase.
Some programs have their own definitions, so you should check the rules for the specific mortgage or assistance program.
This means someone who owned a home several years ago may potentially qualify for certain first-time buyer programs again.
1. FHA Loans
FHA loans are one of the most commonly considered options for first-time buyers who want a lower down payment or more flexible credit requirements.
An FHA-insured mortgage is issued by an approved private lender and insured by the Federal Housing Administration.
Down payment
An FHA loan can allow a down payment as low as 3.5% when the borrower meets the applicable credit requirements.
For some borrowers with lower credit scores, a higher down payment may be required.
Why first-time buyers consider FHA loans
FHA financing can be useful for buyers who:
- Have limited savings
- Have less-than-perfect credit
- Want a lower down payment
- Need a government-backed mortgage
- Are purchasing a primary residence
FHA loans also have mortgage insurance costs that need to be included when comparing the total cost.
Example
Suppose you purchase a $300,000 home.
A 3.5% down payment would be:
$300,000 × 3.5% = $10,500
That does not mean $10,500 is all the cash you’ll need. Closing costs, prepaid expenses, inspections, moving expenses, reserves, and other costs may also apply.
2. Conventional 3% Down Payment Loans
A conventional mortgage is not part of a specific government loan program.
Some conventional programs allow qualified borrowers to purchase a home with as little as 3% down.
This can be particularly useful for first-time buyers who have good enough credit and income to qualify for conventional financing.
Potential advantages
A conventional loan may offer:
- 3% down payment options
- Different mortgage insurance structures
- Flexible property choices
- Potentially lower costs than FHA for some borrowers
- Mortgage insurance that can generally be canceled once applicable requirements are met
The exact cost depends on your credit profile, down payment, loan terms, property and lender.
Example
For a $350,000 home:
3% down = $10,500
Again, this is only the down payment. You should budget separately for closing costs and other cash requirements.
3. VA Loans
If you’re an eligible veteran, active-duty service member or another qualifying borrower, a VA-backed purchase loan can be an important option.
VA-backed purchase loans can often be used with no down payment, provided the borrower and property meet applicable requirements.
The VA says borrowers still need to meet credit, income and other requirements from both the VA and lender.
Potential benefits
Depending on eligibility and circumstances, a VA loan can offer:
- No down payment
- No monthly mortgage insurance
- Competitive loan terms
- Ability to purchase a primary residence
- Potential reuse of VA loan benefits
A VA funding fee may apply unless the borrower qualifies for an exemption.
Who should investigate VA financing?
Consider checking VA eligibility if you are:
- An eligible veteran
- An active-duty service member
- An eligible member of the National Guard or Reserve
- An eligible surviving spouse
You will generally need a Certificate of Eligibility (COE).
4. USDA Loans
USDA loans are designed for eligible borrowers purchasing homes in qualifying rural areas.
One of their biggest attractions is that qualifying borrowers may be able to obtain 100% financing, meaning no down payment may be required.
USDA eligibility depends on more than simply living outside a major city.
The property must be in an eligible area, household income must meet program requirements, and the home must generally be used as the borrower’s primary residence.
USDA may be worth investigating if:
- You’re buying outside a major urban area
- Your household income falls within program limits
- You want a low- or no-down-payment option
- The property is eligible
- You can meet the program’s underwriting requirements
USDA loans also have upfront and ongoing guarantee fees that should be included when comparing total costs.
5. Fannie Mae HomeReady
HomeReady is a conventional mortgage program from Fannie Mae designed to expand access to homeownership for eligible borrowers.
The program can offer down payments as low as 3%.
It can be particularly relevant to buyers with lower or moderate incomes who meet the program’s eligibility requirements.
Features can include:
- 3% down payment
- Flexible sources of funds
- Reduced mortgage insurance requirements in applicable situations
- Homeownership education
- Potentially flexible income and underwriting features
HomeReady has specific eligibility requirements, including income limits in many circumstances.
So don’t assume that simply being a first-time buyer makes you eligible.
6. Freddie Mac Home Possible
Home Possible is another conventional mortgage program that can offer a down payment as low as 3% for eligible borrowers.
Freddie Mac says the program is designed for very low-, low- and moderate-income borrowers and offers flexibility in how down payment and closing-cost funds can be sourced.
Depending on the borrower’s situation, eligible sources can include:
- Gifts
- Grants
- Employer assistance
- Secondary financing
- Other permitted sources
Home Possible also has income and other eligibility requirements.
For first-time buyers, homeownership education may be required in certain circumstances.
7. Freddie Mac HomeOne
HomeOne is specifically designed for qualified first-time homebuyers and can allow a down payment as low as 3%.
Unlike some income-targeted programs, HomeOne is available regardless of income level or geographic location, subject to program rules.
It can be used for eligible single-family properties, including certain townhomes and condominiums.
Why it can matter
For a buyer who wants:
- Conventional financing
- A 3% down payment
- A program specifically serving first-time buyers
HomeOne can be worth discussing with a lender.
8. State Housing Finance Agency Programs
One of the most overlooked areas for first-time buyers is the housing finance agency (HFA) in their state.
State and local housing agencies may offer programs that combine a mortgage with assistance for:
- Down payments
- Closing costs
- Reduced-interest financing
- Homebuyer education
- Other homeownership expenses
Eligibility varies significantly by state and program.
Some programs are designed for first-time buyers, while others may also serve repeat buyers or specific groups.
Why this matters
You might qualify for a standard FHA or conventional mortgage and a separate assistance program.
That means you shouldn’t compare only:
FHA vs. conventional
You should also ask:
“Can I combine this mortgage with a state or local first-time buyer assistance program?”
9. Down Payment Assistance Programs
Down payment assistance is not necessarily a separate mortgage.
It can be a grant, second mortgage, deferred loan, forgivable loan, or another form of financial assistance, depending on the program.
Some programs can be paired with FHA or conventional mortgages.
Assistance may help with:
- Down payment
- Closing costs
- Prepaid expenses
- Other eligible purchase expenses
But assistance almost always comes with rules.
You may need to:
- Meet income limits
- Purchase a primary residence
- Complete homebuyer education
- Use an approved lender
- Meet credit requirements
- Stay in the home for a certain period
Some assistance can become repayable if you sell, refinance, move out or otherwise fail to meet program requirements.
Always read the specific program terms.
10. Local and Special-Purpose Home Buyer Programs
Some first-time buyers may qualify for programs based on where they live, their income, occupation or other eligibility factors.
For example, certain programs may focus on:
- Teachers
- Firefighters
- Public-service employees
- Low- or moderate-income households
- Buyers purchasing in targeted communities
- Certain underserved areas
These programs can vary substantially from one location to another.
This is why a first-time buyer should not assume that a national mortgage comparison tells the whole story.
A HUD-approved housing counselor or local housing finance agency can help identify programs available in your area.
First-Time Home Buyer Loans: Which Option Should You Compare?
Rather than asking which loan is universally “best,” compare the options based on your situation.
| Your situation | Programs worth investigating |
|---|---|
| Limited down payment | FHA, conventional 3%, USDA, VA |
| Eligible veteran/service member | VA |
| Buying in an eligible rural area | USDA |
| Lower-to-moderate income | HomeReady, Home Possible, HFA programs |
| Stronger credit + 3% available | Conventional 3%, HomeOne |
| Need help with closing costs | State/local assistance |
| First-time buyer specifically | HomeOne, FHA, HFA programs |
| Previous homeowner more than 3 years ago | Check first-time buyer definitions again |
| Want to compare multiple options | Get multiple lender offers |
This is not a ranking. Eligibility and total cost should drive the comparison.
How Much Money Do You Need to Buy Your First Home?
The down payment is only one part of your upfront cost.
Your cash requirement can include:
Down payment + closing costs + prepaid expenses + inspections + moving costs + initial repairs + required reserves
For example, imagine a $300,000 home with a 3% down payment.
Down payment = $9,000
But your total cash needed could be higher because of other transaction and ownership expenses.
That’s why putting every available dollar into the down payment isn’t always the best financial decision. You may need cash after closing for repairs, emergencies and other expenses.
Can You Buy Your First Home With No Down Payment?
Yes, some qualified borrowers may be able to.
The most notable examples are:
VA
Eligible borrowers may qualify for a VA-backed purchase loan with no down payment.
USDA
Eligible borrowers purchasing qualifying properties in eligible rural areas may qualify for 100% financing.
Assistance programs
Some state and local programs can reduce the amount of money you personally need to bring to closing.
However, no down payment does not mean no upfront costs.
You may still have closing costs, prepaid expenses, inspections, moving costs and other expenses.
What Credit Score Do You Need for a First-Time Home Buyer Loan?
There is no single credit score that applies to every first-time buyer mortgage.
Different programs and lenders have different requirements.
FHA financing is known for allowing lower credit scores than many conventional options, while conventional programs may require stronger credit depending on the specific product and underwriting.
VA itself does not establish a universal minimum credit score, although lenders may have their own requirements.
The important point is:
Don’t assume that one credit score automatically determines whether you can buy a home.
Ask lenders about the actual program requirements available to you.
What Income Do You Need for a First-Time Home Buyer Loan?
There is no single income level that guarantees mortgage approval.
Lenders generally look at factors such as:
- Income
- Employment
- Existing debts
- Credit history
- Assets
- Down payment
- Property
- Monthly housing payment
- Ability to repay
Your household income can also affect eligibility for certain assistance or specialized mortgage programs.
For example, USDA and some conventional affordable-housing programs have income requirements.
Can First-Time Buyers Get Help With Closing Costs?
Potentially.
State housing finance agencies, local governments and nonprofit organizations may offer programs that help eligible buyers with down payments or closing costs.
Some assistance may be structured as:
- Grants
- Deferred loans
- Forgivable loans
- Second mortgages
- Other assistance
The rules differ significantly.
Don’t assume that an advertised “down payment assistance” program is free money. Find out whether it must be repaid and under what conditions.
FHA vs. Conventional vs. VA vs. USDA
Here’s a simplified comparison:
| Feature | FHA | Conventional | VA | USDA |
|---|---|---|---|---|
| Government-backed/insured | Yes | No | Yes | Yes |
| Potential low down payment | Yes | Yes | Yes | Yes |
| Potential 0% down | No | Generally no | Yes | Yes |
| Rural property requirement | No | No | No | Yes |
| Military eligibility | No | No | Yes | No |
| Mortgage insurance structure | FHA mortgage insurance | PMI may apply | No monthly mortgage insurance | USDA guarantee fees |
| Income limits | Generally no universal FHA income cap | Depends on product | No universal VA income cap | Yes |
| First-time buyer required | No | Some products | No | No |
| Primary residence | Generally yes | Depends on product | Yes for purchase loan | Yes |
The table is a starting point, not an eligibility determination.
How to Compare First-Time Home Buyer Loans
Don’t compare only the advertised interest rate.
Look at the total cost.
Compare:
- Interest rate
- Annual percentage rate (APR)
- Down payment
- Mortgage insurance
- Upfront fees
- Monthly payment
- Closing costs
- Loan term
- Prepayment rules
- Assistance-program requirements
- Cash needed at closing
- Total interest over the life of the loan
Two loans can have similar interest rates but very different total costs.
Why Getting Multiple Mortgage Offers Matters
Don’t assume your first lender is automatically giving you the best available terms for your situation.
The CFPB recommends comparing multiple mortgage offers and suggests getting at least three preapprovals when shopping for a mortgage.
You can compare:
- Interest rates
- Loan programs
- Lender fees
- Mortgage insurance
- Closing costs
- Monthly payment
- Cash required to close
Comparing offers can reveal that one lender’s FHA, conventional or specialized first-time-buyer option may be structured differently from another lender’s offer.
First-Time Home Buyer Loan Mistakes to Avoid
1. Choosing a loan only because of the lowest down payment
A lower down payment can reduce your upfront cash requirement, but it can also increase your monthly payment or mortgage insurance costs.
2. Ignoring assistance programs
You may be overlooking state or local programs that could help with your upfront costs.
3. Looking only at interest rates
Fees, mortgage insurance and other costs matter too.
4. Using all your savings for the down payment
Homeownership comes with repairs, taxes, insurance and unexpected expenses.
5. Applying without checking your credit
Review your credit before applying so you understand your financial position.
6. Taking on new debt before closing
A new car loan, credit card balance or other debt can affect your mortgage application.
7. Assuming “first-time buyer” means one universal set of rules
Different loan programs define and treat first-time buyers differently.
8. Not comparing lenders
Mortgage pricing can differ between lenders, even for similar borrowers.
A Simple First-Time Home Buyer Loan Strategy
If you’re preparing to buy your first home, follow this sequence.
Step 1: Check your credit
Review your credit reports and understand your current credit position.
Step 2: Calculate your available cash
Separate your potential down payment from your emergency savings.
Step 3: Estimate your affordable monthly payment
Include:
- Principal
- Interest
- Property taxes
- Homeowners insurance
- Mortgage insurance if applicable
- HOA fees if applicable
Step 4: Check special eligibility
Ask whether you qualify for:
- VA
- USDA
- FHA
- State HFA programs
- Local assistance
- Conventional affordable-housing programs
Step 5: Get preapproved
A preapproval can help you understand how much a lender may be willing to lend.
Step 6: Compare multiple lenders
Get multiple offers rather than automatically accepting the first one.
Step 7: Compare the Loan Estimates
Look beyond the interest rate and compare the full cost.
First-Time Home Buyer Checklist
Before making an offer, consider having these ready:
- ☐ Credit information
- ☐ Proof of income
- ☐ Employment information
- ☐ Bank statements
- ☐ Down payment savings
- ☐ Tax documents if required
- ☐ Debt information
- ☐ Preapproval
- ☐ Estimated closing costs
- ☐ Emergency savings
- ☐ Homeowners insurance estimate
- ☐ Property tax estimate
- ☐ HOA costs if applicable
- ☐ Information about available assistance programs
Frequently Asked Questions
What are the most common first-time home buyer loans?
Common options include FHA, conventional mortgages, VA loans for eligible borrowers, USDA loans for eligible rural buyers, and specialized conventional products such as HomeReady, Home Possible and HomeOne.
State and local housing programs can also provide mortgages or assistance that work alongside these loan types.
Is FHA the best loan for first-time home buyers?
There is no single best loan for every first-time buyer. FHA can be useful for borrowers who need a lower down payment or more flexible credit requirements, but a conventional loan may have different costs depending on the borrower’s credit and down payment.
Eligible veterans and rural buyers may have access to VA or USDA options that should also be compared.
Can a first-time home buyer get a conventional loan with 3% down?
Yes. Certain conventional mortgage programs allow qualified borrowers to put down as little as 3%.
Examples include eligible Fannie Mae and Freddie Mac programs. Specific income, credit, property and underwriting requirements apply.
Can I get a first-time home buyer loan with bad credit?
Possibly, but your options may be more limited.
FHA loans can accommodate some borrowers with lower credit scores, while lenders may apply additional requirements. Improving your credit before applying may expand the number of mortgage options available to you.
Can I buy a house with no money down?
Some qualified borrowers can purchase with no down payment through programs such as VA or USDA.
However, you may still need money for closing costs, inspections, prepaid expenses, moving and other costs unless those expenses are covered through an eligible assistance program or other permitted source.
How much should a first-time buyer put down?
There is no universal percentage that is right for everyone.
A larger down payment can reduce the loan amount and may reduce certain costs, while a smaller down payment allows you to keep more cash available.
The right amount depends on your savings, monthly budget, loan program, credit profile and financial goals.
Do first-time home buyers get lower mortgage rates?
Not automatically.
Some first-time buyer programs may offer favorable pricing or assistance, but your rate depends on factors such as your credit profile, loan type, market conditions, lender pricing, loan amount and other characteristics.
Compare actual Loan Estimates rather than assuming a first-time buyer automatically receives a lower rate.
Can I use down payment assistance with an FHA loan?
Potentially.
Many state and local programs offer assistance that can be paired with FHA or conventional mortgages. The assistance program will have its own eligibility rules and may have repayment or occupancy requirements.
Can I qualify as a first-time buyer if I owned a home before?
Potentially.
Many programs use a three-year ownership test, meaning someone who has not owned a residential property for the previous three years may qualify under that program’s definition.
Always check the specific program because definitions and exceptions can differ.
Final Takeaway
First time home buyer loans are not limited to one mortgage program.
Depending on your circumstances, you may be able to compare FHA, conventional, VA, USDA, HomeReady, Home Possible, HomeOne and state or local housing programs.
The most important step is to compare the complete cost and eligibility requirements, not simply the minimum down payment.
Before choosing a mortgage, compare:
- Down payment
- Interest rate
- APR
- Mortgage insurance
- Closing costs
- Monthly payment
- Loan term
- Assistance programs
- Eligibility requirements
- Cash remaining after closing
And don’t forget to check your state and local programs. A first-time buyer may have access to assistance that isn’t obvious from a basic FHA-versus-conventional comparison.
Why Maintain Market Is Different
Maintain Market doesn’t treat “first-time buyer” as a single mortgage category.
Instead, we break down the major loan programs and explain how down payments, mortgage insurance, eligibility, assistance programs and total borrowing costs can change the decision.
Our goal is to help readers understand the trade-offs behind the mortgage, not simply promote the loan with the lowest advertised down payment.
References
- CFPB — First-Time Home Buyer Programs
- CFPB — Shopping for a Mortgage
- HUD — FHA Loans
- HUD — Buying a Home
- VA — VA-Backed Purchase Loan
- USDA — Single Family Housing Programs
- USDA — Property & Income Eligibility
- CFPB — Comparing Mortgage Offers
- CFPB — Loan Estimate & Closing Disclosure
- HUD — Single-Family Mortgage Programs
Editorial Review
Reviewed for U.S. mortgage terminology, first-time homebuyer definitions, low-down-payment programs, government-backed mortgage options, conventional mortgage programs and down-payment assistance information.
Mortgage rates, program requirements, loan limits, fees and assistance availability can change. Readers should verify current requirements with the applicable government agency, housing finance agency and lender before applying.